
What if the dealership helps with financing without lending you the money? That’s the key difference with used car financing third party lender Arizona shoppers may encounter. You work with the dealership on the vehicle and application, while an outside lender reviews your information and makes the lending decision. It’s understandable to wonder whether applying commits you to a loan or whether a low monthly payment is the best measure of a deal.
At Any Credit Auto Sales LLC in Chandler, you can browse used vehicles and apply for financing through outside lending partners. Submitting an application starts a review, so take time to understand any proposed terms before deciding how to proceed. You can also get credit help as you consider your options. Approval, rates, and terms depend on the lender and aren’t guaranteed.
This guide explains how dealership-assisted financing works, what information a lender may request, and how to compare more than the monthly payment. You’ll learn to consider the interest rate, loan length, and total amount you’ll repay alongside the vehicle’s price. With a clearer picture, you can weigh your choices with more confidence.
Key Takeaways
- With used car financing third party lender Arizona shoppers can apply through a dealership, but the outside lender reviews the application and determines available terms.
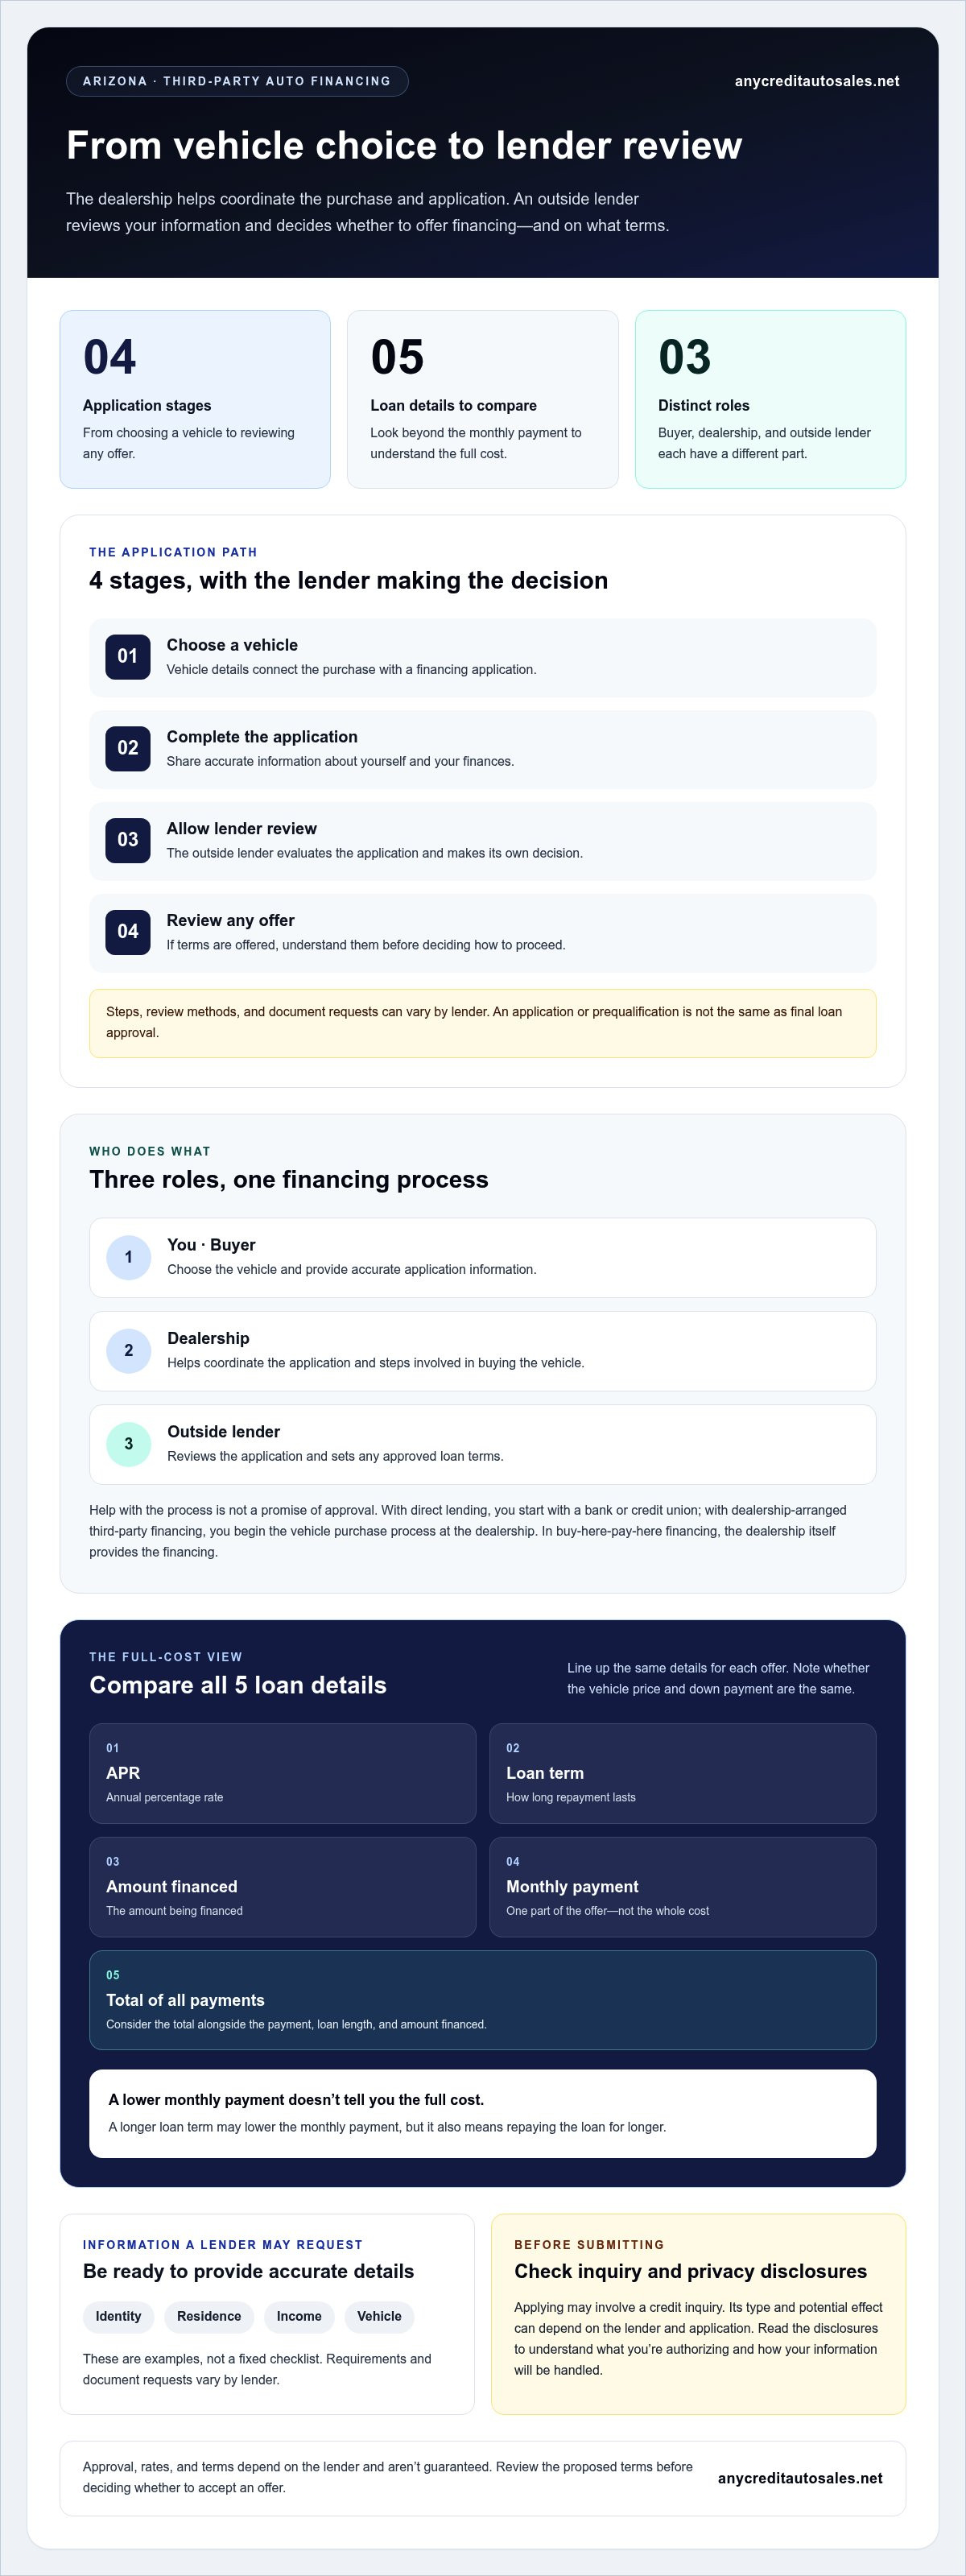
- The process may include choosing a vehicle, completing an application, lender review, and reviewing any offer. Steps and document requests can vary by lender.
- Compare APR, loan term, amount financed, monthly payment, and total payments to understand the full cost of a loan.
- A longer loan term may lower the monthly payment, but it also means repaying the loan for longer.
- Set a budget that accounts for your payment and other ownership costs, then explore used vehicles and financing applications with Any Credit Auto Sales in Chandler.
How used car financing with a third-party lender works in Arizona
With third-party financing, an outside lender provides the loan for a vehicle you purchase from a dealership. The dealership helps connect the vehicle purchase and financing application, but it isn’t the lender. The lender reviews your information, makes its own credit decision, and determines what terms, if any, are available.
This distinction can make the process clearer for Arizona shoppers. If you’re looking at used cars in Chandler or nearby Mesa, Tempe, Phoenix, Queen Creek, or San Tan Valley, the dealership can help coordinate the application alongside your vehicle purchase. The financing decision still belongs to the outside lender. Understanding how loans work, including the role of interest and repayment, can help you make sense of an offer.
Who does what: buyer, dealership, and lender
You choose the vehicle and provide accurate information for the financing application. The dealership helps coordinate the application and steps involved in buying the vehicle. The outside lender reviews the application and sets any approved loan terms. Each role is distinct, so help with the process isn’t a promise of approval.
How dealership-arranged financing differs from direct lending
The main difference is where you begin. With a direct bank or credit union application, you start with that lender to explore financing. With dealership-arranged third-party financing, you begin the vehicle purchase process at the dealership, which connects your application with outside lending partners. Either route can lead to a loan from a financial institution, but the application path differs.
Third-party financing also differs from buy-here-pay-here financing. In a buy-here-pay-here arrangement, the dealership itself provides the financing. With third-party financing, an outside lender evaluates the application and provides the loan, while the dealership sells the vehicle and helps coordinate the purchase process.
Neither route guarantees approval, a lower payment, or better terms. The right fit depends on your situation and the offer available to you. As you explore used car financing third party lender Arizona options, keep the roles straight: you choose the car and share accurate information, the dealership helps connect the steps, and the lender decides whether to offer financing and on what terms.
How an Arizona used-car financing application reaches a third-party lender
With dealership-assisted financing, the application moves from your vehicle search to an outside lender for review. The exact process can vary by lending partner, but it generally follows these steps:
- Choose a vehicle. The vehicle details connect your purchase with a financing application.
- Complete the application. Share accurate information about yourself and your finances.
- Allow lender review. The lender evaluates the application and makes its own decision.
- Review any offer. If terms are offered, understand them before deciding how to proceed.
This is the general path for used car financing third party lender Arizona shoppers may use. Application steps, review methods, and document requests can differ by lender. An application or prequalification is not the same as final loan approval, so review the status and details of any response you receive.
What information may be requested on an auto loan application?
A lender may ask for information about your identity, residence, income, and the vehicle you’re considering. These are examples, not a fixed checklist. Requirements and document requests vary by lender. Provide complete, accurate details, and review the application instructions and privacy information before submitting personal or financial data.
Check what the application says about a credit inquiry. Applying may involve an inquiry, and its type and potential effect can depend on the lender and application. Don’t assume it will be a soft inquiry or have a particular result. Read the disclosures to understand what you’re authorizing and how your information will be handled.
What happens after the lender reviews your application?
The lender may approve an application, decline it, or offer terms subject to its review. If you receive an offer, look beyond whether the payment feels manageable. Consider the proposed payment, loan length, and amount financed together. If anything is unclear, pause and review the terms before accepting them.
Submitting an application isn’t the same as accepting a loan offer or agreeing to buy a vehicle. Review the information presented and decide what makes sense for you. If you’re still exploring options in Chandler, you can browse used car inventory as you consider which vehicle may fit your needs.
Compare third-party used-car financing by the full loan terms
A manageable monthly payment matters, but it doesn’t tell you the full cost of financing. Compare the annual percentage rate (APR), loan term, amount financed, payment, and total of all payments. For a useful comparison, line up the same details for each offer and note whether the vehicle price and down payment are the same. This helps show what’s driving differences between options.
Why the monthly payment is only one part of the offer
A longer loan term can lower the monthly payment by spreading repayment over more time, but you’ll also make payments for longer. Two offers with similar monthly payments may have different loan lengths, amounts financed, or total repayment obligations. Compare the figures rather than choosing by payment alone.
Use a simple comparison sheet. Fill in the figures shown in each offer, and leave a field blank if it isn’t provided. Don’t guess.
| Loan detail | Offer A | Offer B |
|---|---|---|
| APR | Compare offer | Compare offer |
| Loan term | Compare offer | Compare offer |
| Amount financed | Compare offer | Compare offer |
| Monthly payment | Compare offer | Compare offer |
| Total of payments | Compare offer | Compare offer |
Keep optional products or add-ons separate from the vehicle price and base loan terms as you review the paperwork. If an item appears in the amount financed, identify what it is and how it affects the loan. This lets you compare the underlying financing and the full package without mixing the two.
Third-party financing versus direct bank or credit union financing
With direct financing, you start by applying through a bank or credit union, then bring your financing plan into the vehicle search. With dealership-arranged third-party financing, you begin with the vehicle purchase process, and the dealership helps connect your application with outside lenders. Each path links shopping and financing in a different order.
Neither route is automatically better. The lender’s review determines eligibility and available terms, not simply whether you applied directly or through a dealership. For used car financing third party lender Arizona options, compare the written terms and vehicle details side by side. A clear comparison helps you decide with less guesswork.
Get ready to apply for used-car financing in Chandler and the East Valley
Preparation can make the financing process feel more manageable. Before you apply, set a comfortable vehicle budget that includes more than the loan payment. Leave room for ownership costs such as insurance, fuel, registration, and upkeep. Then choose a realistic vehicle range. Knowing what fits your household budget can help you assess financing options without letting the payment alone set your limit.
Whether you’re shopping in Chandler or comparing used-car choices around the East Valley, including Mesa and Tempe, plan your budget before reviewing offers. Lender requirements vary, so prepare accurate personal and income information and follow the application instructions for supporting documents. Don’t assume every lender requests the same paperwork.
A simple checklist before you submit an application
Use this checklist to feel prepared, not pressured. Gather the information you’ll need to complete the application consistently. Decide what payment and loan length feel manageable for your household, then keep your questions in mind as you review any offer.
- Check that your personal and income information is complete and accurate.
- Set a comfortable payment range and consider how long you’re willing to repay.
- Write down questions about APR, amount financed, optional add-ons, and payment schedule.
- Review the application instructions for lender-specific document requests.
These steps can help you approach used car financing third party lender Arizona options with a clearer sense of your priorities. They don’t determine the lender’s decision, but they help you focus on what matters to your budget.
What to do if the proposed terms do not fit
Take a breath and review the full offer. Approval alone doesn’t mean the payment, loan length, or amount financed works for you. Revisit your budget and consider whether a different vehicle choice or other available terms may feel more comfortable. A change to the vehicle or down payment may affect an application, but it can’t guarantee a particular lender decision.
You can pause and consider your options before deciding whether to move forward. If you’re ready to compare vehicles as you plan your budget, explore used cars and financing at Any Credit Auto Sales in Chandler.
Explore used cars and third-party financing with Any Credit Auto Sales
Buying a used car and arranging financing are connected, but they’re separate decisions. Any Credit Auto Sales LLC helps you explore pre-owned vehicles and move through the purchase and financing steps. An outside lending partner reviews your application and makes the lending decision, including whether to offer financing and what terms may be available.
How Any Credit Auto Sales supports the financing process
Any Credit Auto Sales LLC is an independent used-car dealership in Chandler, serving shoppers in nearby communities including Mesa, Tempe, Phoenix, Queen Creek, and San Tan Valley. You can browse pre-owned inventory online and submit an application that connects with outside lending partners. The dealership helps guide you through the vehicle and application process. The lender, not the dealership, evaluates your application and determines any available loan terms.
If you have questions about your credit history, credit help can offer practical guidance as you consider your next steps. That guidance isn’t a promise of loan approval, a specific rate, or a particular offer. Each lender reviews applications individually, so review the process and any proposed terms carefully.
Choose a next step that feels manageable
Start by browsing vehicles and narrowing your choices to options that suit your needs and budget. If you’re ready, submitting a financing application starts the lender review process. An application by itself doesn’t require you to accept an offer or purchase a vehicle. Take your time and decide what works for you.
For shoppers researching used car financing third party lender Arizona options, the central idea is simple: the dealership supports the purchase process, while an outside lender evaluates financing. You can take these steps at your own pace, whether you’re exploring used cars or ready to submit an application.
Browse used cars and start a financing application with Any Credit Auto Sales LLC.
Take your next car-shopping step with confidence
With used car financing third party lender Arizona shoppers work with a dealership on the vehicle and application while an outside lender reviews the request and determines any available terms. Keep the roles clear, and remember that applying is not the same as accepting a loan or committing to a purchase.
As you consider an offer, compare APR, loan length, amount financed, monthly payment, and total payments together. A lower payment may come with a longer repayment period, so look at the full terms and choose a vehicle that fits your budget. Review the details before deciding.
At Any Credit Auto Sales LLC in Chandler, applications connect shoppers with outside lending partners. Credit guidance is also available for shoppers with varied credit histories. It’s practical support, not a promise of approval or a particular offer.
Ready to explore your options? Explore used cars and start your financing application. Take it one step at a time and review each option with care.
Frequently Asked Questions
What does third-party lender financing mean when buying a used car?
Third-party lender financing means an outside financial institution provides the loan for a used car you buy through a dealership. The dealership sells the vehicle and may help coordinate the application, while the lender reviews your information and decides whether to offer financing and on what terms. Any Credit Auto Sales connects applications with outside lending partners for shoppers in Chandler and nearby Arizona communities.
Is dealership-arranged financing the same as buy-here-pay-here financing?
No. With dealership-arranged third-party financing, an outside lender reviews your application and provides any loan. In buy-here-pay-here financing, the dealership itself lends the money. These are different arrangements. Any Credit Auto Sales helps shoppers connect with outside lending partners rather than providing in-house financing. Review the terms and make sure they fit your budget before deciding.
Can I get used-car financing through a third-party lender with challenged credit?
You can submit an application, but approval and terms depend on the lender’s review of your individual situation. Challenged credit doesn’t determine the outcome by itself, and no dealership can promise approval or a particular offer. Any Credit Auto Sales offers credit guidance for shoppers with varied credit histories. That practical support can help you understand your options as you shop in Chandler, Mesa, Tempe, Phoenix, Queen Creek, or San Tan Valley.
What information do I need to apply for a used-car loan in Arizona?
Lenders commonly request information about your identity, residence, income, and the vehicle, but exact requirements vary by lending partner. You may need details such as the vehicle’s year, make, model, or VIN once you’ve chosen one. Follow the application instructions, provide accurate information, and review how to submit it securely. Treat any document list as lender-specific, not a universal Arizona checklist.
Does applying for third-party auto financing affect my credit score?
It can, depending on the type of credit inquiry involved. Don’t assume an application uses a soft inquiry or will have a particular effect on your score. Before submitting, read the application disclosures to understand what credit review you’re authorizing. Inquiry practices can vary by lending partner. A prequalification and a full application may also involve different steps, so review the terms shown for your specific application.
What should I compare when reviewing a third-party car loan offer?
Compare the APR, loan term, amount financed, monthly payment, and total of all payments. A longer term may lower the monthly payment while extending repayment, so consider both the monthly amount and how long you’ll be paying. Review optional products separately from the vehicle price and base loan terms. Comparing the full offer helps you understand the commitment instead of judging it by payment alone.
Can I apply for used-car financing before choosing a vehicle?
You may be able to start an application before choosing a specific car, but the process depends on the lending partner. A lender may need vehicle information to review a final financing request or set terms. Review the application response to understand what stage it represents, since it may not be final approval. Submitting an application doesn’t by itself mean you’ve agreed to buy a vehicle or accept a loan.


