
A difficult credit history doesn’t automatically close the door to a car. Affordable cars for bad credit in Arizona may be within reach through a used-car purchase and a financing application. Buy-here-pay-here financing is one route, but interest rates at those dealerships are likely to be higher than rates from banks, credit unions, or other lenders, according to the Consumer Financial Protection Bureau.
It’s understandable to feel unsure about your options when your credit history has bumps. You deserve a clear explanation of how financing works and practical steps to prepare, without pressure or judgment.
This guide explains how buy-here-pay-here financing differs from applications to third-party lenders, which documents to prepare, and what to consider when your credit history is challenging. You’ll also learn how a Chandler dealership fits into the process and how credit help can support your next steps.
Key Takeaways
- Buy-here-pay-here financing is different from applying through third-party lenders, and its interest rates are likely to be higher than rates from banks, credit unions, or other lenders.
- Use the dealership’s Chandler location to understand where your vehicle search begins and what local steps may be convenient for you.
- Bring paperwork that helps show your identity, income, and current financial situation so you’re ready to discuss possible financing options.
- Bad credit, no credit, or a past bankruptcy doesn’t mean you can’t explore an auto financing application and credit help.
Buy Here Pay Here financing
Buy Here Pay Here (BHPH) means you arrange vehicle financing through the dealership rather than applying through a separate lender. Before choosing this route, compare the full repayment terms with other financing options and read every page of the contract.
Comparing Loan Costs and Vehicle Prices
Compare the vehicle price, amount financed, interest rate, payment schedule, loan length, and every listed fee. A lower payment can still mean a higher total repayment if the loan lasts longer. The Consumer Financial Protection Bureau says interest rates at BHPH dealerships are likely to be higher than rates from banks, credit unions, or other lenders.
To compare offers, write each term side by side and add up all scheduled payments. Include any amount due at signing and fees listed in the contract. Arizona buyers should look beyond the monthly payment and compare the full repayment amount with the vehicle price.
Arizona consumer-protection and lending rules apply to vehicle sales and financing. Review the written sales and financing documents for the price, payment terms, and fees, and keep copies for your records.
Used Car Prices and Loan Risks
There is no single useful price for every used car in Arizona. The price depends on factors such as make, age, mileage, and condition. Compare similar vehicles, then consider the asking price alongside the financing terms rather than treating the monthly payment as the whole cost.
Review no-credit-check offers and subprime auto loans carefully. A higher rate or costly fees can increase the total amount repaid, while a payment that strains your budget can make it harder to keep up. Read the contract before signing and understand what happens if a payment is late.
When searching for affordable cars for bad credit in Arizona, focus on how the vehicle price fits with the loan’s full terms. Ask for clear explanations of listed charges, confirm the contract matches what you agreed to, and keep a copy after signing.
Dealership location and service area
Any Credit Auto Sales is based in Chandler, Arizona, serving shoppers in Chandler, Mesa, Tempe, Phoenix, Queen Creek, and San Tan Valley. If you’re planning a visit, factor in travel time alongside work, family, and other commitments. The dealership’s location can help you plan, while your own travel needs will shape the visit.
Before setting out, map your trip to Chandler and choose a time that leaves room to look at vehicles and discuss financing paperwork. If you’re coming from elsewhere in Arizona, factor in the drive back as well as the trip there. That can help you decide whether to make one focused visit or prepare questions and documents in advance. Don’t plan around an assumed delivery or remote-purchase option.
A simple location check can make the visit easier:
- Save Chandler as the destination and plan your route from your starting point.
- Set aside time to review vehicle choices and financing details in person.
- Bring the documents needed for your financing discussion, rather than making a second trip for paperwork.
- Before leaving, note any questions about the next step and the information you’ll need to keep.
Your home address can shape which practical details matter most. A driver commuting from outside Chandler may want to consider how the vehicle will handle regular travel, while someone nearby may focus on arranging a convenient visit. Either way, match your travel needs to the vehicle’s intended use, then review the purchase and financing terms carefully.
Use the Chandler dealership information as a starting point for planning. That keeps your search grounded in the known location without assuming a specific service boundary across Arizona. A clear plan for reaching Chandler, bringing your paperwork, and discussing your needs can make the next steps easier to manage.
Documents needed for financing approval
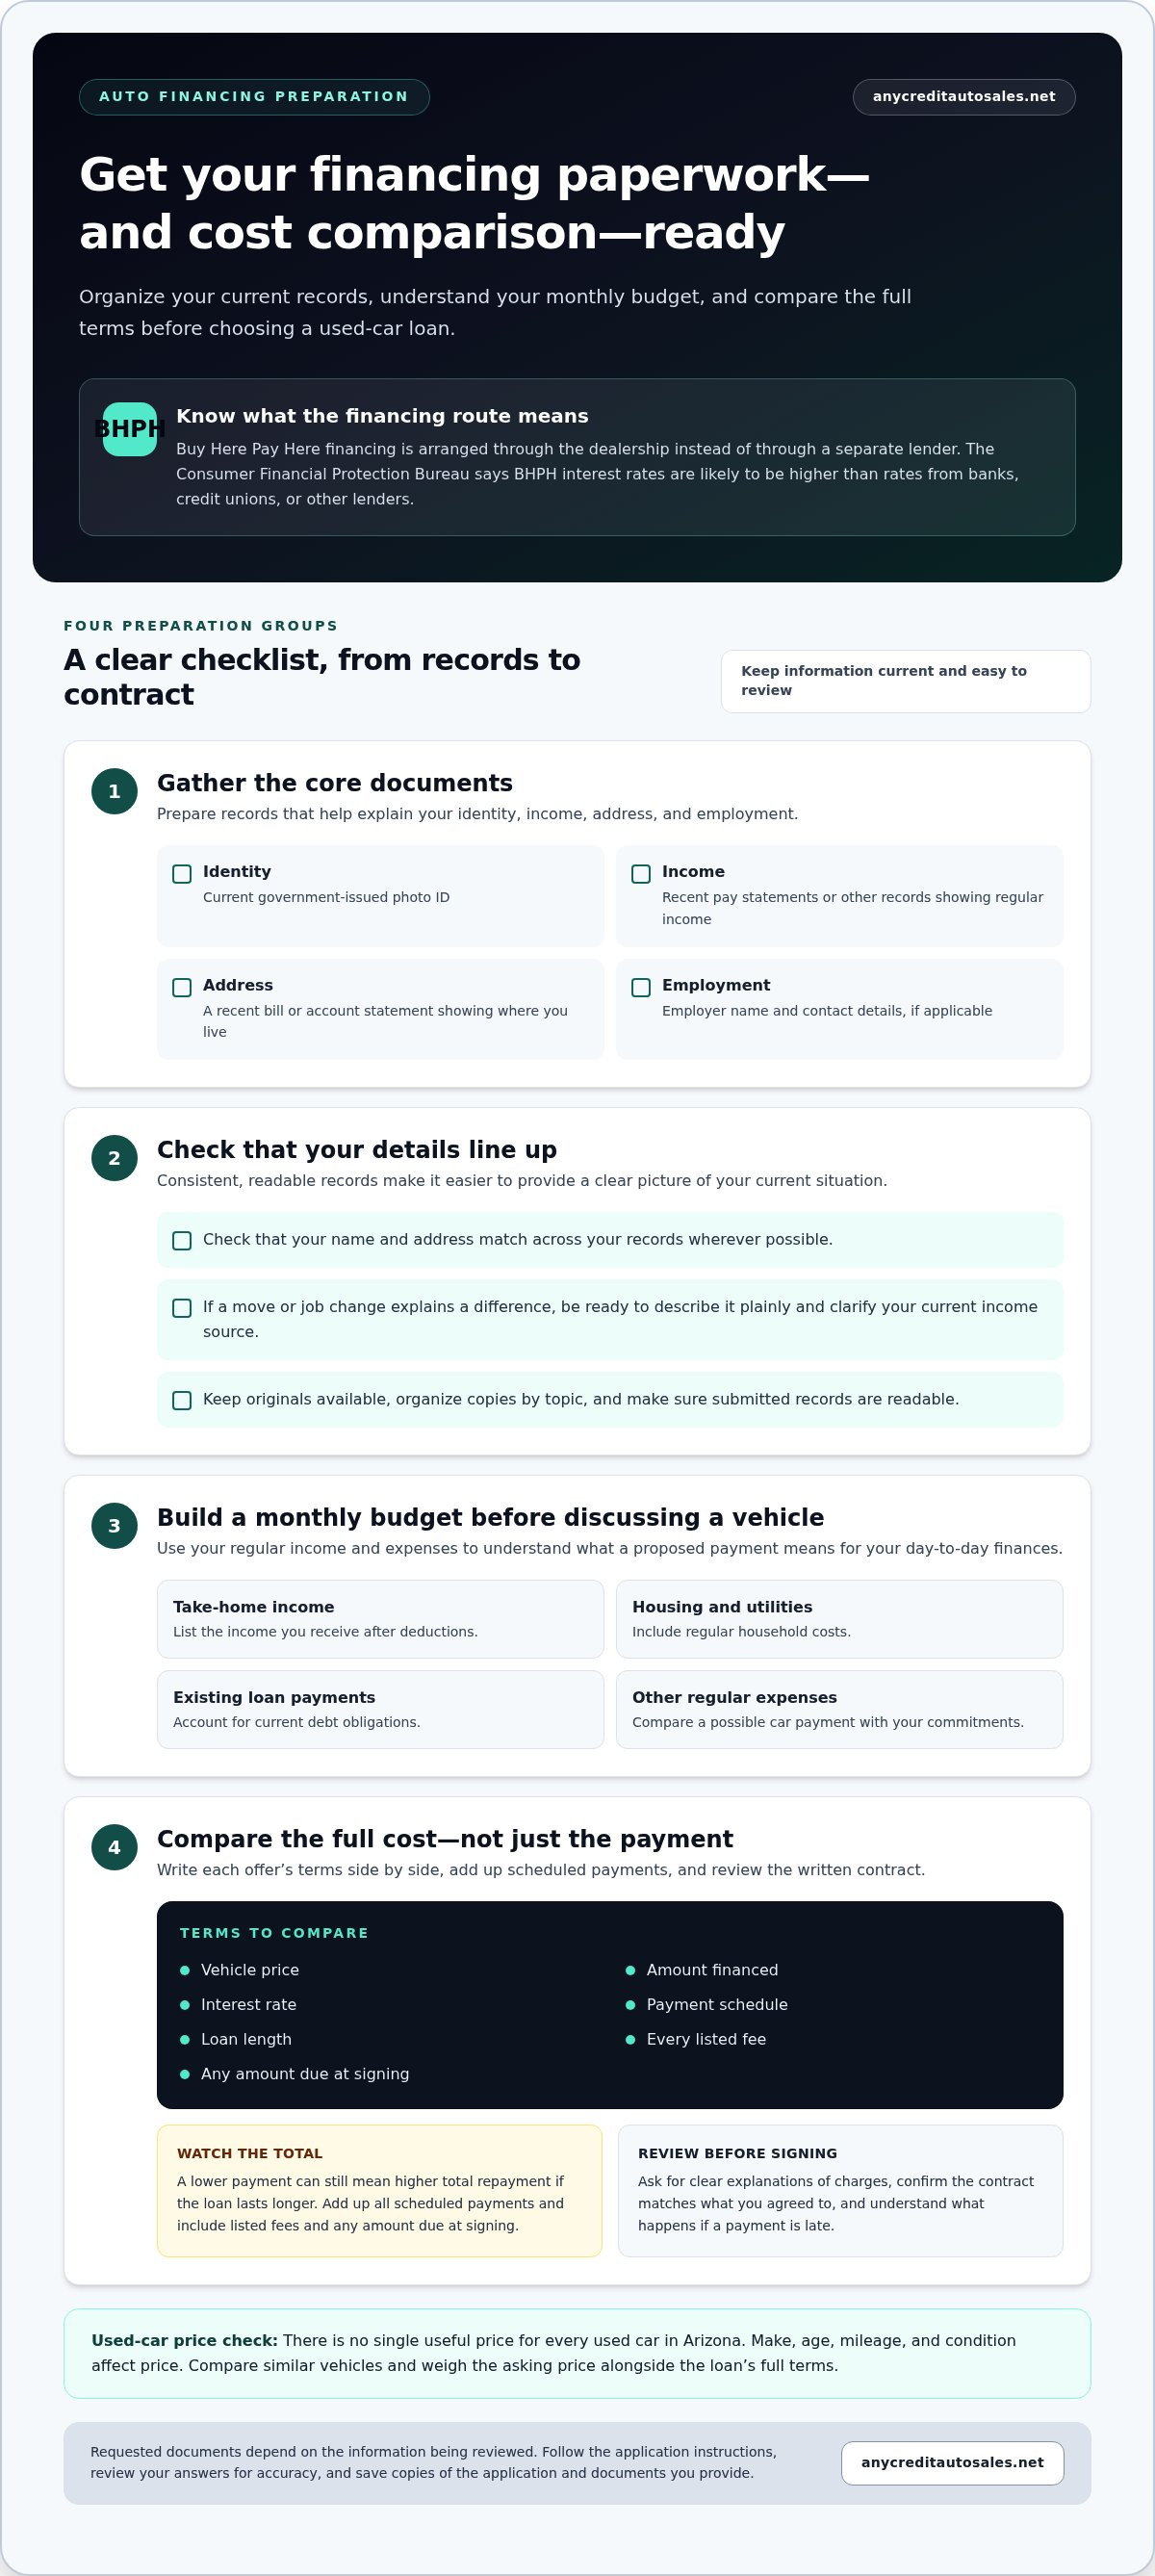
Gather your paperwork before starting an auto financing application. Clear, current records make it easier to provide consistent details about your identity, income, address, and monthly obligations. Keep originals available and organize copies by topic. Use the application instructions as your checklist, since requested documents depend on the information being reviewed.
Prepare documents that help explain your current situation:
- Identity: Have a current government-issued photo ID ready.
- Income: Gather recent pay statements or other records showing regular income.
- Address: Set aside a recent bill or account statement showing where you live.
- Employment: Note your employer’s name and contact details, if applicable.
Check details across your records before submitting an application. Your name and address should match wherever possible. If a recent move or job change explains a difference, be ready to describe it plainly. For example, if a pay statement shows a new employer, bring information that clarifies your current income source.
Make a simple monthly budget before discussing a vehicle. List take-home income, housing costs, utilities, existing loan payments, and other regular expenses. This helps you identify a payment that fits your finances and compare a proposed payment with your day-to-day commitments.
If your credit history includes missed payments or a past bankruptcy, organize paperwork that helps explain your current circumstances. Keep the explanation factual and concise. Separate current income records from older credit documents so the information is easy to follow. Don’t alter or omit details requested in the application.
Before submitting, review every answer for accuracy and make sure attached records are readable. Save a copy of the application and the documents you provide. This gives you a clear record of the information used in your financing discussion and helps you answer questions consistently.
Financing for bad credit, no credit, and prior bankruptcy
Credit challenges don’t tell the whole story of your finances. Focus on the details lenders consider and the loan terms you can manage.
Financing With Credit Challenges
Bad credit, a limited credit history, or a prior bankruptcy can affect how lenders assess an application. Share accurate information about your income, current obligations, and circumstances. A third-party lender may consider several parts of your financial picture. Compare the offered terms carefully, including the rate, payment, loan length, and total repayment.
If your circumstances have changed, organize clear records that show your current situation. For example, recent income records can help explain a job change since older credit events.
Down Payment Expectations
Arizona has no single down payment amount for every bad-credit car loan. The amount depends on the vehicle price, your application, and the lender’s terms. A larger down payment reduces the amount financed, while a smaller one leaves more of the vehicle price in the loan.
Before choosing an amount, review your savings and leave room for regular expenses. Compare the amount due at signing with the resulting loan balance and payment. Don’t commit money needed for essentials just to reduce the amount borrowed.
Rates and Monthly Payments
Your rate and monthly payment depend on factors such as credit history, amount financed, vehicle price, and loan length. A longer term can change the payment while extending how long you owe. Compare the total repayment, not just the monthly amount, and review every charge in the written terms.
To strengthen your credit, review your credit information for errors, keep payments current, and manage existing balances. If your credit improves, compare a refinancing offer with your current loan. Consider the new rate, fees, remaining balance, and total repayment before deciding. You can explore financing options as you plan your next step.
Any Credit Auto Sales: Used Vehicles
Any Credit Auto Sales helps shoppers explore used vehicles, complete an auto financing application, and get credit help. It can be a useful next step if you’re comparing cars while navigating a challenging credit history. The application connects with third-party lenders, so this is not Buy Here Pay Here financing.
Bring your income and identity documents, along with a clear idea of your monthly budget. You can discuss vehicle options and financing steps in light of your circumstances. Credit help can guide you as you consider possible loan options. Review the vehicle price and loan terms together to see how the payment fits your plans.
For a straightforward next step, contact Any Credit Auto Sales to discuss your vehicle search and financing application.
Take Your Next Step With Confidence
Turn your car search into a clear personal plan. Decide what you need the vehicle to handle each day, such as commuting, family errands, or getting to work. Then separate must-haves from features you can do without. This keeps your focus on practical choices rather than pressure to decide quickly.
As you compare affordable cars for bad credit in Arizona, take time to consider whether the vehicle and financing fit your priorities. A thoughtful choice should support your routine without adding avoidable stress. Move forward one decision at a time, with your questions ready and priorities in view.
For help taking that next step, contact Any Credit Auto Sales to discuss your options. A fresh start can begin with a calm conversation and a plan that feels right for you.
Frequently Asked Questions
What are the best affordable used cars for sale in Arizona?
The right choice depends on your daily driving needs, budget, and the vehicle’s condition. A compact car may suit regular city commutes, while an SUV may offer more room for family errands. Compare similar vehicles by mileage, age, features, and stated condition. Drivers in Chandler, Mesa, Tempe, Phoenix, Queen Creek, and San Tan Valley can use these needs to narrow their search.
Which Arizona dealerships offer financing for buyers with bad credit?
Any Credit Auto Sales helps Arizona shoppers apply for financing through third-party lenders and offers credit help. Its local focus includes Chandler, Mesa, Tempe, Phoenix, Queen Creek, and San Tan Valley. Start by identifying a vehicle that fits your needs, then consider the application information and lender terms as part of the same decision.
What credit score is needed to finance a car in Arizona?
No credit score guarantees approval for every Arizona auto loan. Lenders may weigh your credit history alongside income, existing obligations, the vehicle, and the loan request. If your score is low or your credit file is limited, focus on providing accurate, current information. Ask how the offered terms affect the total repayment, not just whether the application can proceed.
Are buy here pay here dealerships in Arizona a good option for bad credit?
Buy-here-pay-here loans may suit some buyers, but compare the full terms before deciding. The Consumer Financial Protection Bureau says interest rates at BHPH dealerships are likely to be higher than rates from banks, credit unions, or other lenders. Any Credit Auto Sales submits financing applications to third-party lenders, a different route from buy-here-pay-here financing.
What documents are needed to get approved for a car loan in Arizona?
Prepare identification, records showing income and residence, and details about your regular financial obligations. Keep information consistent across forms. If your address changed recently, use current records and be ready to explain differences from older paperwork. If a past bankruptcy affects your credit history, organize relevant records so you can clearly describe your current financial situation.


