
What if the monthly payment you focus on isn’t the best way to compare car loans? When you search “used car auto loan Arizona,” you may find different rates, loan terms, and application steps. It’s understandable if the details feel hard to sort through, or if you’re unsure what a lender will review. You can make the process clearer by understanding the loan before choosing a vehicle.
This guide explains the basic parts of a used-car loan, what lenders may consider when reviewing your application, and what information to gather before you apply. You’ll also learn how to compare financing options and set a vehicle budget with more confidence. If you’re shopping in Chandler, Mesa, Tempe, Phoenix, Queen Creek, or San Tan, a dealership may help submit your application to third-party lenders. That’s different from in-house financing, and it doesn’t guarantee approval or specific loan terms. With some preparation, you can take the next step with a clearer sense of what to ask and compare.
Key Takeaways
- A used car auto loan Arizona shoppers apply for is repaid over time under terms set by a lender, not necessarily by the dealership selling the vehicle.
- Before applying, set a comfortable vehicle budget and be ready to share details about your income, credit history, existing obligations, and chosen vehicle.
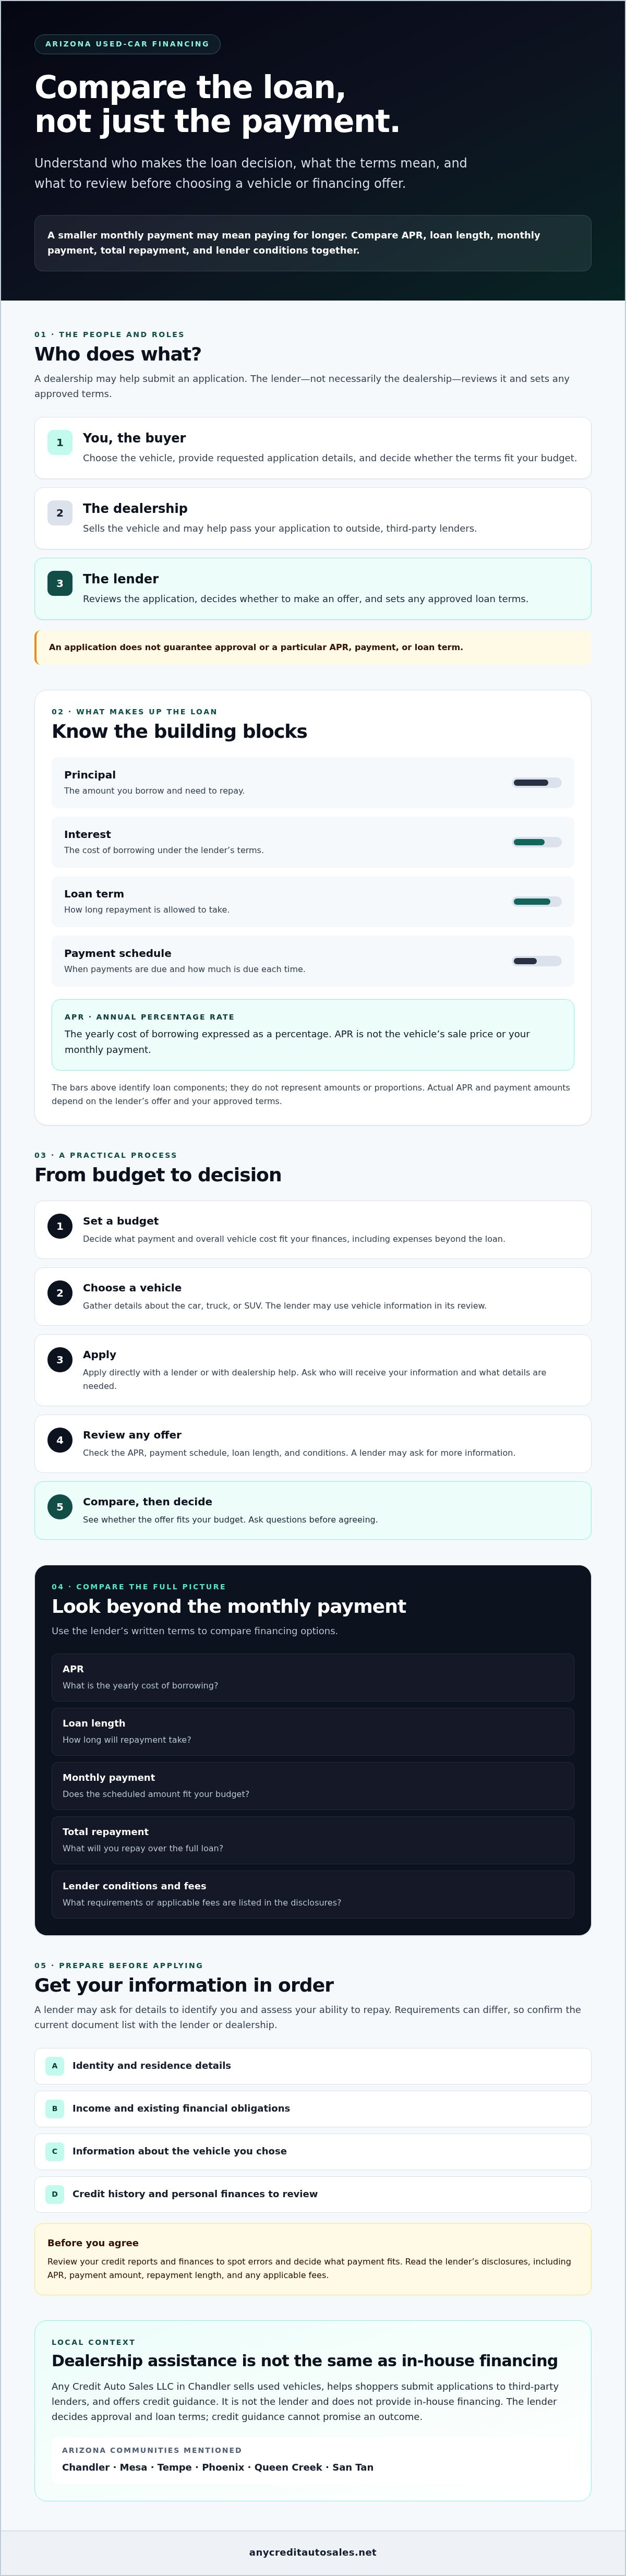
- Compare APR, loan length, monthly payment, total repayment, and lender conditions. A smaller monthly payment may mean paying for longer.
- Review your credit reports and personal finances so you can spot errors and decide what payment fits your budget.
- Any Credit Auto Sales in Chandler sells used vehicles, helps shoppers submit applications to third-party lenders, and offers credit guidance, but the lender decides loan terms and approval.
What Is a Used-Car Loan in Arizona, and Who Is Involved?
A used-car loan lets you pay for a vehicle over time instead of paying the full amount upfront. You borrow money from a lender and repay it under terms the lender approves. The buyer chooses the vehicle and agrees to repay the loan. The seller completes the vehicle sale, while the lending institution reviews the application, decides whether to make an offer, and sets any approved terms.
That distinction matters if you’re looking into a used car auto loan Arizona shoppers can apply for through a dealership. A dealer may help you submit an application, but that doesn’t mean the dealer is lending you the money. For a plain-language overview of direct and dealer-assisted car financing options, see the general explanation of vehicle finance.
How do the dealership and lender work together?
The dealership sells the vehicle and may help pass your application to outside lenders. The lender reviews the information and decides whether to offer financing, then provides proposed terms for you to consider. The process and outcome can vary by lender and applicant, and an application might not result in an offer.
For example, Any Credit Auto Sales LLC in Chandler helps shoppers submit applications to third-party lenders and offers credit guidance. It isn’t the lender and doesn’t provide in-house financing. Credit guidance can help you understand your application, but it can’t promise approval, a particular APR, or specific loan terms.
What does a used-car loan payment include?
Your payment is based on several parts of the loan:
- Principal: The amount you borrow and need to repay.
- Interest: The cost of borrowing, set under the lender’s terms.
- Loan term: The length of time allowed for repayment. A longer term spreads repayment over more time.
- Payment schedule: When payments are due, such as monthly, and how much is due each time.
APR, or annual percentage rate, is the yearly cost of borrowing expressed as a percentage. It helps you understand the cost of credit, but it isn’t the vehicle’s sale price or your monthly payment. The sale price is what the seller charges for the vehicle; the monthly payment is the amount due on the lender’s schedule. APR and payment amounts depend on the lender’s offer and your approved terms.
Before agreeing, read the lender’s disclosures. Check the APR, payment amount, repayment length, and any applicable fees listed there. Use those written terms to understand what you’re agreeing to and compare the offer with other options.
How Does a Used-Car Auto Loan Application Work in Arizona?
A clear order can make the application easier to manage. For a used car auto loan Arizona shoppers may pursue through a dealership, the dealer can help submit an application, while a third-party lender reviews it and decides whether to make an offer. Here’s a practical way to move through the steps without assuming every lender follows the same process:
- Set a budget. Decide what payment and overall vehicle cost fit your finances, including expenses beyond the loan.
- Choose a vehicle. Gather details about the car, truck, or SUV you’re considering. The lender may use vehicle information as part of its review.
- Apply. Complete the lender’s application directly or with help from a dealership. Ask who will receive your information and what details are needed.
- Review any terms. If a lender makes an offer, read the APR, payment schedule, loan length, and conditions carefully.
- Decide whether to proceed. Compare the offer with your budget and ask questions before agreeing.
What information may a lender ask you to provide?
An application may ask for details that help identify you and assess your ability to repay, such as your identity, residence, income, existing financial obligations, and information about the vehicle. Requirements can differ. Before gathering paperwork, confirm the current document list with the lender or dealership. Providing information allows the lender to review your application, but it doesn’t guarantee approval or a particular offer.
What happens after you submit an application?
The lender reviews what you submit and may ask for more information. If you receive terms, compare them with your budget and other options before deciding. Ask the lender or dealership about next steps, expected timing, and any application-related questions. For more preparation tips, the Consumer Financial Protection Bureau explains how to prepare to shop for an auto loan.
Keep the vehicle paperwork in view, too. Arizona title and transaction steps may depend on your situation, so check current guidance through the Arizona Department of Transportation Motor Vehicle Division or another official state source. If you’re shopping in Chandler or nearby communities, you can explore used vehicles and application assistance. Any Credit Auto Sales LLC helps shoppers submit applications to third-party lenders; the lender makes the decision and sets any approved terms.
How Should You Compare Used-Car Loan Terms and Options?
A payment that fits your budget is only one part of a loan offer. Compare the full written terms side by side, not an advertised example or an offer you assume you’ll qualify for. When weighing a used car auto loan Arizona lenders may offer, use the same vehicle price and down payment assumptions for each comparison so the differences are easier to spot.
How do APR, loan term, and monthly payment relate?
APR and repayment length both affect what you pay over time. A longer term can lower the scheduled monthly payment, but it also means making payments for longer. A shorter term may mean a higher payment, even though repayment ends sooner.
Hypothetical example: Imagine two offers for the same amount borrowed. Offer A has a shorter term and a higher monthly payment. Offer B stretches repayment over more time, so its monthly payment may be lower. These are illustrative comparisons, not typical Arizona loan terms. A calculator can help estimate payments, but check the lender’s written disclosures for exact figures and conditions.
How can you compare a lender, bank, or dealership-assisted application?
Compare actual written offers, including their APR, term, payment, total repayment, application steps, communication, and any conditions. A dealership may help submit an application to a third-party lender, but the lender sets any approved terms. A bank or other lender may have a different application process. No route is automatically the cheapest or best for every buyer. The Consumer Financial Protection Bureau also outlines steps for getting an auto loan.
Use this table to organize the details. Fill it with information from each lender’s written offer, and ask about anything that isn’t clear.
| What to compare | What to record | Why it matters |
|---|---|---|
| APR | The stated annual percentage rate | Helps show the yearly cost of borrowing. |
| Loan term | How long repayment lasts | A longer term can reduce the payment while extending repayment. |
| Monthly payment | Payment amount and due schedule | Check whether it fits your budget. |
| Total repayment | Total amount due over the loan | Shows the broader cost beyond the monthly payment. |
| Lender conditions | Requirements, fees, or other listed terms | Can affect the offer and your decision to proceed. |
Compare the full loan terms, not payment alone.
How Can Arizona Shoppers Prepare Before Applying for a Used-Car Loan?
Preparation can help you shop with a clearer budget and better questions. Before applying for a used car auto loan Arizona lenders may review, look at your monthly cash flow and decide what vehicle costs feel manageable, even if a lender might approve a different amount.
Budget beyond the loan payment. Ownership expenses can include insurance, fuel, maintenance, and registration-related costs. Arizona title and registration details can depend on the transaction, so shoppers in Chandler, Mesa, Tempe, Phoenix, Queen Creek, and San Tan should confirm current steps with the Arizona Motor Vehicle Division (MVD) or another appropriate official state source.
What should you review before choosing a vehicle?
Start with your own budget, not the maximum amount a lender may offer. Review your income, regular bills, savings, and other obligations to find a payment that leaves room for everyday expenses. Check your credit reports for mistakes, too. If you find an error, follow the reporting agency’s process to ask about correcting it before applying.
Keep the vehicle decision separate from the financing decision. Review a vehicle’s condition and history, then compare suitable cars, trucks, and SUVs against your needs, such as passenger space or the kind of driving you do. Check current inventory directly with the seller, since availability can change.
What should you ask before accepting loan terms?
Ask for the lender’s offer in writing. Make sure you understand the APR, repayment length, payment amount, total repayment, and any conditions. Ask which terms are final and which depend on lender approval or additional information. If something is unclear, request an explanation before agreeing.
It also helps to prepare questions about the vehicle’s history, the purchase paperwork, and what happens next. Confirm transaction details with the dealership, and verify title or registration questions through Arizona MVD guidance. That way, you’re checking both sides of the purchase: the loan and the vehicle transaction.
If you’re considering a vehicle from Any Credit Auto Sales in Chandler, review used vehicles and ask about application assistance. The dealership helps shoppers submit applications to third-party lenders and offers credit guidance. The lender decides whether to approve an application and sets any offered terms.
Where Can You Get Help With a Used-Car Auto Loan in Arizona?
Help can come from a lender, a bank or credit union, or a dealership that assists with applications. Keep the roles clear: the lender reviews your individual application and decides whether to offer a loan. If it makes an offer, the lender sets the APR, payment schedule, and other terms. A dealership can help you understand the application process, but it can’t promise approval or a particular offer.
How can a dealership help if your credit history is varied?
If your credit history has a few bumps, clear guidance can help you understand what information an application may involve and what questions to ask. Any Credit Auto Sales LLC, an independent used-car dealership in Chandler, offers credit guidance and helps shoppers submit applications to third-party lenders. The lender reviews each application and decides what options, if any, may be available based on the applicant’s circumstances.
That distinction matters. The dealership doesn’t provide in-house or buy-here-pay-here financing, and credit guidance isn’t a promise of approval, a specific rate, or improved credit. Ask which lender will review the application, what terms are being considered, and whether the lender needs more information. Get clear answers before deciding what to do next.
What is a low-pressure next step for Chandler-area shoppers?
If you’re exploring a used car auto loan Arizona shoppers can apply for through a dealership, take it one question at a time. First, decide what kind of vehicle fits your needs. Then ask about the current selection and how application assistance works. If you live in Chandler, Mesa, Tempe, Phoenix, Queen Creek, or San Tan, ask which steps the dealership handles and which questions should go directly to the lender.
Before moving forward, make sure you understand whether an application is being sent to an outside lender and what information may be requested. If a lender provides terms, review them carefully and compare them with your budget. Submitting an application doesn’t require you to accept an offer.
Ready to explore your options? Review Any Credit Auto Sales’ available used vehicles and ask the dealership about its application process.
Take Your Next Step With a Clearer Plan
Preparation can make your next move more manageable. Set a vehicle budget that fits your finances, review your credit information, and compare written loan offers by APR, repayment length, monthly payment, and total repayment. Looking for a used car auto loan Arizona shoppers can apply for through a dealership? Remember that the lender reviews your application and sets any approved terms.
Any Credit Auto Sales in Chandler sells used vehicles, helps shoppers apply through third-party lenders, and offers credit guidance to people with varied credit histories. The dealership doesn’t provide in-house financing, and guidance isn’t a promise of approval or specific loan terms. Ask questions, take time to review the details, and choose only what feels right for your situation.
Ready to explore your options? Explore available vehicles and ask us about the financing application process. You can take this one step at a time, with more confidence in the questions you ask and the choice you make.
Frequently Asked Questions
Can I get a used-car auto loan in Arizona through a dealership?
Yes, a dealership may help you submit an application to outside lenders, but the lender reviews it and decides whether to offer a loan. Any Credit Auto Sales LLC is based in Chandler and assists shoppers with applications and credit guidance. It doesn’t offer in-house or buy-here-pay-here financing. If you’re shopping in Mesa, Tempe, Phoenix, Queen Creek, or San Tan, ask which lender reviews your application and who can answer questions about the terms.
What credit score do I need for a used-car loan in Arizona?
There isn’t one credit score that guarantees approval for every used-car loan. Lenders set their own review standards and may consider your credit history along with income, existing obligations, and vehicle details. Before applying, check your credit reports for errors and ask the lender what factors it considers. Any Credit Auto Sales offers credit guidance to shoppers with varied credit histories, but only a lender can decide whether to approve an application or offer terms.
How much should I budget for a used-car loan payment?
Choose a payment that fits your monthly budget, rather than relying only on the amount a lender may offer. Consider the APR, repayment length, and total repayment, since a lower monthly payment may mean paying for longer. Leave room for vehicle expenses beyond the loan, such as insurance, fuel, and registration-related costs. Compare written offers for the same vehicle and amount borrowed, then check the lender’s disclosures for exact payment details.
What documents may I need to apply for a used-car auto loan?
A lender may ask for information to confirm your identity and residence, verify income, and understand your financial obligations. It may also request details about the vehicle you want to buy. The exact documents can vary by lender and application, so contact the lender or dealership for its current requirements before gathering paperwork. Submitting documents helps the lender review your application, but it doesn’t guarantee approval or a particular rate or loan term.
Does a dealership decide whether my auto loan is approved?
No. If a dealership helps send your application to a third-party lender, that lender reviews the information and makes the approval decision. The lender also sets any offered APR, payment schedule, and other terms. A dealership can explain its application process and provide credit guidance, but it can’t guarantee approval or a specific offer. Read the lender’s written terms carefully, and ask the lender directly about any conditions or information you don’t understand.
What happens if I am not approved for a used-car loan?
If a lender doesn’t approve your application, ask whether it can explain the decision and whether any information is missing or needs correcting. You can review your credit reports for errors, reconsider your vehicle budget, or ask about other application options. Any Credit Auto Sales can offer credit guidance and help shoppers submit applications to third-party lenders, but the lender decides whether to make an offer. Take time to understand your choices before applying again.


