
The lowest monthly payment can be the most expensive choice over time. A longer loan may reduce what you pay each month, but it can increase the total you repay. If you’re comparing used car finance options, it helps to understand how applying through a dealership differs from applying directly to a lender, and how your credit history may affect the offers you receive.
Compare the full cost of borrowing, not just the payment. This guide explains how APR, loan term, monthly payment, and total repayment fit together. It also covers what to prepare before applying and how to make a fair comparison between offers.
At Any Credit Auto Sales LLC, shoppers can explore pre-owned vehicles online and apply for financing through third-party lenders, with credit guidance along the way. The dealership helps guide the application process; lenders make financing decisions. Whether you’re in Chandler, Mesa, Tempe, Phoenix, Queen Creek, or San Tan, understanding the options can help you choose a vehicle and loan that suit your budget.
Key Takeaways
- Compare applying directly to a lender, applying through a dealership, and paying cash to see which approach suits your needs.
- With dealership-arranged used car finance, the dealership helps submit your application to third-party financial institutions for review.
- Compare APR, loan term, monthly payment, total repayment, and lender conditions together.
- Make comparisons fair by using the same vehicle price, down payment, and amount borrowed wherever possible.
- Explore pre-owned vehicles online and prepare key application details before taking your next step in Chandler or the East Valley.
Used Car Finance: What Are Your Main Ways to Pay for a Vehicle?
You can pay for a pre-owned vehicle with cash or borrow money and repay it over time. If you plan to borrow, you can apply directly to a lender or submit an application through a dealership that works with outside lenders. These routes differ in where you start, but any financing offer depends on a lender’s review.
What does financing a used car mean?
With a vehicle loan, you borrow an amount called the principal to help pay for the car. The lender charges interest, shown as an annual percentage rate (APR). Your loan term is the time set for repayment, and your monthly payment is the amount due each month under the agreement. The amount borrowed, APR, and term all affect your payment and the total you repay.
The vehicle purchase and financing agreement are related but separate. One records the sale of the car; the other sets out the borrowing and repayment terms. The lender reviews your application and determines whether to approve it and what APR and terms to offer. Those details depend on the lender’s review.
Which financing routes can used-car shoppers compare?
Direct lender application: You apply to a bank, credit union, or another lender yourself. The lender reviews your application and provides any offer directly to you. This can help you understand a financing offer before settling on a vehicle. Review the lender’s requirements and the terms of any offer.
Dealership-arranged third-party financing: You apply through the dealership, which connects your application with outside financial institutions. The dealership helps with the application process, but the lender reviews it and sets any final offer. Any Credit Auto Sales LLC helps shoppers apply through third-party lenders; it is not the lender. Car finance offers a neutral overview of direct and indirect borrowing routes.
Paying cash: You use available funds instead of taking out a vehicle loan. That avoids borrowing and monthly loan payments, but uses money you may need for other priorities. Consider how the purchase fits your budget and available funds.
No route is right for every shopper. Compare the costs, application process, and impact on your budget, and remember that any financing offer depends on lender review.
How Does Dealership-Arranged Used Car Finance Work?
With dealership-arranged financing, you can apply for a vehicle loan while shopping for a car. The application goes to outside financial institutions for review. The dealership can guide you through the application, but it doesn’t make the lending decision or set the final loan terms. The process typically follows these steps.
- Choose a vehicle. Explore the pre-owned inventory and identify a car that fits your needs and budget. The vehicle and requested loan information may be part of the lender’s review.
- Submit an application. Provide the information requested so participating third-party lenders can review your application. Any Credit Auto Sales assists shoppers with applications to outside financial institutions.
- Wait for lender review. A lender evaluates the application and decides whether to make an offer. If it does, the lender sets the terms. Applying doesn’t guarantee approval or a particular rate, payment, or loan term.
What happens after you submit a financing application?
Lenders review the information in your application alongside details about the vehicle and requested financing. The review and available offers can vary. If you receive an offer, read the documents before accepting. Check the APR, repayment term, monthly payment, total amount to be repaid, and any conditions. The Federal Trade Commission’s Financing or Leasing a Car guide also explains what to consider when reviewing financing.
Submitting an application doesn’t mean you have to accept an offer. Take time to understand the written terms and consider whether the payment fits your budget before making a decision.
What does the dealership do, and what does the lender decide?
Any Credit Auto Sales helps shoppers navigate an application to third-party financial institutions. The dealership supports the application process; it doesn’t act as the lender, provide buy-here-pay-here financing, or decide the outcome.
The outside lender reviews the application and determines whether to offer financing, along with the APR, term, and other loan conditions. Since terms can differ between offers, review the full agreement rather than relying on a payment estimate alone. Knowing which party handles each step makes it easier to understand whose terms you’re reviewing.
If you’re ready to consider a vehicle, you can explore pre-owned vehicles and take a first step toward an application.
Used Car Finance Options Compared: What Should You Weigh?
The right route depends on whether you want to borrow, how you prefer to apply, and what fits your budget. Compare the practical differences without assuming one option is always cheaper or better. The Consumer Financial Protection Bureau also outlines the different ways to buy or finance a car.
| Option | Convenience | Who reviews financing? | Flexibility and what to understand |
|---|---|---|---|
| Direct lender application | You start with a bank, credit union, or other lender. | The lender reviews your application. | You handle the lender conversation directly. Review the offer’s APR, term, payment, total repayment, and conditions. |
| Dealership-arranged third-party financing | You apply through a dealership while shopping for a vehicle. | Outside financial institutions review the application and decide whether to make an offer. | The dealership can help with the application, but the lender sets any final terms. Offers depend on lender review. |
| Paying cash | You pay for the vehicle without applying for a loan. | No lender reviews a financing application. | You avoid a loan payment, but use funds that may be needed for other priorities. Consider how the purchase fits your overall budget. |
How does direct lender financing compare with dealership-arranged financing?
With a direct application, you start with a lender and work with it on financing. With dealership-arranged financing, you start at the dealership, which helps connect your application with outside lenders. The starting point differs, but both routes involve lender review. Neither guarantees approval, a specific rate, or particular offers. Compare the written terms you receive rather than assuming one route will produce a better outcome.
When might paying cash make sense instead?
Paying cash avoids a loan obligation and monthly loan payments. It also uses money that could otherwise go toward savings, bills, or other plans. Consider how the purchase affects your available funds and financial priorities. Choose the approach that feels manageable for your circumstances.
Compare the full repayment obligation, not the monthly payment alone. For used car finance, look at the APR, loan length, total amount repaid, and any conditions together. A payment that looks comfortable on its own may not show the full cost of borrowing.
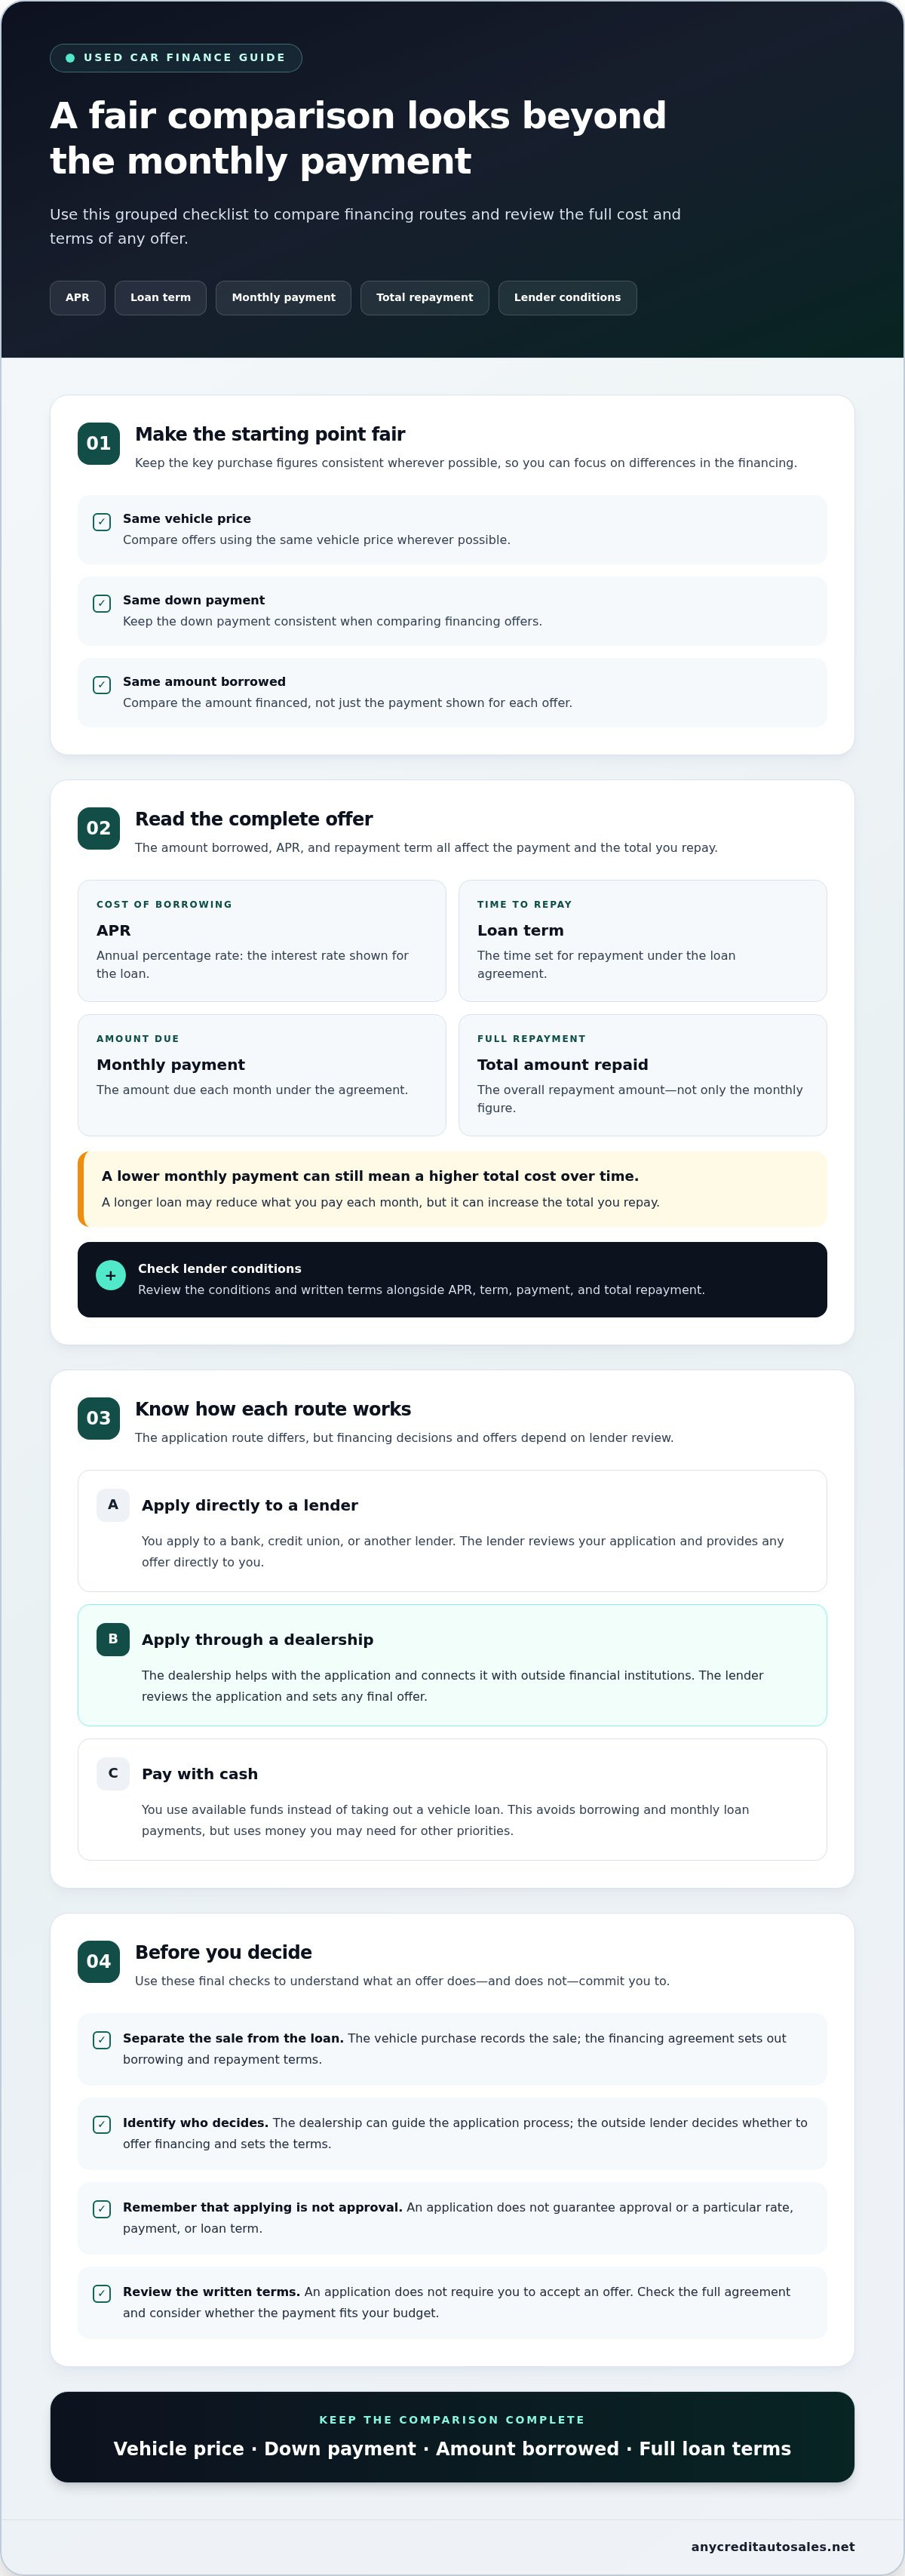
How to Compare Used Car Finance Offers in Chandler and the East Valley
A fair comparison starts with the same vehicle and similar borrowing assumptions. If one offer uses a different amount financed or a longer term, its monthly payment may look lower without costing less overall. Use this checklist to compare the details side by side.
- Compare the APR. APR is the yearly cost of borrowing expressed as a rate. It helps you compare offers, but it isn’t the whole picture.
- Check the loan term. Note how long you’ll make payments. A longer term can lower the monthly amount while extending repayment.
- Review the monthly payment. Check that it fits your budget, but don’t judge an offer by this number alone.
- Look at total repayment. Compare the full amount you would repay over the life of each loan.
- Read lender conditions. Note any stated fees and other conditions. If a term is unclear, ask the lender to explain it before you accept.
Which loan details should you compare side by side?
Where possible, line up offers for the same vehicle, amount financed, and similar loan terms. Then compare APR, repayment length, monthly payment, total repayment, and any stated fees. If an offer uses a different down payment or amount borrowed, account for that before drawing conclusions. This helps show whether a lower payment reflects different loan terms or simply more time to repay.
For shoppers in Chandler and the East Valley, this approach can make offers easier to understand, whether you’re in Mesa, Tempe, Phoenix, Queen Creek, or San Tan. A clear side-by-side comparison keeps the focus on the complete loan obligation, not just one appealing figure.
What can you prepare before applying?
Gather accurate information requested by the application. This may include details about your identity, income, residence, and the vehicle you’re considering. Set a monthly budget that also accounts for ownership costs beyond the loan payment, such as fuel and insurance. Preparing these details can make it easier to complete an application, but doesn’t guarantee approval or a particular offer.
Ready to compare a vehicle with your budget in mind? Explore pre-owned vehicles and take a clear next step from Chandler or the surrounding area.
Explore Used Car Finance with Any Credit Auto Sales
Choosing a vehicle and deciding how to pay for it can feel like a lot to handle at once. Any Credit Auto Sales is a used-car dealership in Chandler, Arizona, serving shoppers in nearby East Valley communities. The team helps shoppers navigate financing applications and offers credit guidance, so you can take the process one step at a time.
Any Credit Auto Sales connects financing applications with third-party financial institutions. Those lenders review applications and decide whether to offer financing and what terms apply. The dealership guides the application process but isn’t the lender and doesn’t provide in-house financing. Approval, rates, and loan terms depend on the lender’s review.
How can local shoppers take the next step?
Start by browsing pre-owned vehicles online and narrowing your choices to cars that suit your needs and budget. When you’re ready, begin a financing application online. Outside lenders review the application, while the dealership helps guide you through the process. Shoppers in Chandler, Mesa, Tempe, Phoenix, Queen Creek, and San Tan can explore this path at their own pace.
What should you expect from credit help?
Credit guidance can help you understand the application process and think through financing choices in practical terms. You can focus on the information lenders may consider and the details of any offer you receive. Each lender makes its own decision, so guidance isn’t a promise of approval, a particular rate, or a change to your credit score.
Ready to take the next step? Browse pre-owned vehicles and start an application to explore used car finance with support from a local dealership and an application connected to outside lenders.
Take Your Next Step with Confidence
The best choice is the one that fits your budget and priorities. You can apply directly to a lender, use a dealership-arranged application that connects with outside lenders, or pay cash. If you finance, compare APR, loan term, monthly payment, and total repayment together. A lower payment alone doesn’t show what the full loan will cost.
Any Credit Auto Sales helps shoppers with varied credit histories explore financing applications through third-party financial institutions. The lenders review applications and set any offered terms. You can browse pre-owned vehicles online and begin the process at your own pace.
Ready to explore your options? Browse pre-owned vehicles and start your financing application. Compare the full terms and choose what fits your budget. Any Credit Auto Sales can guide you through the application process.
Frequently Asked Questions
Is dealership-arranged used car finance the same as buy-here-pay-here financing?
No. With dealership-arranged financing, the dealership helps send your application to outside financial institutions. A lender reviews it and decides whether to offer a loan and what terms apply. Buy-here-pay-here financing is a different arrangement. Any Credit Auto Sales LLC works with third-party lenders and does not provide in-house financing. An application doesn’t guarantee approval or a specific rate, payment, or term.
Can I get used car finance with challenged credit?
It may be possible, but only a lender can decide after reviewing your application. Your credit history is one part of that review, and decisions or offers can vary. Any Credit Auto Sales LLC offers credit help and guidance for shoppers with varied credit histories. The team can help you understand your options, but no dealership can promise approval, a particular rate, or a specific loan term.
How much should I put down when financing a used car?
There isn’t one down payment amount that suits everyone. Consider what you can comfortably pay upfront while keeping enough for other needs and expenses. A down payment reduces the amount you need to borrow, but final loan terms depend on lender review. Before applying, set a comfortable budget and compare offers using the same vehicle price, down payment, and amount financed wherever possible.
What is the difference between APR and the monthly payment?
APR is the yearly cost of borrowing expressed as a rate. Your monthly payment is the amount due each month under a loan agreement. The payment is affected by factors such as the amount borrowed, APR, and repayment term. A lower monthly payment doesn’t always mean lower overall borrowing, especially if the repayment period is longer. Compare APR, term, payment, and total repayment together.
Does applying for used car finance affect my credit?
It can, depending on how the lender checks your credit. Some applications involve a credit inquiry that may affect your score, while other checks may not. Before submitting an application, read the lender’s disclosures so you understand whether a credit check is involved and how your information will be used. An application doesn’t guarantee approval, and its effect can vary by credit file and scoring approach.
Can I apply for used car finance online in Chandler, Arizona?
Yes. Shoppers can browse Any Credit Auto Sales LLC’s pre-owned inventory online and submit an application to begin the financing process with third-party financial institutions. The dealership guides the application, while lenders review it and determine any offer. This online starting point is available to shoppers in Chandler, Mesa, Tempe, Phoenix, Queen Creek, and San Tan. Approval and loan terms depend on lender review.


