
Can you buy a car with bad credit? It may be possible, but a low score doesn’t guarantee approval or mean you have to accept a payment that strains your budget. If you’re wondering how to buy a car with bad credit, start by working out what you can afford, not by assuming financing is guaranteed.
It’s understandable to worry about rejection or feel unsure what lenders will review. Your credit history matters, but lenders may also consider income, existing debts, the vehicle, and the loan terms you request. Knowing what information may shape a decision can help you prepare before you apply.
This guide covers the steps to take before you shop: setting a realistic budget, preparing application details, comparing loan offers, and choosing a vehicle that fits your needs. You’ll learn how to weigh the monthly payment against the total loan cost and how a down payment may affect the amount you borrow. For shoppers in Chandler and nearby East Valley communities, Any Credit Auto Sales LLC offers pre-owned vehicles, an application connecting shoppers with third-party lenders, and credit guidance. Use these steps to explore your options with more confidence.
Key Takeaways
- Bad credit is a lender’s assessment, not a judgment of your worth or a guarantee of rejection.
- Learn how to buy a car with bad credit by preparing your financial information and setting a realistic budget before exploring vehicles.
- An auto financing application can connect you with third-party lenders. Each lender reviews the application and makes its own decision.
- Compare the vehicle and loan separately, then weigh the payment, loan length, and full repayment terms together.
- Explore practical next steps for finding a pre-owned vehicle and financing options in Chandler and nearby East Valley communities.
Can You Buy a Car with Bad Credit? What It Really Means
Uncertainty about financing can make an important car purchase feel stressful. A lower credit score may raise questions about whether you’ll qualify, what a lender will consider, and where to begin. “Bad credit” is a lender’s assessment of past borrowing and repayment information. It isn’t a verdict on your worth or your future.
You may also hear the term What is subprime lending? It generally refers to lending for borrowers a lender considers higher risk. The label describes how a lender views a financial application, not who you are as a person. Lenders use different standards, so the same credit history may be viewed differently by different institutions.
Does bad credit automatically prevent you from buying a car?
No. A lower score doesn’t automatically mean every application will be declined. Credit history is one part of the picture. A lender may also review income, existing debts, the vehicle you want, and the loan terms you request. Together, these details can provide a broader view of your finances, but they don’t ensure a particular decision.
There’s no single outcome to count on. Lenders have their own criteria, and approval is never guaranteed. Learning how to buy a car with bad credit starts with understanding what may affect a decision, rather than assuming either automatic rejection or certain approval.
What can affect a car-financing decision?
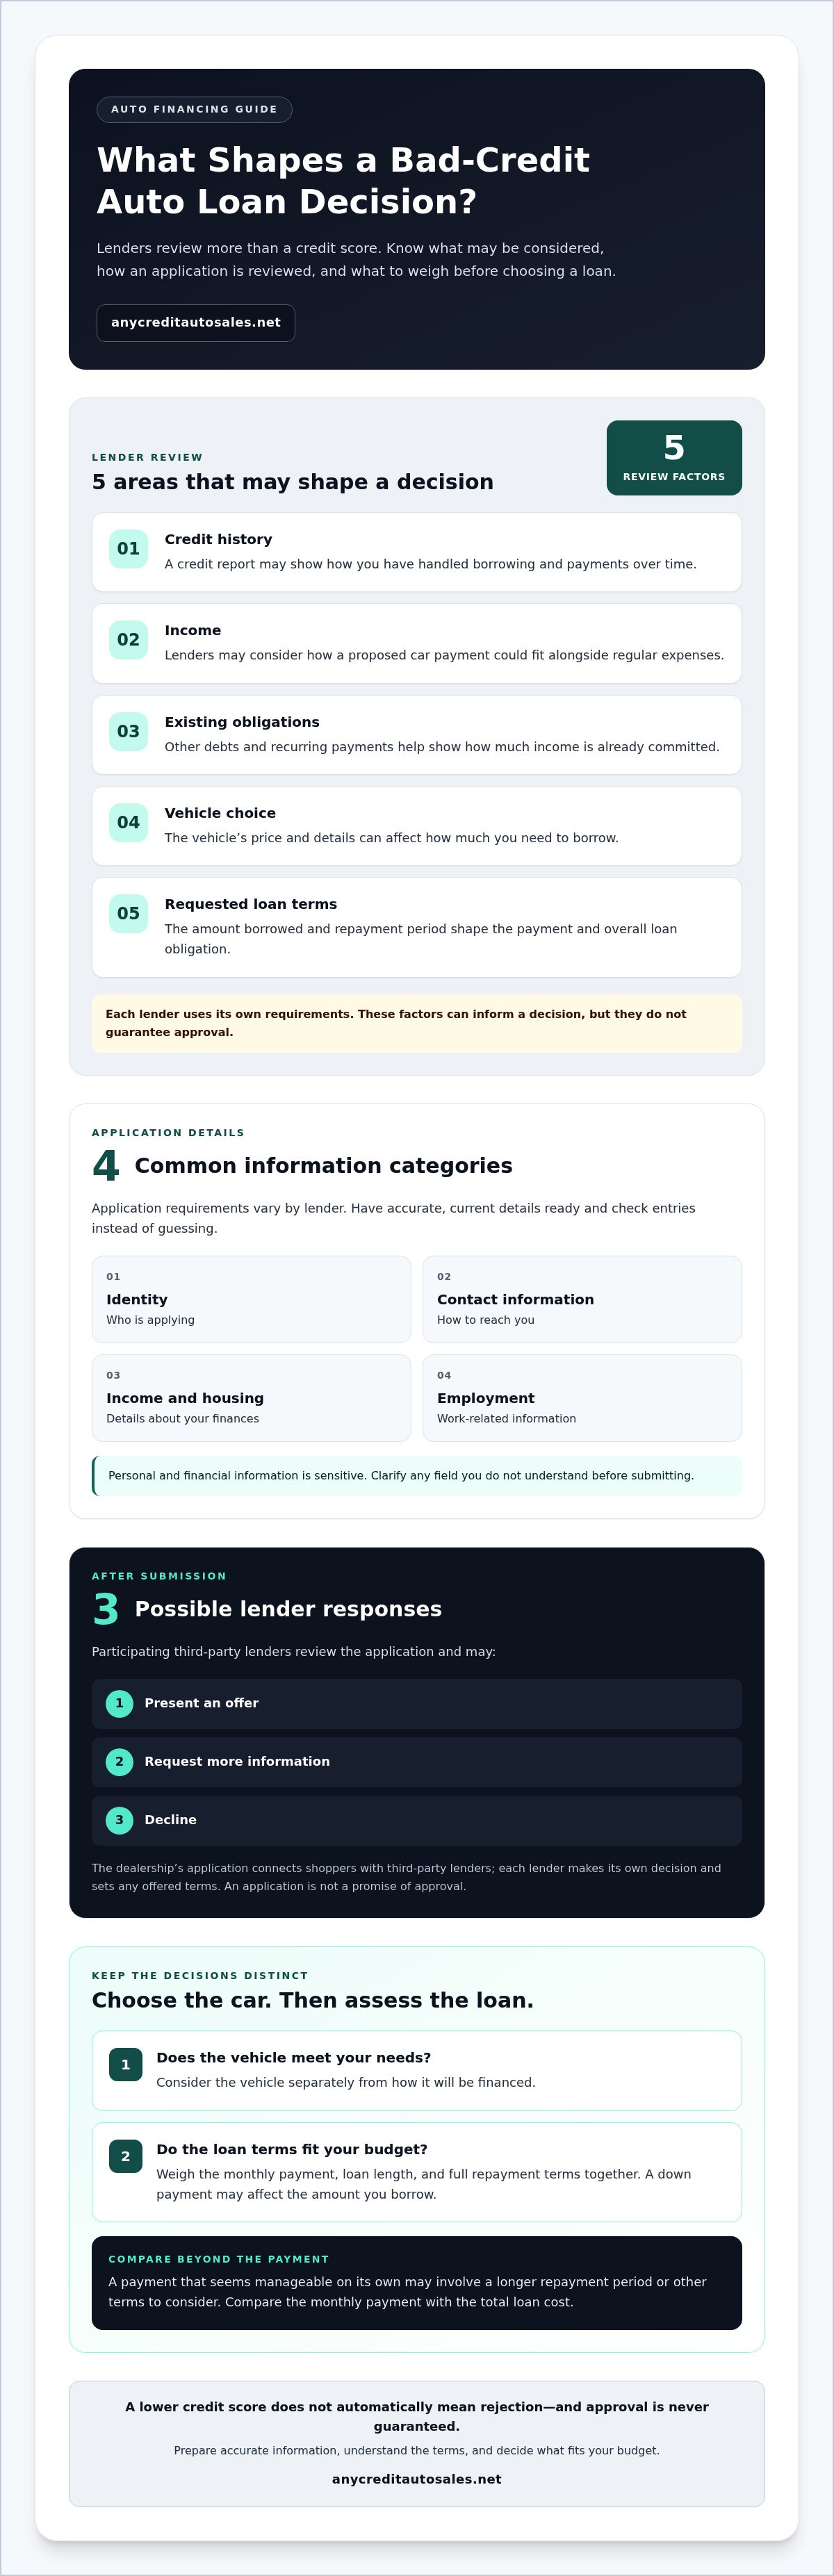
Each application is assessed in its own context. A lender may consider factors such as:
- Credit history: Your credit report may show how you’ve handled borrowing and payments over time.
- Income: Lenders may review your income to understand how a car payment could fit alongside regular expenses.
- Existing obligations: Other debts and recurring payments help show how much of your income is already committed.
- Vehicle choice: The vehicle’s price and details can affect the amount you need to borrow.
- Requested loan terms: The amount borrowed and repayment period shape the payment and overall loan obligation.
These factors don’t follow one universal formula. A lender weighs the information according to its own requirements. Providing accurate details helps present a clear application, but it can’t promise a particular result.
Lender review factors can inform a decision, but they can’t guarantee approval. Keep that distinction in mind as you prepare. Focus on what you can control: understanding your budget and getting accurate information ready.
How Bad-Credit Auto Financing Works from Application to Decision
When you explore financing, it helps to know who reviews your application. At Any Credit Auto Sales LLC, shoppers can complete an auto financing application that connects them with third-party lending partners. The dealership doesn’t make the lending decision. Each lender reviews the information and decides whether to offer financing and what terms to set.
This differs from buy-here-pay-here or in-house financing. Instead of the dealership providing the loan itself, the application connects shoppers with outside financial institutions. An application is a request for consideration, not a promise of approval or a particular rate, payment, or loan length.
What information might an auto-loan application request?
Application details vary by lender, but common categories include identity and contact information, income, housing, and employment. A lender may request these details to understand who is applying and how a proposed payment could fit into their finances. Have accurate, current information ready, and enter it carefully. Check details rather than guessing when you can.
Personal and financial information is sensitive. Use the dealership’s application process and take care when sharing details. If you’re unsure what a field means, pause and clarify the question before submitting. The information requested can depend on the lender and application.
What happens after you submit an application?
After submission, participating third-party lenders review the application. They may assess the details you provide and respond with an offer, request more information, or decline. The next step depends on each lender’s review, so don’t treat an application as guaranteed approval.
Before submitting, understand whether the process includes a credit inquiry and whether it may affect your credit file. A lender may use different types of inquiries, and their effects can differ. Knowing what to expect helps you make an informed choice before sharing your information.
If a lender presents terms, read them before choosing a vehicle. Review the payment, loan length, and other stated conditions together. The financing decision and vehicle decision are related, but they’re not the same step. A payment that seems manageable on its own may come with a longer repayment period or other terms to consider.
Knowing how to buy a car with bad credit includes understanding who reviews your application and what happens next. To begin exploring the process, you can review the auto financing application from Any Credit Auto Sales LLC.
How to Compare a Car, Monthly Payment, and Loan Terms
A vehicle that seems affordable at first glance can come with financing terms that don’t fit your plans. Make two decisions separately: choose a car that meets your needs, then decide whether the loan terms work for your budget. Don’t let a low monthly payment alone steer you toward a vehicle or loan you haven’t fully reviewed.
How can you set a car budget before shopping?
Start with your take-home income, then subtract recurring household expenses such as housing, utilities, food, and existing debt payments. The amount left isn’t automatically your car budget. Set aside room for savings and unexpected expenses before deciding what payment you can manage.
Estimate the costs of owning the vehicle, not just the loan payment. Consider insurance, fuel or charging, and routine ownership needs. Leave a buffer for changes in expenses, too. A budget that works only under best-case assumptions can become uncomfortable when everyday costs shift.
Which loan terms should you compare side by side?
Put each written offer beside the same details so you can compare them fairly. Review:
- Payment amount: What you’re expected to pay and how often.
- Repayment length: How long you’ll make payments.
- Total repayment: The full amount due over the life of the loan.
- Other stated terms: Any disclosed fees, down payment, or conditions that affect the offer.
A longer repayment period can lower the monthly payment by spreading payments over more time. But it can also mean making payments for longer and repaying more overall. Compare the complete written terms, not just the figure that seems easiest to fit into this month’s budget.
The monthly payment alone can’t tell you the full cost of borrowing. Check how it connects to the repayment period and total amount due. If a term or fee is unclear, get an explanation before deciding. Compare like with like: don’t set one offer’s monthly payment against another offer’s total repayment.
Then consider the vehicle itself. Does its size, features, and expected use suit your daily needs? Does the amount you’d borrow fit your budget? Learning how to buy a car with bad credit means weighing the car and financing together without confusing one decision for the other. Choose only when both the vehicle and written terms feel workable.
How to Prepare Before Applying for a Car Loan with Bad Credit
Preparation can make an application feel more manageable. It won’t guarantee approval or specific loan terms, but it can help you share accurate information and make choices that fit your circumstances. Take the steps in order: review your finances, gather the details you may need, set a budget, then explore vehicles.
What should you review before starting an application?
Start with a clear snapshot of your finances and transportation needs. Look over your income, recurring household expenses, and current debts. Think about what you need from a vehicle, such as room for passengers or a dependable way to get to work. This gives you a practical starting point before you focus on specific cars.
Check your credit reports through appropriate consumer channels and review them for information that looks inaccurate. If you spot an error, follow the reporting agency’s process to dispute it. Corrections can take time, so don’t assume a report will change immediately. Gather current identity, income, housing, and employment details, too. If an application question is unclear or you’re unsure of a detail, resolve that before submitting rather than guessing.
Consider whether a down payment or a co-applicant makes sense for your situation. Neither is the right choice for everyone. A co-applicant should understand the responsibility involved, and you should avoid committing money needed for essential expenses. Choose what feels financially sound for you, not what you feel pressured to offer.
How can you shop without taking on more than you can manage?
Set a comfortable budget before browsing inventory. Include the vehicle payment along with your estimates for insurance, fuel or charging, and routine ownership needs. Leave room for unexpected expenses. Then explore vehicles that match your transportation needs and budget, rather than stretching your budget to fit a particular car.
When you review financing, compare the written terms with your budget. Look beyond the payment and consider the repayment period, total repayment, and any disclosed fees together. A payment that looks manageable may still come with a longer commitment than you want. Pause if the numbers depend on cutting essentials or assuming nothing unexpected will happen.
Preparation helps you make informed choices, but the lender makes its own decision. As you work through how to buy a car with bad credit, keep your needs and budget at the center. Explore pre-owned vehicles and financing help as you consider your next step.
Your Next Step: Explore Bad-Credit Car Buying in Chandler, Arizona
A practical car purchase starts with three steady steps: set a budget that works for your household, provide accurate information on an application, and review any written financing terms carefully. You don’t need every answer before you begin. Take one manageable step at a time, and keep your budget in view as you explore your options.
For shoppers learning how to buy a car with bad credit, local guidance can make the process feel more approachable. Any Credit Auto Sales LLC is a used-car dealership in Chandler serving shoppers across nearby East Valley communities. The dealership helps shoppers explore pre-owned vehicles and submit an application that connects them with third-party lenders. Those lenders make financing decisions and set any offered terms. Approval isn’t guaranteed, and terms can vary.
What support can a local dealership provide?
Credit histories differ, and questions about applying are understandable. Any Credit Auto Sales LLC offers credit help for shoppers with varied credit histories. This guidance can help you understand the steps involved as you consider a vehicle and financing application. It isn’t a promise to change your credit score or secure approval.
The dealership offers pre-owned cars, trucks, and SUVs. Explore the online inventory to see which vehicles may suit your needs, then consider how a potential choice fits your budget. Any Credit Auto Sales LLC connects applicants with third-party lending partners. Those lenders, not the dealership, decide whether to offer financing and determine the terms.
How can Chandler-area shoppers get started?
If you’re in Chandler, Mesa, Tempe, Phoenix, Queen Creek, or San Tan Valley, you can begin online. Browse the inventory first, using your transportation needs and budget to guide your search. When you’re ready, complete the financing application with accurate, current information. Take time to understand each step and review any lender terms before making a decision.
There’s no need to rush into a commitment. Start with the step that feels simplest, whether that’s looking through vehicles or preparing your application details. A clear budget and careful review can help you stay grounded as you explore what may fit.
Start exploring vehicles and financing options.
Take Your Next Car-Buying Step with Confidence
Learning how to buy a car with bad credit starts with preparation, not pressure. Set a realistic budget, share accurate information on your application, and compare the full loan terms instead of focusing only on the monthly payment. A lower credit score doesn’t define your future or automatically rule out every option.
In Chandler, Any Credit Auto Sales LLC helps shoppers with varied credit histories explore pre-owned cars, trucks, and SUVs. The dealership offers credit guidance and an application that connects shoppers with third-party lenders. Those lenders make financing decisions and set any offered terms, so approval isn’t guaranteed.
When you feel ready, take one simple step: browse vehicles and begin exploring the application process. Explore pre-owned vehicles and start your financing application. Move at a pace that feels right, with your budget and needs leading the way.
Frequently Asked Questions
Can you buy a car with bad credit?
Yes, buying a car with bad credit may be possible, but approval isn’t guaranteed. Lenders can consider more than your credit score, including your income, existing debts, application details, and the vehicle you want. Their requirements differ, so one lender’s decision may not predict another’s. Start with a realistic budget and provide accurate information when you apply.
What credit score do you need to buy a car?
There’s no single credit score required to buy a car. Each lender sets its own criteria and may consider your wider financial picture, not just your score. A lower score can affect the financing options or terms available, but it doesn’t automatically mean every application will be declined. Review your credit reports for errors, then focus on choosing a vehicle and payment plan that fit your budget.
How can I improve my chances of getting a car loan with bad credit?
Prepare before applying: review your income, debts, and regular expenses, set a manageable budget, and gather accurate application details. Check your credit reports for errors and allow time for any corrections. A down payment may affect a lender’s assessment, and a co-applicant may be an option if it suits both people’s circumstances. These steps can help you apply with care, but they can’t guarantee approval or specific terms.
Does applying for a car loan hurt your credit?
It depends on the type of credit inquiry. A hard inquiry connected to a loan application may affect your credit file, while a soft inquiry generally doesn’t affect your score. Before submitting an application, find out whether the process involves a hard or soft inquiry and how your information will be used. If you’re applying through a dealership application connected to third-party lenders, understand the inquiry process before you proceed.
Can I get a car loan with bad credit and no down payment?
Possibly, but it depends on the lender and your application. A down payment can reduce the amount you need to borrow and may influence a lender’s decision, but requirements differ. Don’t stretch your finances to make a down payment if it leaves too little for essential expenses. Set your budget first, then review any lender offer carefully. Approval and financing terms aren’t guaranteed, with or without a down payment.
Should I choose a longer auto-loan term to lower my payment?
A longer term may lower the monthly payment by spreading repayment over more time, but it also means you’ll make payments for longer and may repay more overall. Compare the payment, loan length, total repayment, and disclosed fees together. Check that the payment fits alongside insurance, fuel or charging, and routine ownership costs. Choose based on the whole obligation, not the monthly figure alone.
Does Any Credit Auto Sales offer in-house financing?
No. Any Credit Auto Sales connects applicants with third-party lending partners through its auto financing application. Those lenders review applications and make their own financing decisions, including any offered terms. The dealership also provides credit guidance for shoppers with varied credit histories. Chandler-area shoppers, including those in Mesa, Tempe, Phoenix, Queen Creek, and San Tan Valley, can explore pre-owned vehicles online and apply when ready.


