
Can you realistically finance your first car in Arizona if your credit is bad or you haven’t had much time to build credit? It may be possible, but a thin credit history and past credit problems aren’t always viewed the same way. This first time car buyer bad credit Arizona guide explains what lenders may review and how to prepare before you apply.
It’s understandable to worry about being turned down or about how an application could affect your credit. You also need a vehicle that works for everyday life and a payment that fits your budget. A clear plan can help you approach both decisions with more confidence.
We’ll cover the details lenders may review, ways to prepare, and how to compare a vehicle’s cost with potential financing. At Any Credit Auto Sales LLC, you can explore used vehicles and get credit guidance through an application that connects with outside lenders. The lender makes the financing decision, so approval isn’t guaranteed.
Key Takeaways
- Bad credit, limited credit history, and no credit history are different situations. None alone tells the whole story.
- Lenders may consider income, existing obligations, credit history, application details, and the vehicle you choose.
- Compare bank or credit-union applications, dealership-connected lenders, and co-applicant options without assuming one route fits everyone.
- Set a full transportation budget, review your credit information, and approach applications thoughtfully as a first time car buyer bad credit Arizona.
- A local used-car dealership can provide credit guidance and connect an application with third-party lenders, without promising approval.
First-Time Car Buyer with Bad Credit in Arizona: What the Terms Really Mean
Credit challenges don’t automatically decide whether you can pursue financing for a first car. If you’re a first time car buyer bad credit Arizona, it helps to understand how bad credit differs from limited or no credit history. These terms describe different credit situations, not a final answer about whether an application can move forward.
Limited credit history means there’s less information to review; negative marks mean the report includes problems such as missed or late payments. A short file may give a lender fewer clues about how you manage borrowed money. A longer file with negative marks tells a different story. Either way, a lender considers the full application, not just a label.
Bad credit and no credit history are not the same
“Thin credit” usually means you have a short record of using credit. “No credit history” means there may be little or no established borrowing record to review. Bad credit generally refers to negative information, such as late payments, on a credit report. Scoring models and lender policies vary, so a score alone can’t promise approval or predict a denial.
Some lenders may consider an application with limited history differently from one with past payment problems. Others may weigh both situations alongside income, current obligations, and the vehicle being considered. For a plain-language overview of the type of lending sometimes associated with lower credit histories, see Subprime Lending Explained. The term describes a lending category, not a judgment of your worth or your whole financial picture.
What a first-time buyer can reasonably expect
Your first purchase may bring extra questions because there’s no previous auto loan to show how you handled one. A lender may review your credit history, income, existing obligations, application details, and vehicle choice. Each lender sets its own criteria and may assess the same applicant differently. Prepare for a review rather than assuming one outcome.
For example, a buyer with steady income and a short credit file may get questions about the limited history, while an applicant with late payments may get questions about those marks. Neither situation guarantees a result. The lender decides whether an application fits its criteria and what terms, if any, it may offer.
Keep the lender’s review separate from the vehicle-shopping support you receive. A dealership can help you explore used cars, trucks, and SUVs that suit your needs and budget, and guide you through an application connected with outside lenders. That support can make the process easier to understand, but it doesn’t replace the lender’s decision. Credit help can also give you space to discuss your situation and consider next steps without treating a score as the whole story.
How Arizona Lenders May Review a First-Time Buyer with Bad Credit
A lender’s review is usually broader than a credit score. For a first time car buyer bad credit Arizona, the application may include details about income, existing monthly obligations, credit history, the vehicle, and the information provided on the application. Each lender sets its own criteria, so the same person may receive different responses from different lenders.
No single credit score determines every auto-loan decision; lenders may weigh the full application in different ways. Review what’s in your credit file and consider how the vehicle and payment fit your overall finances.
Credit history is one part of the application
A lender may look at whether you’ve made payments on time, what obligations you currently carry, and how long you’ve used credit. If you’re buying your first car, your record may not include an earlier auto loan. That’s context for the application, not an automatic answer about its outcome.
Before applying, review your credit reports from Equifax, Experian, and TransUnion. Look for information you don’t recognize or details that may be incorrect. You can use AnnualCreditReport.com to access your reports. If you spot a possible error, you can look into it before a lender reviews your application. Checking a report won’t determine a lender’s decision, but it can help you understand the information being considered.
Income, vehicle choice, and the overall picture
Lenders may compare the proposed payment with income and existing obligations to assess how the application fits together. They may also consider details about the vehicle, such as its price and age, under their own policies. Requirements can vary, so an income or employment guideline used by one lender or program shouldn’t be treated as a universal rule for Arizona buyers.
Your vehicle choice is one part you can plan for. Start with what you need for daily travel, then consider a vehicle and payment that leave room in your budget for regular expenses. A lower payment doesn’t tell the whole story, so review the full financing terms presented to you. A practical budget can keep your search focused on vehicles that make sense for your circumstances.
A co-applicant may be an option to discuss as you explore financing. Their information may also be considered in the application, but adding someone doesn’t guarantee approval or specific terms. It’s a shared financial commitment, so both people should understand what they’re agreeing to before moving forward.
At Any Credit Auto Sales LLC, credit guidance and an application connected with third-party lenders can help you explore your options. You can also look through used vehicles in Arizona with your needs and budget in mind. Use a lender’s review to understand what may fit, then decide whether the next step feels right for you.
Compare Your First-Car Financing Choices Without Chasing Guarantees
There’s more than one way to explore a first-car loan. As a first time car buyer bad credit Arizona, compare how each route works, what flexibility it may offer, and what you’ll want to understand before agreeing. No option is right for everyone, and none can promise a particular outcome.
| Option | How the process may work | What to understand |
|---|---|---|
| Bank or credit-union application | You apply directly to a financial institution. Its team reviews your information under its own lending criteria. | Ask what terms are offered, how long they last, and what the full repayment amount would be. |
| Dealership-connected lenders | A dealership may submit an application to outside lending partners. At Any Credit Auto Sales LLC, applications connect buyers with third-party lenders, not in-house financing. | Understand which lender is offering the terms and review the written details before deciding. |
| Co-applicant | You apply with another person whose information may also be considered by a lender. | Discuss the shared responsibility, how both applicants are assessed, and what happens if payments become difficult. |
Compare the full financing picture, not one number
A monthly payment is only one part of a loan. The term is how long you repay it, and the payment and term together affect the total amount repaid. A lower monthly payment may come with a longer repayment period. Compare the written terms as a whole, including the amount financed, payment schedule, term, and total repayment figure provided.
Take time to understand any optional products included in a proposal. Ask what each one covers, whether it’s optional, and how it affects the total amount financed. Don’t decide based only on a payment that looks manageable at first glance. Compare the full written offer with your budget and give yourself room to think.
Choose a first vehicle that fits everyday needs
Start with the trips you make most. Think about your commute, regular driving, passengers, and what you need to carry. A vehicle that fits your routine may be more practical than one selected for occasional needs. Consider used cars, trucks, and SUVs that match those priorities, then keep the budget grounded in your actual monthly finances.
Remember to account for more than the loan payment. Insurance, fuel, maintenance, and registration are also part of owning a vehicle. Their amounts can vary, so consider your own circumstances rather than relying on a broad estimate. Including these expenses can help you judge whether the overall plan feels manageable, not just whether the payment fits.
Any Credit Auto Sales LLC offers used vehicles and an application process connected with outside lenders. If you’re comparing vehicle needs with financing choices, you can explore used vehicles and financing options at your own pace.
Prepare Before Applying for a First Car Loan in Arizona
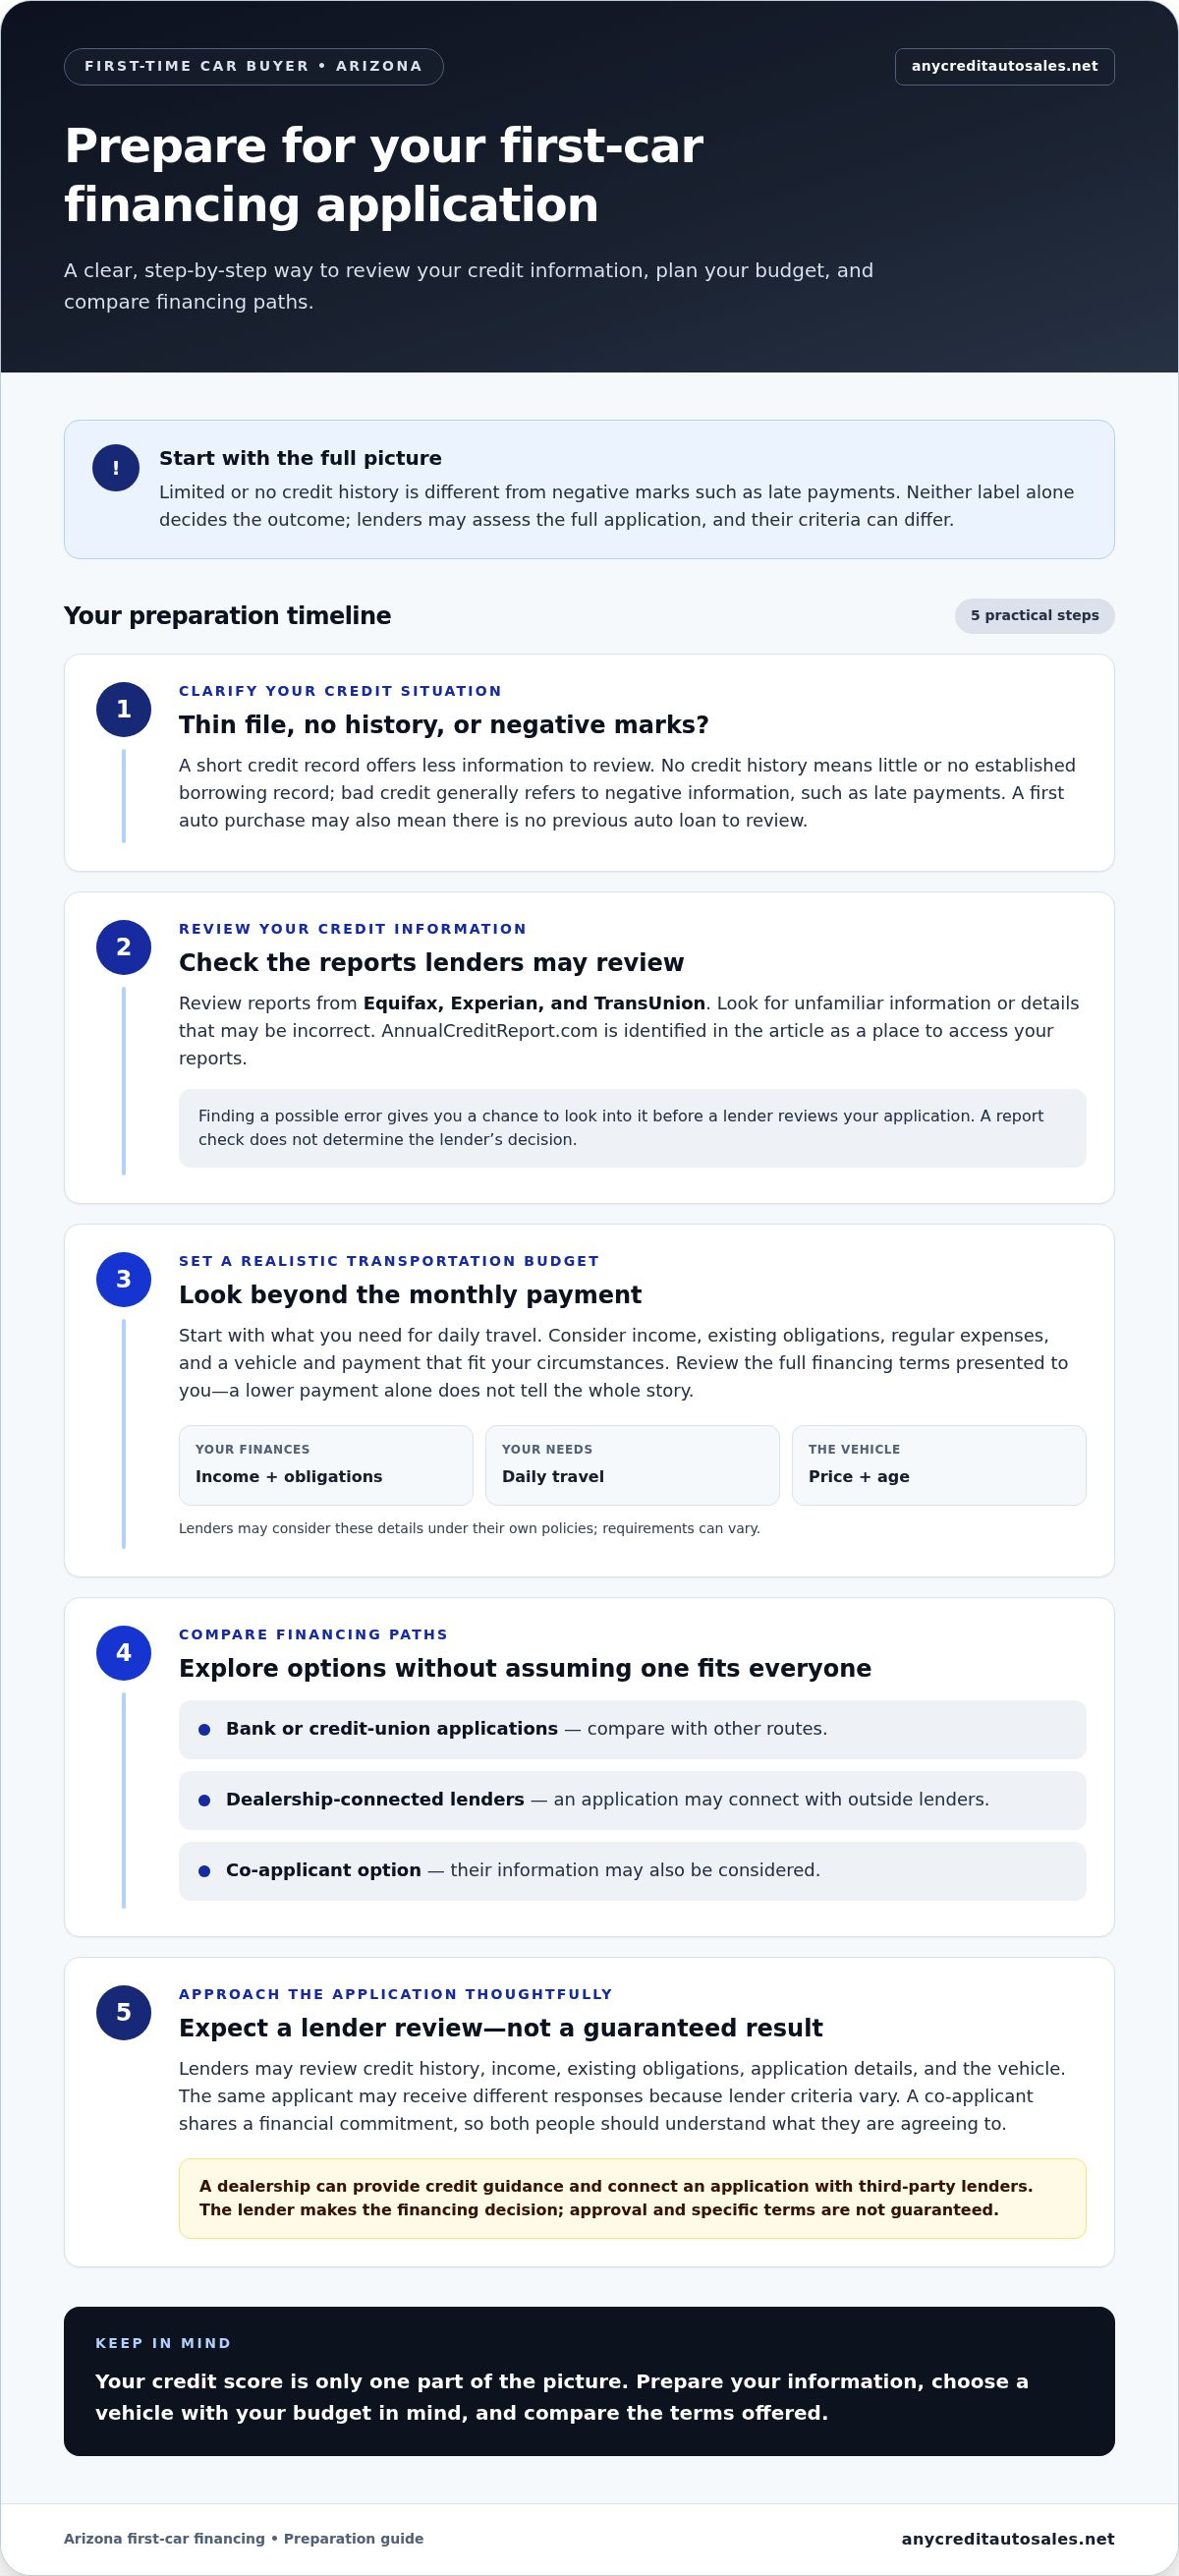
A little preparation can make the process feel more manageable. If you’re a first time car buyer bad credit Arizona, use this plan to decide what fits your budget before submitting an application. You don’t need to predict a lender’s decision. Focus on understanding your finances, your options, and the terms you’re agreeing to.
- Set a full transportation budget. Consider a possible loan payment alongside insurance, fuel, maintenance, registration, and regular expenses. Leave some breathing room instead of building your plan around the largest payment you think you might manage.
- Review your credit information. Look over your reports for details you don’t recognize or believe are inaccurate. If you find a possible error, follow the reporting agency’s process for disputing it.
- Gather your application details. Think through information a lender may ask about, such as income and current obligations. Required documents and application details differ by lender, so one checklist won’t apply to every application.
- Compare financing routes. Consider applying directly with a bank or credit union, or exploring a dealership application connected with outside lenders. Compare written terms and understand who is reviewing the application.
- Apply thoughtfully. Before submitting an application, understand what kind of credit inquiry may be involved and when it could occur. Apply when you’re ready to review the result and its terms, rather than sending applications without a clear comparison plan.
Set a realistic monthly transportation budget
Build your budget around the whole cost of having a vehicle, not only the loan payment. Insurance, fuel, maintenance, and registration can all affect what feels manageable month to month. Leave room for rent, utilities, food, and other regular expenses. A budget based on your actual priorities gives you a steadier starting point than aiming for the maximum payment a lender might consider.
Arizona MVD is the state resource for vehicle and driver services, including registration information. Registration requirements can depend on your situation, so review current MVD guidance before relying on any details.
Review credit and approach applications carefully
Credit applications may involve soft or hard inquiries. Ask the lender which type its initial review uses, and whether a later application step could involve another inquiry. Multiple applications may create multiple inquiries; how they’re treated can depend on the scoring model and timing. Don’t assume that comparing offers has no effect. Keep track of when you apply, who reviews your credit, and the written terms each lender provides.
Take time with each offer. Compare the repayment period, payment schedule, and total amount repaid, and make sure you understand any optional products. A clear comparison can help you decide whether the terms fit your budget without rushing toward a commitment.
Once you’ve set your budget and are ready to explore used vehicles, start an auto financing application through Any Credit Auto Sales. Applications connect with third-party lenders, and credit guidance can help you consider your next step without a promise of approval.
Take a Practical Next Step with a Local Arizona Dealership
Your next step doesn’t have to be a commitment. Bring three things together: the kind of vehicle you need, a budget that leaves room for everyday expenses, and an understanding that a lender will review your application. This gives you a practical basis for comparing options without treating a credit score or vehicle listing as the whole decision.
Any Credit Auto Sales is a Chandler used-car dealership offering credit guidance and applications that connect shoppers with third-party lenders. The dealership serves Chandler, Mesa, Tempe, Phoenix, Queen Creek, and San Tan. If you’re a first time car buyer bad credit Arizona, you can explore used-car choices while getting help understanding the application process.
What a supportive dealership conversation can cover
Credit guidance can help you talk through your situation and understand possible financing paths. A dealership-connected application goes to outside lenders. Those lenders review applications and make financing decisions, and their criteria and terms can vary by applicant. Guidance can make the process easier to follow, but it can’t promise approval, a particular payment, or a specific lender offer.
As you consider a vehicle, connect the discussion to your real needs. Think about your regular commute, passengers, and budget. Bring questions about how an application is submitted and what written financing terms mean. Clear answers can help you understand the next step before deciding whether to take it.
Move forward at a pace that feels manageable
Browse pre-owned cars, trucks, and SUVs with your everyday use in mind. A vehicle that suits your routine and budget may be a better fit than one chosen only because it is available or has a payment that looks appealing. Take your time comparing options, and pause if the choice or proposed terms aren’t clear.
Before agreeing to financing, review the written terms carefully. Look at the payment, repayment period, and total amount to be repaid. Make sure you understand any optional products and how they affect the agreement. If something is unclear, take the time to understand it before moving forward. Review the whole plan, not just one number.
A first purchase can feel like a big step, especially when you’re also thinking about credit. Approach it one decision at a time: find a vehicle that fits your needs, consider your budget, and review any lender offer on its own terms. A conversation or application isn’t a promise of approval.
When you’re ready, you’re welcome to explore used vehicles or begin an application with Any Credit Auto Sales. Start with your questions and move at a pace that feels right for you.
Take Your Next Step with Confidence
Your first car purchase doesn’t need to be solved all at once. Start by deciding what you need a vehicle to do and what kind of financial commitment would leave room for the rest of your life. That gives you a useful point to return to as you weigh your choices.
If you’re a first time car buyer bad credit Arizona, remember that a lender’s review is only one part of the decision. Take time to understand any offer and decide whether the vehicle and terms feel workable for you. A careful choice matters more than rushing to reach an answer.
When you’re ready, Explore pre-owned vehicles and financing options at your own pace. You can take this milestone one step at a time, with a plan that feels right for you.
Frequently Asked Questions
Can I buy my first car in Arizona with bad credit?
It may be possible, but no lender approves every applicant. If you searched for “first time car buyer bad credit Arizona,” the key point is that a lender reviews your full application, not just your credit score. Before shopping, decide what you need the vehicle for and what expenses your budget can support. For example, consider your regular commute and passengers before choosing a vehicle size or payment plan.
Is there a minimum credit score for a first-time car buyer?
There isn’t one credit score that applies to every lender or financing program. A score is one part of the review, and lenders may also consider your credit history, income, obligations, and chosen vehicle. Scores from different services may not match the score or model a lender uses. Treat online cutoffs as general guidance, not a promise that you’ll qualify or be declined.
Can I get a car loan with bad credit and no cosigner?
You can apply on your own, but the lender decides whether your application meets its requirements. A cosigner or co-applicant may be an option in some cases, but isn’t automatically required and can’t guarantee approval. Before applying together, talk through the responsibility both people may take on. Make sure the other person understands that the loan could affect their finances too, especially if payments become difficult.
Does applying for auto financing hurt your credit score?
It depends on the inquiry and the lender’s process. A soft inquiry is generally used for an initial review, while a hard inquiry may be part of a formal application and can affect your score. Before submitting an application, ask which inquiry is involved and when it may happen. Keep track of applications and dates so you can understand what appears on your credit reports afterward.
Should I make a down payment when buying my first car with bad credit?
A down payment may reduce the amount you need to finance, but the right amount depends on your budget, vehicle, and written loan terms. Don’t use money needed for essentials simply to make a larger upfront payment. Keep enough room for regular expenses, then compare the amount financed, payment schedule, and repayment period. Choose a plan that feels manageable beyond the day you buy the car.
Will paying an auto loan on time improve my credit?
On-time payments may help build a positive credit history if the lender reports account activity to credit bureaus. Reporting practices can differ, so don’t assume every payment will appear on every report. An auto loan is a long-term financial commitment, not a guaranteed shortcut to better credit. Before agreeing, consider whether you can keep up with the payment alongside your other regular expenses.


