
What if a past repossession doesn’t tell the whole story of your next application? If you’re searching for “auto loan after repossession Arizona,” you may be wondering whether a lender will approve an application, whether you still owe money on the old loan, or whether your credit report is accurate. A repossession can affect a lender’s review, but your current situation matters too.
This guide explains what lenders may review, including your credit history, finances, and any remaining debt, and offers practical steps to take before applying. Start by checking your credit reports for errors, gathering records about the repossession, and setting a vehicle budget that feels manageable. At Any Credit Auto Sales LLC in Chandler, shoppers with varied credit histories can apply to connect with outside lending partners while exploring pre-owned cars, trucks, and SUVs. Approval isn’t guaranteed, but a past setback doesn’t have to define every step ahead.
Key Takeaways
- A past repossession can affect an application, but lenders may consider your overall financial picture too.
- With an auto loan after repossession Arizona shoppers can compare applying now, preparing first, or getting guidance on old debt before taking the next step.
- Review your credit reports and gather details about the repossession to prepare for a financing conversation.
- Set a realistic vehicle budget that includes ownership costs, not just the monthly loan payment.
- Shoppers in Chandler and nearby communities can apply through Any Credit Auto Sales LLC to connect with third-party lenders.
Auto Loan After Repossession in Arizona: What the Setback Means
A repossession happens when a lender takes back a vehicle after the borrower falls behind on the loan or breaks another loan term. It can disrupt work, family routines, and your sense of control. That’s a difficult experience, but it doesn’t mean every future application will be declined. For a plain-language overview of understanding repossession, you can also read about the general process and related consumer protections.
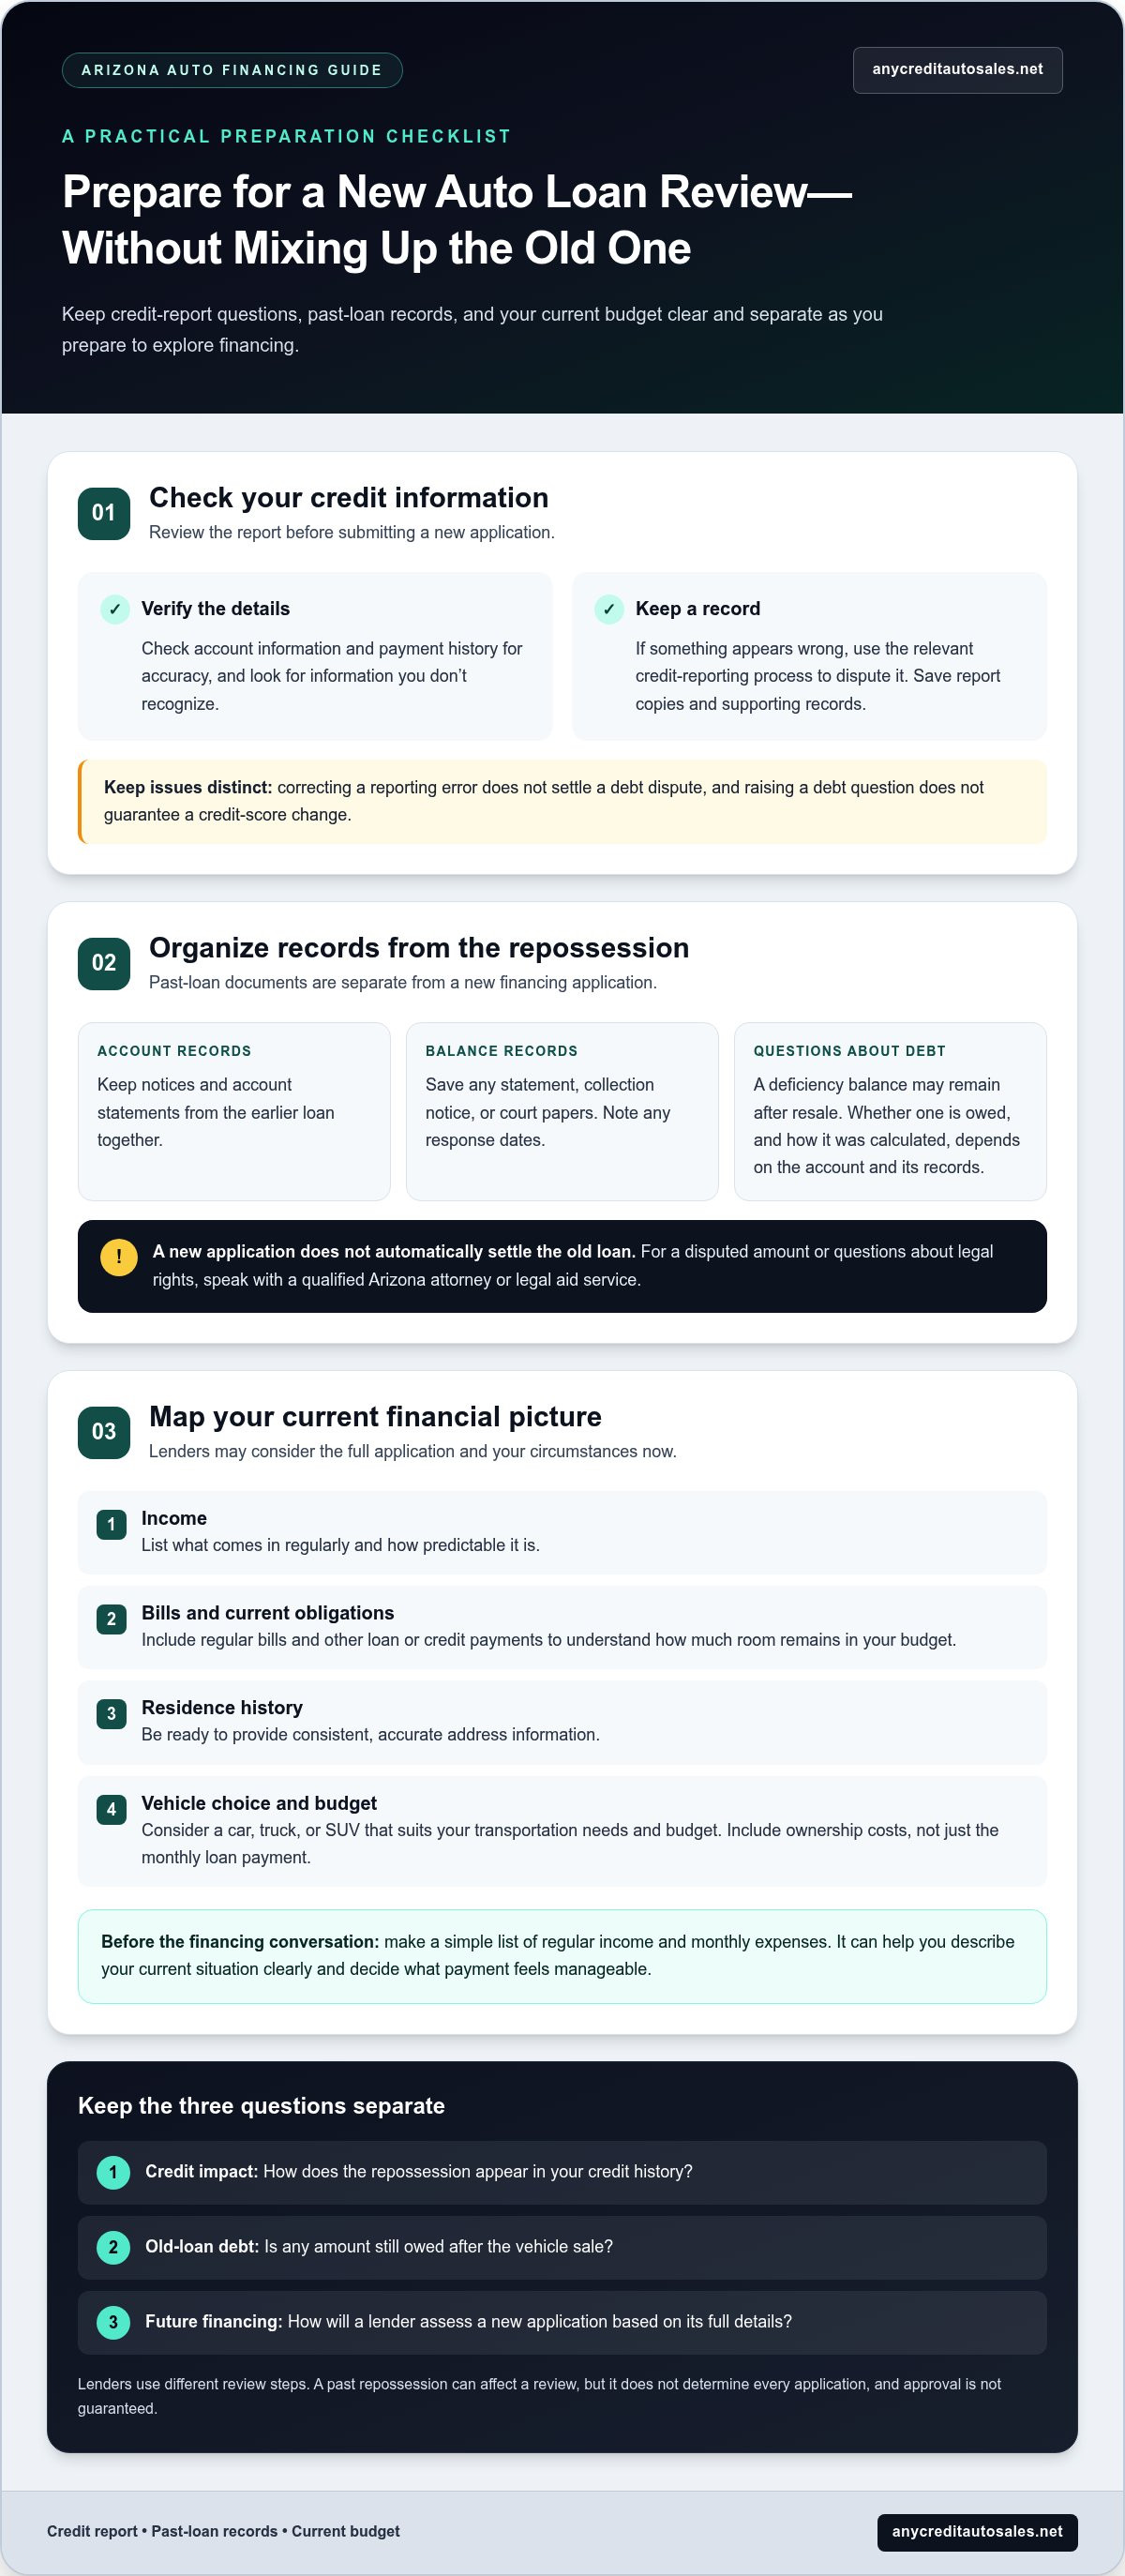
Separate the situation into three parts: credit impact, which may affect how a lender views your history; old-loan debt, which may remain after the vehicle is sold; and future financing, which is a new application assessed on its own details. A repossession can influence a lender’s review, but it doesn’t determine every application. Your current circumstances and the vehicle you’re considering may matter as well.
Can you apply for an auto loan after repossession in Arizona?
You can apply, but approval depends on the lender and the full application, not simply on where you live or whether a vehicle was repossessed. Lenders can review different information, so there’s no single waiting period or minimum credit score that applies to every borrower. The phrase auto loan after repossession Arizona describes a situation to explore, not a promise of approval or a guaranteed outcome.
A new application also doesn’t automatically resolve the old loan. Keep notices and account statements from the earlier loan separate from paperwork for a future vehicle. That makes it easier to distinguish questions about past debt from a new financing decision.
What is a deficiency balance after a repossession?
After a lender resells a repossessed vehicle, the sale proceeds may not cover the remaining loan amount and related costs. An amount still due after the lender accounts for the sale may be called a deficiency balance. Arizona Judicial Branch consumer-debt guidance explains that a borrower may still owe money after a vehicle is resold. Whether a balance is owed, and how it was calculated, depends on the account and its records.
Don’t assume a new car application means the old balance is settled. Save any statement, collection notice, or court papers, and note any response dates. If you dispute the amount or need help understanding your legal rights, speak with a qualified Arizona attorney or legal aid service. A dealership can help with a vehicle financing application, but legal questions about an old debt belong with a qualified legal professional.
In short: a repossession may affect your credit and a lender’s review; a deficiency is a separate question about the old loan; and a future application is considered by its lender based on the full picture.
How a Prior Repossession Can Shape a New Auto Loan Review
A lender may view the repossession as one part of your financial history, then consider your circumstances now. The review may include income, regular bills, other loan or credit payments, and how much room remains in your budget. Your residence history and vehicle choice may matter too. These details can help a lender assess whether a proposed payment fits your current circumstances.
Approval depends on the lender’s review of your full application, not the repossession alone. Lenders can use different review steps, so another person’s experience won’t predict the result of your application. No single income, credit score, or employment history guarantees a decision.
What information may lenders consider?
Each lender may ask for different application details or supporting documents. You might be asked for information about your income, housing costs, current obligations, and residence history. The vehicle you select affects the amount you’re seeking to finance, so consider a car, truck, or SUV that suits your transportation needs and budget.
Before applying, make a simple list of regular income and monthly expenses. This can help you describe your current situation clearly and decide what payment feels manageable. A dealership application can connect shoppers with varied credit histories to third-party lenders, but each lender makes its own decision.
How can you check your credit information first?
Review your credit reports before submitting a new application. Check that account details and payment history look accurate, and look for information you don’t recognize. If something appears wrong, use the relevant credit-reporting process to dispute it. Keep copies of the report and any records that support your concern.
A report dispute and a disagreement about an old loan balance are related to your finances, but they aren’t automatically the same issue. Correcting a reporting error doesn’t settle a debt dispute, and raising a debt question doesn’t guarantee a credit-score change. Keep notes about what you’ve challenged and save responses so you can explain the situation accurately if asked.
- Income: What comes in regularly, and how predictable is it?
- Current obligations: What payments already take up part of your monthly budget?
- Residence history: Can you provide consistent, accurate address information?
- Vehicle choice: Does the vehicle and amount you plan to finance fit your needs?
When you’re ready to explore pre-owned vehicles and a financing conversation, Any Credit Auto Sales LLC’s financing application can connect you with third-party lenders. It’s a way to begin exploring your options, not a promise of approval or particular terms.
Compare Your Options Before Applying for Another Car Loan
There isn’t one right move for everyone considering an auto loan after repossession Arizona. You may need dependable transportation soon, or you may have room to pause and get a clearer view of your finances first. If the old loan is still being pursued or you’re unsure about the balance, that question deserves attention too. Consider the vehicle decision separately from the question of resolving old debt.
Use this table to weigh what fits your situation. These are options to consider, not a required sequence or a promise about what a lender will decide.
| Option | When it may fit | Trade-off | Question to resolve |
|---|---|---|---|
| Apply now | You need transportation and can describe your income, expenses, and vehicle needs clearly. | A lender’s review may bring questions about your application or the past repossession. | Can the payment and other vehicle costs fit your budget? |
| Pause to prepare | Your budget needs a closer look, documents are missing, or credit-report details may be inaccurate. | Waiting may leave you without a vehicle solution for now, but it can give you time to organize information. | What needs to be clearer before you apply? |
| Seek guidance on old debt | You don’t know whether the former account is paid, disputed, or still being pursued, or you’ve received court papers. | Getting help with the old account may take attention apart from your vehicle search. | Is there a deadline, a dispute, or a balance you need to understand? |
Apply now or pause to prepare?
An application may make sense if you have a workable payment limit and can provide clear, current information. Before applying, gather the documents a lender or application may request and list your regular expenses. Preparation can help you make an informed choice, though it can’t guarantee approval.
Pausing is also reasonable if you’re unsure what you can afford or have found possible errors on your credit report. There’s no universal number of months to wait after a repossession. Focus on what needs attention in your situation rather than an arbitrary timeline.
How should you think about the old loan balance?
Start by reviewing what you know about the former account. Is it marked paid? Do you disagree with the amount? Are you receiving collection notices or court papers? Keep statements and letters together, and note any response dates. If a lawsuit, court deadline, or contested debt is involved, seek guidance from a qualified Arizona legal professional.
The old account and a new financing application may both affect your financial picture, but they’re separate questions. Addressing one doesn’t automatically settle the other. You can consider your vehicle needs while seeking appropriate guidance about the old debt, without assuming a particular legal or financing route is right for you.
Prepare for an Arizona Auto Loan Application After Repossession
Preparation can help you approach an application with a clearer picture of your needs and budget. It won’t guarantee approval, but it can make your next steps more focused. If you’re considering an auto loan after repossession Arizona, organize information about your current situation, then look for a pre-owned vehicle that fits your transportation needs and spending limit.
Gather details before starting an application
Application requirements can vary among third-party lenders. Identification, residence details, income information, and a clear account of your monthly budget are examples of information you may want to organize. They aren’t a universal checklist. Follow the directions on the lender’s or application’s document requests.
Before submitting, check that the details you enter are accurate and consistent with your records. Review names, addresses, income figures, and other application information carefully. If something has changed, use current information and be ready to explain it plainly.
- Gather useful records. Set aside identification and, as applicable, documents showing your residence or income. Keep them organized so you can find what an application requests.
- Map your monthly budget. List regular income and expenses, including existing obligations. Decide what amount you could put toward transportation without leaving everyday needs uncovered.
- Set a vehicle range. Think about the type of vehicle you need, how you’ll use it, and the amount you’re comfortable financing. A focused range can make shopping more manageable.
- Review before you submit. Check every answer for accuracy. Don’t guess if you’re unsure about a detail. Find the correct information or follow the application’s instructions.
Set a realistic vehicle and payment range
A monthly loan payment is only one part of owning a vehicle. Leave room in your budget for insurance, fuel, maintenance, and other regular costs. The amount financed and loan terms can affect your budget, while the vehicle you choose affects day-to-day ownership expenses. Consider what you need for work, family, or regular travel, then focus on pre-owned options that suit those needs.
For example, if you mainly drive around town, prioritize a vehicle suited to your usual trips rather than paying for features you won’t use. If you regularly carry passengers or supplies, space may matter more. Identify practical priorities before shopping so you’re less likely to stretch your budget for a vehicle that looks appealing in the moment.
Once you have your documents, spending limit, and vehicle needs in mind, you’re better prepared to compare options. Explore available pre-owned cars, trucks, and SUVs at Any Credit Auto Sales LLC in Chandler, and consider submitting a financing application to connect with third-party lenders. A lender makes its own decision, but a clear starting point can support a more informed conversation.
Explore Used Vehicle Financing Help in Chandler and Nearby Arizona Communities
A past repossession can be part of your financial story without defining every step ahead. If you’re considering an auto loan after repossession Arizona shoppers may have questions about, Any Credit Auto Sales offers a local place to explore pre-owned vehicles and apply for financing. The dealership is in Chandler and serves shoppers from nearby communities, including Mesa, Tempe, Phoenix, Queen Creek, and San Tan.
What financing support does Any Credit Auto Sales provide?
Any Credit Auto Sales helps shoppers with varied credit histories navigate an auto financing application. Apply through the dealership to connect with third-party lenders, which review applications and make their own decisions. Applying doesn’t guarantee approval or particular loan terms. Financing is arranged through outside lending partners.
Credit help means support as you work through the application process, not a promise of a certain credit score or outcome. You can share your current circumstances and ask questions as you consider your next step. A repossession is one part of your history. Your present transportation needs and budget also matter as you look at your options.
What can Chandler-area shoppers do next?
Start by browsing the dealership’s pre-owned cars, trucks, and SUVs. Keep your transportation needs and budget in view as you look. Consider how many passengers you usually carry, the kind of trips you make, and which vehicle type suits your everyday routine. A focused search can help you compare vehicles without losing sight of what you can manage.
- Review the inventory: Browse available vehicles and note the ones that fit your needs.
- Revisit your budget: Consider the full cost of ownership alongside any potential loan payment.
- Apply when ready: Use the financing application to connect with third-party lenders and begin the conversation.
You don’t need every answer before you start exploring. Take the next step at a pace that feels comfortable, whether that means reviewing inventory first or preparing an application. Browse available vehicles and start a financing application with Any Credit Auto Sales in Chandler when you’re ready to explore your options.
Take the Next Step at Your Own Pace
A fresh start doesn’t require a perfect credit history or every question answered. It can begin with one manageable choice: decide what you need from your next vehicle, set a budget that leaves room for everyday expenses, and explore options without rushing. That gives you a steadier starting point for an auto loan after repossession Arizona shoppers may be considering.
If you’re ready, browse pre-owned vehicles and start an application when it feels right. Move forward one step at a time, keeping your needs and budget in view throughout the process.
Explore pre-owned vehicles and start your financing application with Any Credit Auto Sales in Chandler.
Frequently Asked Questions
Can I get an auto loan after repossession in Arizona?
You can apply, but a lender decides based on your complete application. A repossession may be part of the review, alongside your current income, expenses, credit information, and vehicle choice. If you’re considering an auto loan after repossession Arizona, focus on presenting an accurate picture of your current situation. An application is a request for review, not a guarantee of approval or specific terms.
How long should I wait to apply for a car loan after repossession?
There’s no universal waiting period that fits every lender or applicant. If you need a vehicle soon, you might apply after organizing your information and setting a realistic budget. If you’re unsure about your payment capacity or see errors in your credit records, taking time to address those concerns may help you make a more informed choice. Consider your circumstances rather than relying on a fixed timeline.
Does a repossession stay on your credit report in Arizona?
A repossession may appear on your credit reports, so review the reports from the credit-reporting agencies for account details and accuracy. Check that the account belongs to you and that its status and history match your records. If you find information you believe is wrong, use the agency’s dispute process and keep copies of supporting documents. Don’t assume a dispute will change your score or resolve an old balance.
Do I still owe money after my car is repossessed in Arizona?
You may still owe a deficiency balance if the vehicle’s resale proceeds don’t cover the amount owed and related costs. Review any final account statement or notice carefully, and keep it with your original loan paperwork. If the amount seems incorrect or you receive court papers, get qualified legal guidance. A vehicle’s repossession alone doesn’t tell you whether the old account has been fully settled.
Can I get another car loan if I still owe a deficiency balance?
You may be able to apply, but a lender will decide based on the application and its review. An unpaid balance from the former loan may be relevant to your financial picture, but it doesn’t automatically determine whether you can qualify for another loan. Find out whether the balance is still being pursued, disputed, or reported, and keep those records separate from your new vehicle application.
What documents might I need for an auto loan application after repossession?
Possible examples include identification, information about where you live, and records that help show your income. The lender or application may request different items, so treat these as preparation ideas rather than a required list. Before submitting, check that your personal details and figures match your records. If you’re unsure what a question means, review the application instructions instead of guessing.
Does Any Credit Auto Sales offer buy-here-pay-here financing?
Any Credit Auto Sales’ auto financing application connects shoppers with third-party lenders. The dealership also provides credit help for shoppers with varied credit histories, without promising approval or particular terms. Based in Chandler, the dealership serves shoppers from nearby communities, including Mesa, Tempe, Phoenix, Queen Creek, and San Tan.


