
Could bankruptcy be one part of your loan application without deciding the whole outcome? If you’re looking for a car loan after bankruptcy Arizona, it’s understandable to wonder whether you can apply now or need to wait. Bankruptcy can affect a lender’s decision, but it doesn’t automatically make every application impossible.
Your case status matters. An active bankruptcy and a completed discharge can mean different next steps, and a Chapter 13 case may involve added approval requirements. You also need a clear picture of what a payment could mean for your budget, how loan terms affect the total cost, and what to know before authorizing a credit inquiry. Before applying, note whether your case is active or discharged, set a payment range that leaves room for other expenses, and review the application and inquiry disclosures.
This guide explains what lenders may consider, how to prepare an accurate application, and what to weigh before choosing a pre-owned vehicle. You’ll also learn how to explore vehicle options and submit financing applications to third-party lenders, whose decisions and terms vary. With a practical plan, you can take the next step at a pace that feels manageable.
Key Takeaways
- A car loan after bankruptcy Arizona may be possible, but your chapter and case status can shape the next step.
- Lenders set their own standards, so prepare to explain your income, current obligations, and the vehicle amount you’re considering.
- Compare applying after discharge, exploring options during an active case with guidance from your bankruptcy counsel, or waiting while you prepare.
- Build a transportation budget that includes ownership costs, and gather useful details about your income and housing expenses before starting an application.
- At Any Credit Auto Sales LLC in Chandler, you can explore pre-owned vehicles and submit a financing application to third-party lenders, who make financing decisions and set terms.
Can You Get a Car Loan After Bankruptcy in Arizona?
A bankruptcy filing doesn’t, by itself, answer whether you can get auto financing. If you need a car, it’s natural to want a clear yes or no. The practical answer is that a car loan after bankruptcy Arizona may be possible, but each lender makes its own decision. Approval and loan terms aren’t guaranteed.
Several details shape the picture: whether you filed under Chapter 7 or Chapter 13, whether your case is active or discharged, the lender’s review standards, your income and current obligations, and whether the vehicle fits your budget. A lender may weigh these factors together rather than treating bankruptcy as the only part of your application. Before you shop, write down your current monthly income, regular obligations, and a borrowing amount that leaves room for vehicle expenses.
Bankruptcy can involve the discharge of certain debts or a repayment plan. The overview of Bankruptcy in the United States offers general background, but it can’t tell you what applies to your case or whether a lender will approve you.
Why bankruptcy status matters when applying
An active case is still underway. A discharge means the court has released you from personal responsibility for certain debts covered by the discharge. A completed repayment plan means you’ve finished the payments required by the plan, though the case’s final status and discharge are separate details to understand. Check your paperwork so you can describe your status accurately.
Applying during an active case may involve different steps from applying after discharge. Timing and any legal permissions depend on the details of your case and current procedures. For questions about filing restrictions or what you’re allowed to do, speak with a qualified bankruptcy attorney before seeking new debt.
Chapter 7 and Chapter 13: different contexts for car financing
At a high level, Chapter 7 generally deals with eligible debts through a bankruptcy process that may end in discharge. Chapter 13 generally uses a court-supervised repayment plan. Those broad differences can affect when and how a financing application fits into your situation, but they don’t determine a lender’s decision.
If your Chapter 13 case is still active, getting a car loan may require court or trustee approval. The steps can depend on the individual case, so don’t treat general online guidance as permission to take on new debt. Confirm the process with your bankruptcy attorney and verify any Arizona court requirements that apply at the time. After discharge, you may have a different path, but lenders still assess your finances and the vehicle you want to buy.
This section offers general educational information, not legal advice about your bankruptcy. Before applying, identify your case status, set a payment amount your budget can handle, and get legal guidance if you’re unsure about restrictions. Bankruptcy is part of the context, not a promise of approval or an automatic barrier to every application.
What Arizona Auto Lenders May Consider After Bankruptcy
There’s no single lender cutoff that tells you whether you’ll qualify. Each lender sets its own review standards, and bankruptcy history is one part of the application, not an automatic promise of approval or rejection. A lender may look at your current income, regular expenses, existing debts, the amount you want to borrow, and whether the vehicle makes sense for your budget.
A credit report shows reported credit history, while a full application review may also consider your current financial details and the information you provide. Prepare a straightforward summary of your income and recurring costs so you can see how a proposed payment might fit before you apply.
Credit history, income, and current obligations
Lenders may review your reported payment history alongside your present ability to manage another monthly bill. They may consider whether your income is steady, what you already owe, and how much room remains in your budget after housing and other regular expenses. Their standards differ, so a credit score alone can’t predict an outcome.
Keep your application accurate and complete. Give a clear account of your income and obligations, and answer questions about your bankruptcy honestly. Trying to hide a past filing can create confusion and make it harder for a lender to assess your application. For a car loan after bankruptcy Arizona, focus on the financial picture you can document now, not on guessing what a lender wants to hear.
Choosing a vehicle that fits the full budget
The loan payment is only one part of owning a vehicle. Set aside room for insurance, fuel, routine maintenance, and Arizona registration costs, too. When comparing vehicles, consider the amount you’d need to finance as well as the expected payment. A payment that looks manageable on its own may still strain your budget once regular ownership costs are included.
Before looking at vehicles, decide what you need for daily travel, such as passenger space or enough room for work gear. Then compare vehicles that fit those needs and the amount you’re comfortable borrowing. Avoid choosing solely by the monthly payment: review the loan term and total amount paid as well, because a longer term can change the overall cost. A lower amount to finance can make your budget easier to manage, but it doesn’t guarantee a lender’s decision or terms.
- Income: Be ready to describe the source and consistency of your income.
- Obligations: Account for housing, existing debt payments, and other recurring expenses.
- Vehicle fit: Keep the amount you plan to borrow in line with your transportation needs.
- Ownership costs: Leave room for insurance, fuel, maintenance, and registration beyond the loan payment.
Take your time. A vehicle should support your daily life without crowding out other essentials. You can explore pre-owned vehicles and financing options as you work out what may fit your needs. Any financing application is reviewed by third-party lenders, and those lenders make their own decisions and set their own terms.
Compare Your Car-Financing Paths After Bankruptcy
There isn’t one right route for every shopper. Your case status, transportation needs, and readiness to take on a payment can help shape the next step. The options below have different considerations, benefits, and limits. None guarantees approval or particular loan terms.
| Path | Main consideration | Potential benefit | Limitation |
|---|---|---|---|
| Apply after discharge | Your current income, obligations, vehicle choice, and lender criteria still matter. | You can apply after the case reaches discharge without taking on new debt during an active case. | Discharge doesn’t guarantee approval or favorable terms. |
| Ask counsel about an active case | Get case-specific legal guidance before seeking new debt. | You can understand whether pursuing financing fits your situation and what steps may apply. | Legal permissions and timing can depend on your case. Guidance doesn’t guarantee a lender will approve an application. |
| Wait and prepare | Use the time to review your budget, gather information, and clarify your transportation needs. | You may feel more organized before deciding whether to apply. | Waiting doesn’t ensure approval, and delaying may not suit an urgent transportation need. |
Applying after discharge versus during an active case
After discharge, you can still face lender review of your finances and the requested loan. If your case is active, speak with your bankruptcy attorney before taking on debt. Don’t rely on a general timeline as a rule for your situation. The right next step depends on the details of your case, and legal guidance is separate from a lender’s financing decision.
If you’re not ready to apply, preparation can still be useful. Estimate a payment that fits alongside household expenses, narrow down the kind of vehicle you need, and gather accurate income and housing details. Include insurance, fuel, maintenance, and registration when setting your budget. That way, you can make a more informed choice about whether to proceed.
Dealership-assisted applications and direct lender applications
You can contact a lender directly, or work with a dealership that submits an application to outside lending partners. Any Credit Auto Sales LLC helps shoppers submit applications to third-party lenders. The lenders make financing decisions and set the terms. The dealership doesn’t provide in-house or buy-here-pay-here financing.
Whichever route you consider, take time to understand the proposed payment, loan terms, and any credit inquiry disclosures before authorizing an application. If you’re exploring a car loan after bankruptcy Arizona, getting clear on the process can help prevent avoidable confusion, though it can’t guarantee a result. You can browse pre-owned vehicle options as you think through what may fit your needs and budget.
Prepare for an Arizona Car Loan Application: Practical Steps
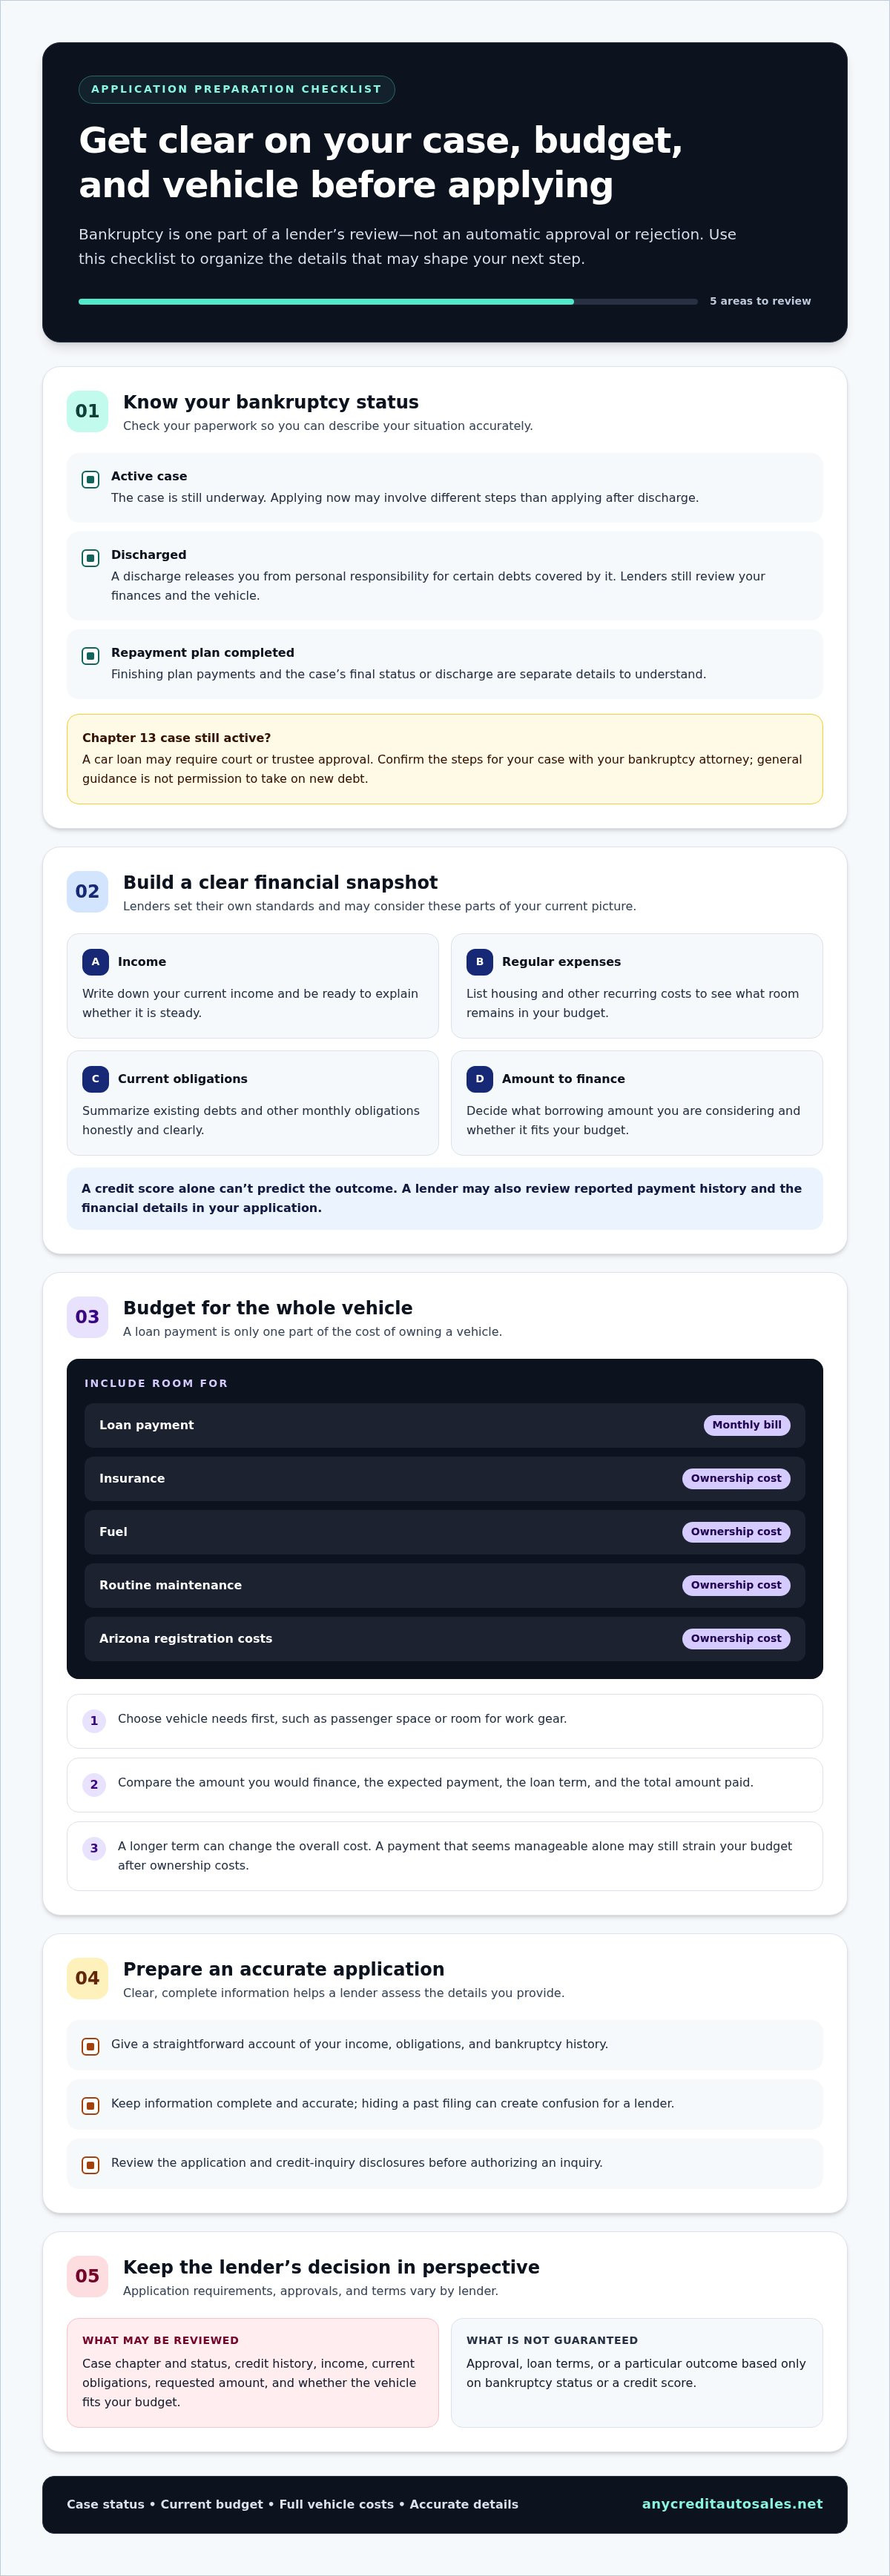
A little preparation can make the application process feel clearer. Before comparing vehicles, get a handle on your case status, transportation needs, and the full amount you can comfortably spend. These steps won’t guarantee approval, but they can help you share accurate information and compare options with less guesswork.
Gather information and set a comfortable budget
Start with the details that shape your decision. If your bankruptcy case is active, get case-specific guidance from your attorney before taking on new debt. Then plan around your household budget, not just a possible loan payment. One useful check is to subtract regular household obligations and estimated vehicle ownership costs from your income before settling on a payment limit.
- Confirm your case status. Note whether your case is active, discharged, or has a completed repayment plan. Keep relevant paperwork handy so you can answer application questions accurately.
- Set a transportation budget. Decide what monthly amount feels manageable after housing, food, utilities, and other obligations. Leave room for costs beyond the loan payment.
- Write down your vehicle needs. Consider your regular trips, passengers, and any space needed for work or family responsibilities. Choose a practical vehicle type before browsing.
- Gather common application details. You may need identification, current income information, and housing expenses. Lender requirements vary, so be ready to provide other details if requested.
- Review your information. Check names, addresses, income figures, and monthly expenses for accuracy before submitting anything. Complete, consistent answers make your current financial picture easier to understand.
Use this quick worksheet to keep the numbers and priorities together:
- Everyday vehicle needs: __________________________________
- Comfortable monthly payment limit: ________________________
- Room for insurance, fuel, maintenance, and registration: __________
- Borrowing amount that fits your budget: ____________________
Include insurance, fuel, maintenance, and Arizona registration in your ownership plan. If these costs leave little room for a loan payment, adjust your vehicle or borrowing target before you apply. That’s a practical way to keep dependable transportation in view without feeling pushed to buy quickly.
Understand the application before submitting it
Read each question and answer it fully. An application may ask about income, housing, existing obligations, and the vehicle or loan you’re seeking. Don’t guess or leave out a bankruptcy filing if asked. If a question is unclear, pause and get an explanation before submitting your information.
Review the lender’s disclosures, including how the financing inquiry is handled and whether it may involve a credit inquiry. If you’re comparing a car loan after bankruptcy Arizona, understanding the application and inquiry process can help you make a more deliberate choice. Once you’re ready to explore vehicles that match your needs, explore pre-owned vehicles and consider your options at a comfortable pace.
Explore Car Loan Options After Bankruptcy with a Chandler Dealership
Finding transportation after bankruptcy can feel like a lot to sort through. Any Credit Auto Sales LLC is a used-car dealership in Chandler serving shoppers in nearby communities including Mesa, Tempe, Phoenix, Queen Creek, and San Tan. You can browse pre-owned vehicles, consider what fits your transportation needs, and, when you’re ready, submit a financing application to third-party lenders.
This path connects your vehicle search with an application process, but it doesn’t promise approval. Outside lenders review the application, make the financing decision, and set any terms. The dealership doesn’t provide in-house or buy-here-pay-here financing. Keep your budget and case status in mind as you explore a possible car loan after bankruptcy Arizona.
What to expect from the dealership’s financing process
Start by looking at available pre-owned vehicles and narrowing your choices to options that match your day-to-day needs and comfortable budget. Think about practical criteria such as passenger space, cargo room, and the kind of trips you regularly make. If you choose to proceed, you can submit a financing application for review by outside lending partners.
Any Credit Auto Sales LLC helps shoppers navigate the application process, but only the lender can decide whether to approve it and what terms may apply. There’s no guaranteed outcome. If you have questions about application details or credit inquiry disclosures, review the information before you submit. For legal questions about an active bankruptcy case, speak with your bankruptcy attorney.
Credit histories vary, and credit help is available as you consider your next step. Keep expectations grounded: no dealership conversation can promise a credit-score change or a particular lending result. The goal is to understand the process and explore a vehicle choice that makes sense for your situation.
Take a manageable next step in the East Valley
If you’re in Chandler, Mesa, Tempe, Phoenix, Queen Creek, or San Tan, begin at a pace that feels right for you. Revisit your transportation budget, including insurance, fuel, maintenance, and registration. Then compare vehicles based on how you’ll use them, not pressure to choose quickly. A clear borrowing target can help keep the search focused.
- Browse available pre-owned vehicles and note options that meet your practical needs.
- Discuss your transportation priorities and budget as you consider a vehicle.
- Review the application details and lender disclosures before submitting a financing application.
You don’t need to have every answer before you start exploring. Take one manageable step, gather the information you need, and decide whether an application makes sense for your circumstances.
Browse vehicles and start your financing application
Take Your Next Step at Your Own Pace
You don’t have to solve everything at once. Start by deciding what reliable transportation would make easier in your daily life, then choose one manageable step toward it. A thoughtful pace gives you room to make a choice that fits your needs rather than one driven by pressure.
If you’re considering a car loan after bankruptcy Arizona, remember that your financial history is only part of your story. Be honest about where things stand today, and give yourself time to plan. Any Credit Auto Sales is BBB accredited since April 2017, and you can explore vehicles and financing options without treating an application as a promise of approval.
When you feel ready, take a look at available pre-owned vehicles and decide whether you’d like to begin an application. Browse pre-owned vehicles and start your financing application. One practical step at a time can move you closer to transportation that fits your life.
Frequently Asked Questions
Can I get a car loan after bankruptcy in Arizona?
If you’re researching “car loan after bankruptcy Arizona,” financing may be possible, but approval depends on lender criteria, your case status, income, existing obligations, and the vehicle and amount requested. No dealer or article can promise approval. For example, steady income doesn’t erase a lender’s review of other monthly debt. If your bankruptcy case is active, get guidance from a qualified bankruptcy attorney before taking on new debt.
How soon after Chapter 7 bankruptcy can I apply for a car loan?
There isn’t one waiting period that applies to every Chapter 7 borrower. Whether you’ve received a discharge, the lender’s own rules, and your current finances can all matter. A lender’s willingness to review an application is separate from any restrictions tied to your case. Ask a qualified bankruptcy attorney about your circumstances, then set a vehicle budget that includes ownership costs before deciding when to apply.
Can I finance a car during Chapter 13 bankruptcy in Arizona?
Possibly, but an active Chapter 13 case may involve restrictions or approval steps specific to your situation. Don’t assume that applying is automatically allowed or prohibited. Before submitting an application or agreeing to new debt, discuss the proposed purchase with your bankruptcy attorney or trustee as appropriate. Be ready to explain why you need transportation and how the expected payment fits your household budget.
Does a bankruptcy discharge guarantee auto-loan approval?
No. A discharge isn’t a loan approval, and lenders use their own criteria. They may assess your current income, obligations, credit history, requested amount, and vehicle. If you receive an offer, look beyond whether you were accepted. Read the payment schedule and full loan terms, and consider whether the obligation remains manageable alongside your regular expenses. Compare disclosed terms carefully before deciding to proceed.
Will applying for a car loan after bankruptcy affect my credit?
An application may involve a credit inquiry, depending on the lender’s process, and a new loan adds a payment obligation. The effect of an inquiry can depend on the details, so review the lender’s disclosures before authorizing an application. Don’t count on a car loan to rebuild your credit. First decide whether the payment fits your budget, and make a plan to keep any new payments current.
What documents should I prepare for an auto-loan application after bankruptcy?
Have identification and current information about your income, housing costs, and regular expenses ready. The lender may request other details, and document needs vary by application. Accurate information helps prevent avoidable delays caused by missing or mismatched details. Keep relevant bankruptcy case information available in case it’s requested, but direct questions about your case or legal obligations to your bankruptcy professional.
Can a dealership arrange financing after bankruptcy without offering in-house loans?
Yes. A dealership can help submit an application to outside lending partners without making the loan itself. Any Credit Auto Sales LLC connects shoppers with third-party lenders through its auto financing application process. The outside lender decides whether to approve the application and sets any terms. Financing isn’t guaranteed. Before submitting, review the application and lender disclosures so you understand the inquiry process and potential payment obligations.


