
What if having no credit history is a starting point, not an automatic dead end? If you’re looking for a car loan with no credit history Arizona lenders may consider more than a credit score, so a thin credit file doesn’t automatically mean rejection. Preparation can help you understand your options and decide what fits your budget.
It’s normal to feel unsure about how a lender will assess your application, especially when you need dependable transportation and want to keep payments manageable. No credit history is different from a history of missed payments. Lenders may review details such as income, employment, a down payment, and whether you have a cosigner.
This guide explains what to gather before applying, how to compare a vehicle and loan offer, and what to consider beyond the monthly payment. At Any Credit Auto Sales LLC in Chandler, you can browse used vehicles, get credit guidance, and submit an application to connect with third-party lending partners. These steps can help you make an informed decision, though approval and loan terms are not guaranteed.
Key Takeaways
- No credit history isn’t the same as a record of missed payments. A thin credit file gives a lender less borrowing history to review.
- For a car loan with no credit history Arizona lenders may consider details beyond your credit file, but each lender sets its own criteria.
- Build a budget that accounts for insurance, fuel, registration, upkeep, and an emergency cushion, not just the monthly payment.
- Gather identification, income and residence details, and vehicle preferences before you apply.
- Any Credit Auto Sales LLC helps Chandler shoppers submit applications to outside lending partners and offers credit guidance as they explore their options.
Car Loan With No Credit History in Arizona: What It Means for a First-Time Buyer
No credit history means your credit file contains little or no record of borrowing and repaying money. It isn’t automatically a record of missed payments. That distinction matters when you’re considering a first auto loan.
If you’re searching for a car loan with no credit history Arizona, limited credit activity may feel like a closed door. A more useful way to think about it is that the lender has less payment history to review. That’s only one part of your application and doesn’t tell the whole story about your ability to manage a loan.
Auto financing can involve different loan types and lender assessments. The general overview of car finance can help explain the basics, but each lender sets its own criteria for reviewing an application. No guide can predict an individual decision. Start by understanding what your credit file does, and doesn’t, show.
A first auto loan may be worth exploring if you need transportation and can approach the decision at a comfortable pace. You don’t need to rush into a purchase just because you’re ready to drive. Learning how lenders distinguish a limited file from a pattern of payment problems can help you set realistic expectations and choose your next step.
Why a thin credit file is different from bad credit
A thin file contains limited borrowing history for a lender to assess. Negative credit history, by contrast, may include records of missed or late payments. These situations aren’t the same, though lenders may interpret credit information differently. With little history, a lender has fewer examples of how you’ve handled debt. That uncertainty doesn’t prove you’ve made late payments, and it doesn’t guarantee approval or denial.
If you’ve never used credit or have only a small amount of credit activity, keep that distinction in mind. Your file reflects information reported about your borrowing, not your character or your potential as a responsible buyer. Since lender requirements and decisions vary, don’t assume a thin file will lead to one particular outcome.
Who may be looking for a first auto loan in Arizona?
You might be a student buying your first car, starting a new job, or a recent Arizona resident whose borrowing history hasn’t followed you into a local application. You may also have relied on cash or a debit card for everyday expenses and simply haven’t needed to borrow before. Each situation can leave you with little credit history, even when your need for transportation is clear.
If you commute to work, travel to classes, or handle family responsibilities, a dependable vehicle can make daily routines easier. Shoppers in Chandler and nearby East Valley communities may be weighing that need against the cost and responsibility of a loan. Make time to compare vehicles, understand your budget, and explore an application when you feel prepared. A first loan is an option to consider, not a reason to buy before you’re ready.
How Auto Lenders May Review a Car Loan Application With No Credit
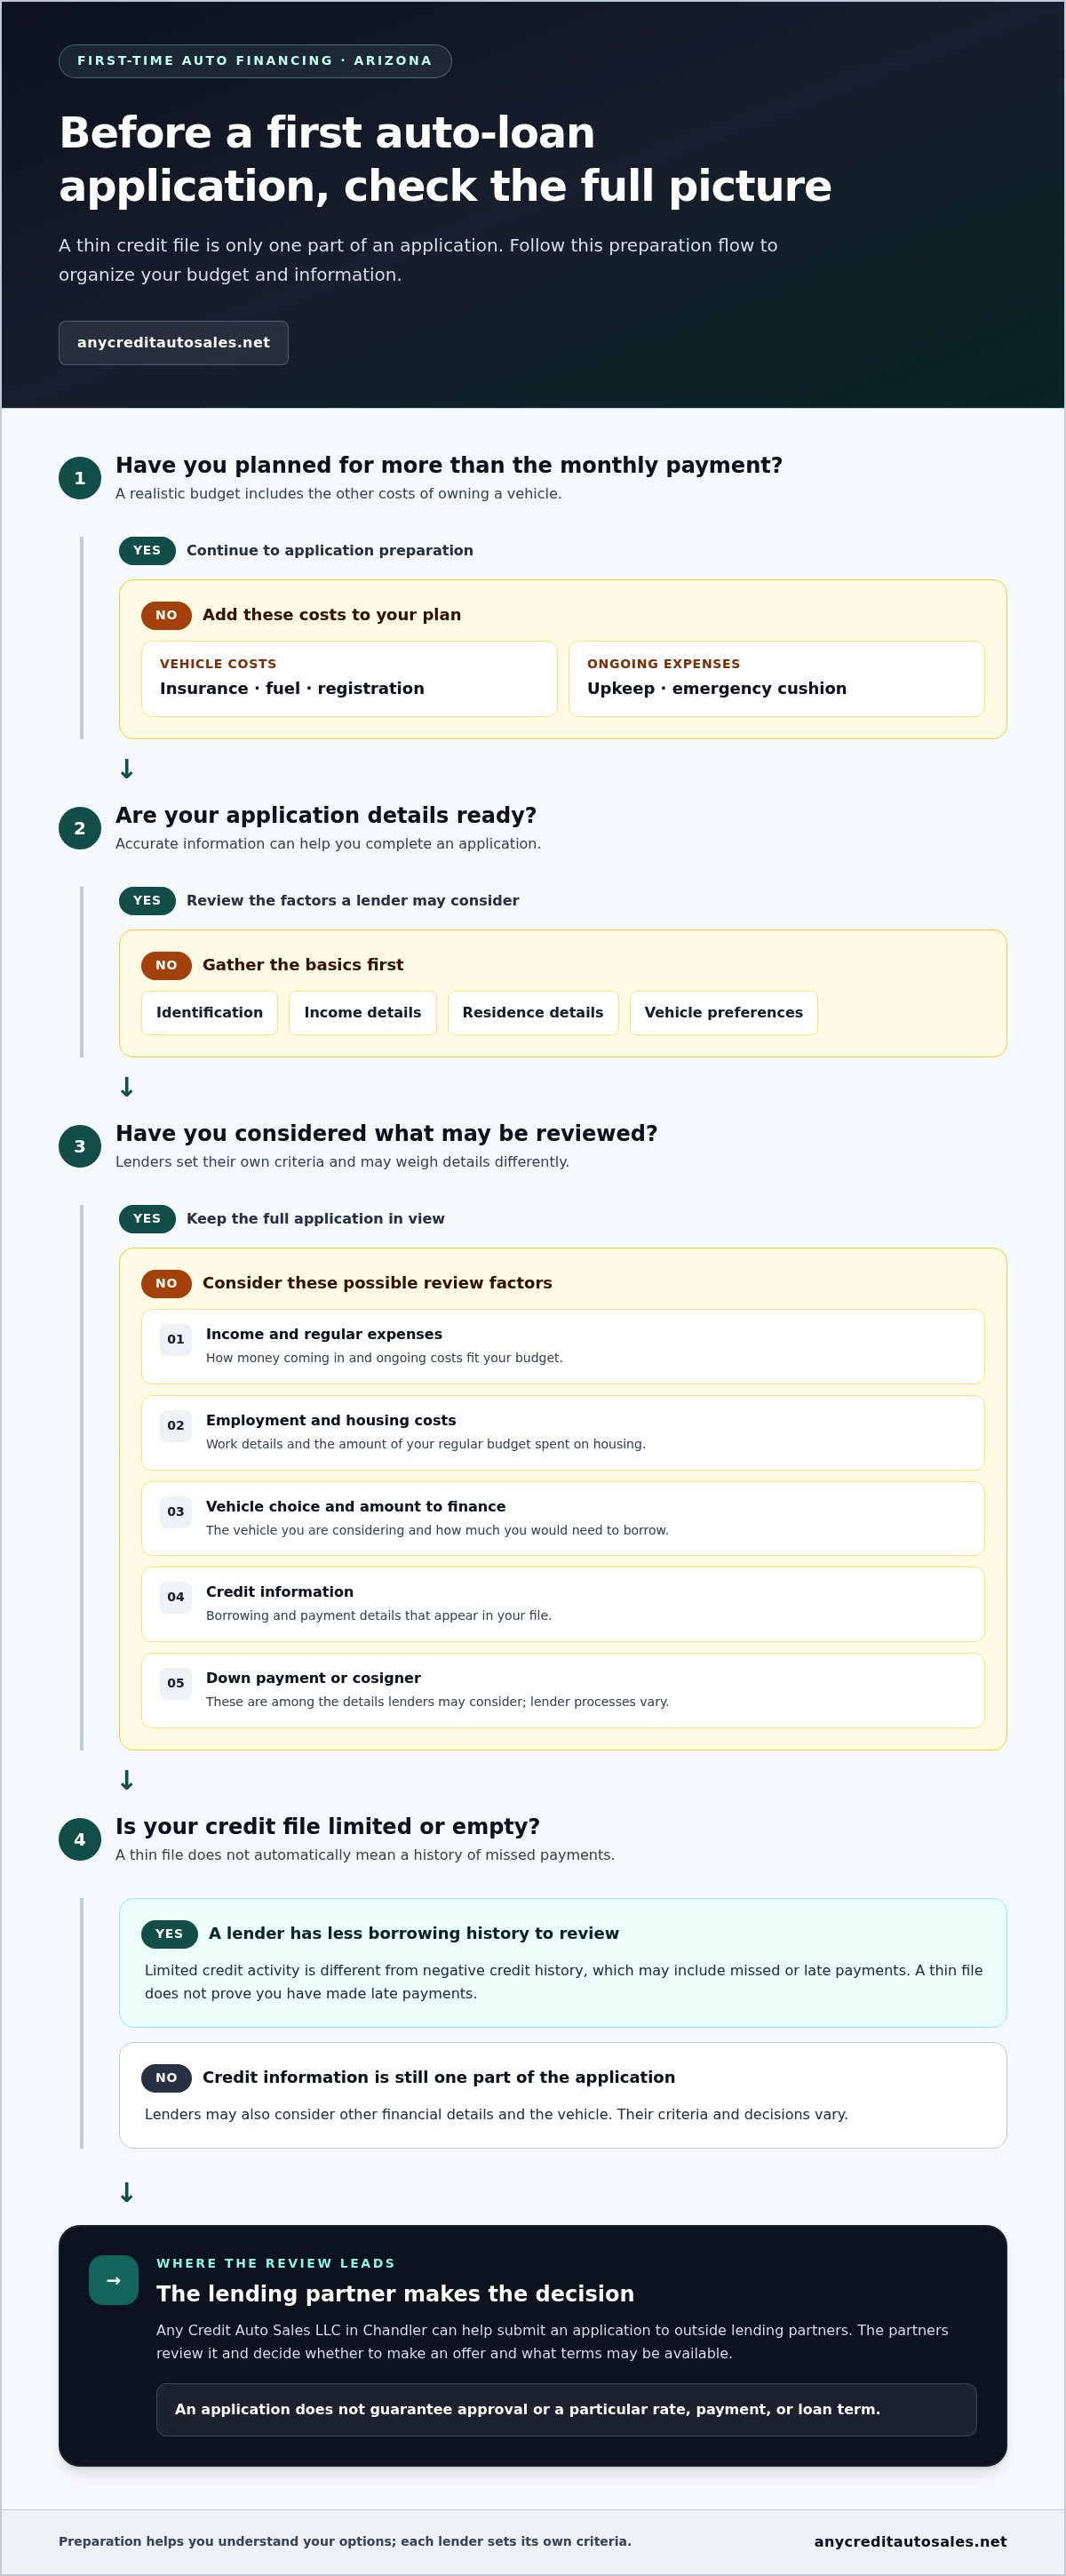
A credit file is one part of an application. When borrowing history is limited, a lender may consider other details about your finances and the vehicle you’re considering. The review depends on the lender, so treat the following as possible factors, not a checklist every applicant must meet.
What information may help show your ability to repay?
Income and regular expenses can help a lender assess how a potential payment fits your budget. Employment details may provide additional context, while housing costs show what you already spend each month. A lender may also review your credit information and the vehicle included in your application.
Depending on its process, a lender may request supporting details. Having clear information about your income, work, and housing costs can make it easier to complete an application accurately. There isn’t one income amount or work history that guarantees approval. Each lender sets its own criteria and makes its own decision.
As you prepare, consider these areas a lender may review:
- Income: What money comes in, and how regularly?
- Employment: What work details does the application ask you to provide?
- Housing costs: How much of your regular budget goes toward housing?
- Vehicle choice: What vehicle are you considering, and how much would you need to finance?
- Credit information: What borrowing and payment details appear in your file?
These details offer a general picture, not a promise of a particular outcome. A lender may weigh them differently or ask for other information. For a car loan with no credit history Arizona shoppers can start by preparing accurate details and choosing a vehicle that fits their budget.
What happens when a dealership submits your application?
You complete an auto financing application with information about yourself and the vehicle you’re considering. At Any Credit Auto Sales LLC in Chandler, the dealership helps submit applications to outside lending partners. The dealership guides you through that connection but isn’t the lender.
The lending partners review the application and decide whether to make an offer. They determine any available terms. Submitting an application doesn’t guarantee approval or a particular rate, payment, or loan term.
Keep your expectations grounded as you take the next step. You can explore the financing application through Any Credit Auto Sales LLC and get credit guidance as you consider your options. Compare any offer with your full budget before deciding whether it feels manageable.
How to Set a Realistic Budget Before Choosing a First Car Loan
A payment can look manageable on its own and still leave too little for other expenses. Start with your take-home income and recurring bills, then work out what you could comfortably spend on transportation. Don’t begin with the largest loan amount you might be offered. A practical budget helps you choose a vehicle without squeezing out groceries, savings, or other regular needs.
Include more than the loan payment. Ownership and operating costs can include insurance, fuel, registration, and routine upkeep. Set aside an emergency cushion for unexpected expenses, too. Costs vary by vehicle and personal circumstances, so use your own quotes and spending patterns rather than relying on a generic estimate.
How do you choose a payment that fits your monthly life?
List your take-home income, regular bills, and savings goals first. Then calculate the transportation budget you can manage, including the loan payment and the costs of using and maintaining the vehicle. Leave room for expenses that can change from month to month. If a payment only works when everything goes perfectly, it may be too high for comfort.
How should you compare loan terms and vehicle choices?
Look beyond the monthly payment. APR is the yearly cost of borrowing expressed as a percentage. The loan term is how long you have to repay. The total amount repaid is the sum of payments over the loan, including interest. A longer term may lower each payment but can increase the total interest paid. Compare vehicles based on practical needs, condition, and overall ownership costs, not the payment alone.
Use this table to compare actual offers. Enter the figures shown in each offer rather than guessing. For a plain-language explanation of loan details, review Understanding Auto Loan Terms Before You Sign.
| Compare | Offer A | Offer B |
|---|---|---|
| APR | Enter the stated APR | Enter the stated APR |
| Loan term | Enter the repayment length | Enter the repayment length |
| Monthly payment | Enter the quoted payment | Enter the quoted payment |
| Total amount repaid | Enter the full amount | Enter the full amount |
Check that each vehicle meets the same practical needs, such as commuting, passenger space, and everyday use. Include expected insurance, fuel, registration, and upkeep in your comparison. If you’re researching “car loan with no credit history Arizona,” weigh each offer against your actual budget, not just the payment that looks easiest today.
How to Prepare for a No-Credit Auto Loan Application in Arizona
Preparation can make the application process easier to manage. Set your budget, gather useful information, browse vehicles that fit, and then complete an application. This order helps you avoid choosing a vehicle before you know what payment and total ownership costs feel comfortable.
- Set your budget. Account for regular bills and the costs of owning and operating a vehicle, not only the loan payment.
- Gather your information. Have identification, income details, and current residence information nearby.
- Browse suitable vehicles. Narrow your choices by practical needs and the budget you set.
- Apply when ready. Provide accurate information and allow time to review any follow-up or offer.
This approach can help whether you’re in Chandler, Mesa, Tempe, Phoenix, Queen Creek, or San Tan. Your location doesn’t change the lender’s application process, but having your details and vehicle preferences ready can make it easier to complete each step thoughtfully.
What should you gather before starting an application?
Each lender may ask for different details, so there isn’t one document list for every application. It can help to have identification, income information, residence details, and notes about the vehicle you’re considering ready. Depending on the lender’s process, you may be asked for supporting documents. Keep the details you enter consistent with those documents, and review your information before submitting.
A First-Time Car Buyer Checklist: Documents You Need can help you organize the basics. Use it as a preparation aid, not as a guarantee that every lender will request the same paperwork.
What should you do after submitting your application?
After submission, a lender may review your information and request more details. It may also present terms for you to consider. The timing, requested documents, and outcome depend on the lender, so submission alone doesn’t guarantee approval or a particular offer. Stay organized, read any response carefully, and consider what it means for your budget.
Before signing an agreement, read the full terms, including the APR, loan length, payment amount, and total repayment. Ask questions about anything you don’t understand. Make sure you know what you’re agreeing to before moving forward.
Any Credit Auto Sales LLC in Chandler helps shoppers submit applications to outside lending partners and offers credit guidance as they explore their options. If you’re ready for a practical next step, start an auto financing application. The lender makes its own decision, so review any offer carefully and decide whether it fits your plans.
Explore a First Car Loan With Any Credit Auto Sales in Chandler
A first auto loan can feel like a big step, especially when you’re learning how lenders review applications. Any Credit Auto Sales is an independent used-car dealership in Chandler that helps shoppers with varied credit histories explore their options. Browse pre-owned cars, trucks, and SUVs online, then consider an application when you’re ready.
How does the dealership support shoppers with limited credit history?
Any Credit Auto Sales helps you submit an auto financing application to outside lending partners. The team also offers credit help to guide you as you consider your situation and possible next steps. This support can make the process easier to understand, but it doesn’t promise that a lender will approve an application or offer specific terms.
The dealership helps connect your application with lending partners. Those lenders review it, make their own decisions, and set any available loan terms. Knowing who makes the lending decision can help you set clear expectations and take time to consider any offer.
What are practical next steps for Arizona shoppers?
Start with the budget you’ve worked out. Consider the vehicle’s role in your daily routine, the payment you can manage, and the other costs of owning and using it. Then browse inventory with a practical shortlist in mind. Think about how much passenger or cargo space you need, how you expect to use the vehicle, and which choices fit your overall budget.
Shoppers in Chandler, Mesa, Tempe, Phoenix, Queen Creek, and San Tan can browse available pre-owned cars, trucks, and SUVs online before taking the next step. You don’t need to rush just because you’re exploring a car loan with no credit history Arizona. Reviewing your options at your own pace can help you focus on vehicles that fit your needs and budget.
When you’re ready, submit an application to begin the process with outside lending partners. Gather your information, take your time reviewing any lender response, and read the full terms before deciding whether to move forward. Credit guidance can help you understand your options, while the lender remains responsible for its decision and any offer.
When you’re ready to explore vehicles and take the next step, browse pre-owned inventory and start an application with Any Credit Auto Sales.
Take Your Next Step at a Pace That Feels Right
Your first car loan doesn’t need to be figured out all at once. Treat each step as a chance to learn what fits: refine your budget, consider vehicles suited to your daily life, and decide when you’re ready to apply. Looking into a car loan with no credit history Arizona can be a practical start, even if you’re still weighing your options.
Any Credit Auto Sales can help you explore pre-owned vehicles, submit an application to outside lending partners, and get credit guidance as you consider your choices. Each lender makes its own decision, and you control how quickly you move forward. Take the time you need to feel comfortable with your next step.
Browse pre-owned vehicles and start your financing application when you’re ready. Begin with your budget and explore options that work for your needs.
Frequently Asked Questions
Can you get a car loan with no credit history in Arizona?
It may be possible, but having no credit history doesn’t guarantee approval. For a car loan with no credit history Arizona lenders may consider income, expenses, the vehicle, and other application details. Start by identifying the transportation you need and what you can comfortably afford. Shoppers in Chandler, Mesa, Tempe, Phoenix, Queen Creek, and San Tan can submit applications through a dealership to outside lending partners, which make their own decisions.
Does applying for an auto loan hurt your credit?
An auto-loan application may lead to a hard inquiry, which can affect your credit file. The effect varies based on your situation and the scoring model used. Before applying, review the lender’s disclosures so you understand when a credit check may happen. If you’re comparing offers, keep track of the applications you submit and make sure your personal and financial information is accurate.
Can a cosigner help you get a car loan with no credit?
A cosigner may strengthen an application in some situations, but lender rules differ and approval isn’t guaranteed. A cosigner also becomes responsible for the debt if payments aren’t made as agreed. Before applying together, discuss who will make payments, how you’ll handle a missed payment, and what the loan commitment means for both people. Review the proposed terms together before either person signs.
Do rent and utility payments count as credit history for an auto loan?
Rent and utility payments don’t automatically appear in every credit file or count in every lender’s review. Reporting practices and lender methods vary. If you’ve paid these bills consistently, keep records such as statements or payment confirmations organized. They may help explain your financial habits if a lender considers them, but don’t assume they replace traditional credit history or will change a lending decision.
Will making car payments build your credit history?
On-time car payments may help establish a payment record if the lender reports the account to credit bureaus and you meet the loan terms. Reporting practices can differ, so check the loan documents rather than assuming the account will be reported. Set up a reliable reminder or payment routine from the start. Late or missed payments may have consequences, so choose a payment you can manage consistently.
Can you apply for a car loan before choosing a vehicle?
You can often begin an application before choosing a specific vehicle, though each lender’s process may differ. Starting with a clear budget can help you narrow your search to vehicles that fit your needs. Any Credit Auto Sales in Chandler helps shoppers submit applications to third-party lending partners. Those lenders decide whether to make an offer and set its terms. You can explore vehicles and the application process without assuming an offer is guaranteed.


