
Can you buy a used car in Arizona with a small down payment? It may be possible, but paying less upfront does not guarantee financing or make the full loan less important. If you’re searching for a low down payment used car Arizona buyers can afford, compare more than the cash due on purchase day.
Keeping upfront costs manageable matters, especially when you’re also planning for monthly expenses. Your down payment affects how much you borrow, while your credit history, the vehicle, and the lender’s terms also shape the financing picture. At Any Credit Auto Sales LLC in Chandler, you can browse used vehicles and apply for financing through third-party lending partners. Credit help is available to guide you as you consider your choices, without promising a particular approval or loan.
This comparison explains what “low down payment” can mean, how financing options differ, and what to weigh beyond the amount due upfront. You’ll also find practical ways to prepare for shopping and compare offers, so you can make a decision that fits your budget.
Key Takeaways
- A “low” down payment depends on the vehicle, your available funds, and the lender’s review. There is no single amount that fits every shopper.
- Compare the amount due upfront with the total amount financed, including applicable charges and any trade-in value.
- For a low down payment used car Arizona purchase, look beyond the upfront amount to the interest rate, loan term, and repayment terms.
- Before shopping, set a comfortable budget, review available vehicles, gather your information, and account for ongoing ownership expenses.
- Any Credit Auto Sales LLC offers used vehicles, credit help, and an application for financing through third-party lending partners.
What Does a Low Down Payment Mean When Buying a Used Car in Arizona?
A down payment is money you put toward a vehicle at the time of purchase. It reduces the portion of the vehicle price that may need to be financed. “Low down payment” has no fixed definition. What feels manageable depends on the vehicle you choose, the funds you have available, and the lender’s review of your application.
That’s why the phrase low down payment used car Arizona can describe different situations for different shoppers. The amount you can put down is separate from whether a lender approves the loan. A smaller amount does not automatically rule out financing, and a larger one does not guarantee approval. Treat the down payment as one part of the decision: the vehicle, amount borrowed, and repayment terms matter too.
How a Down Payment Changes the Amount You Finance
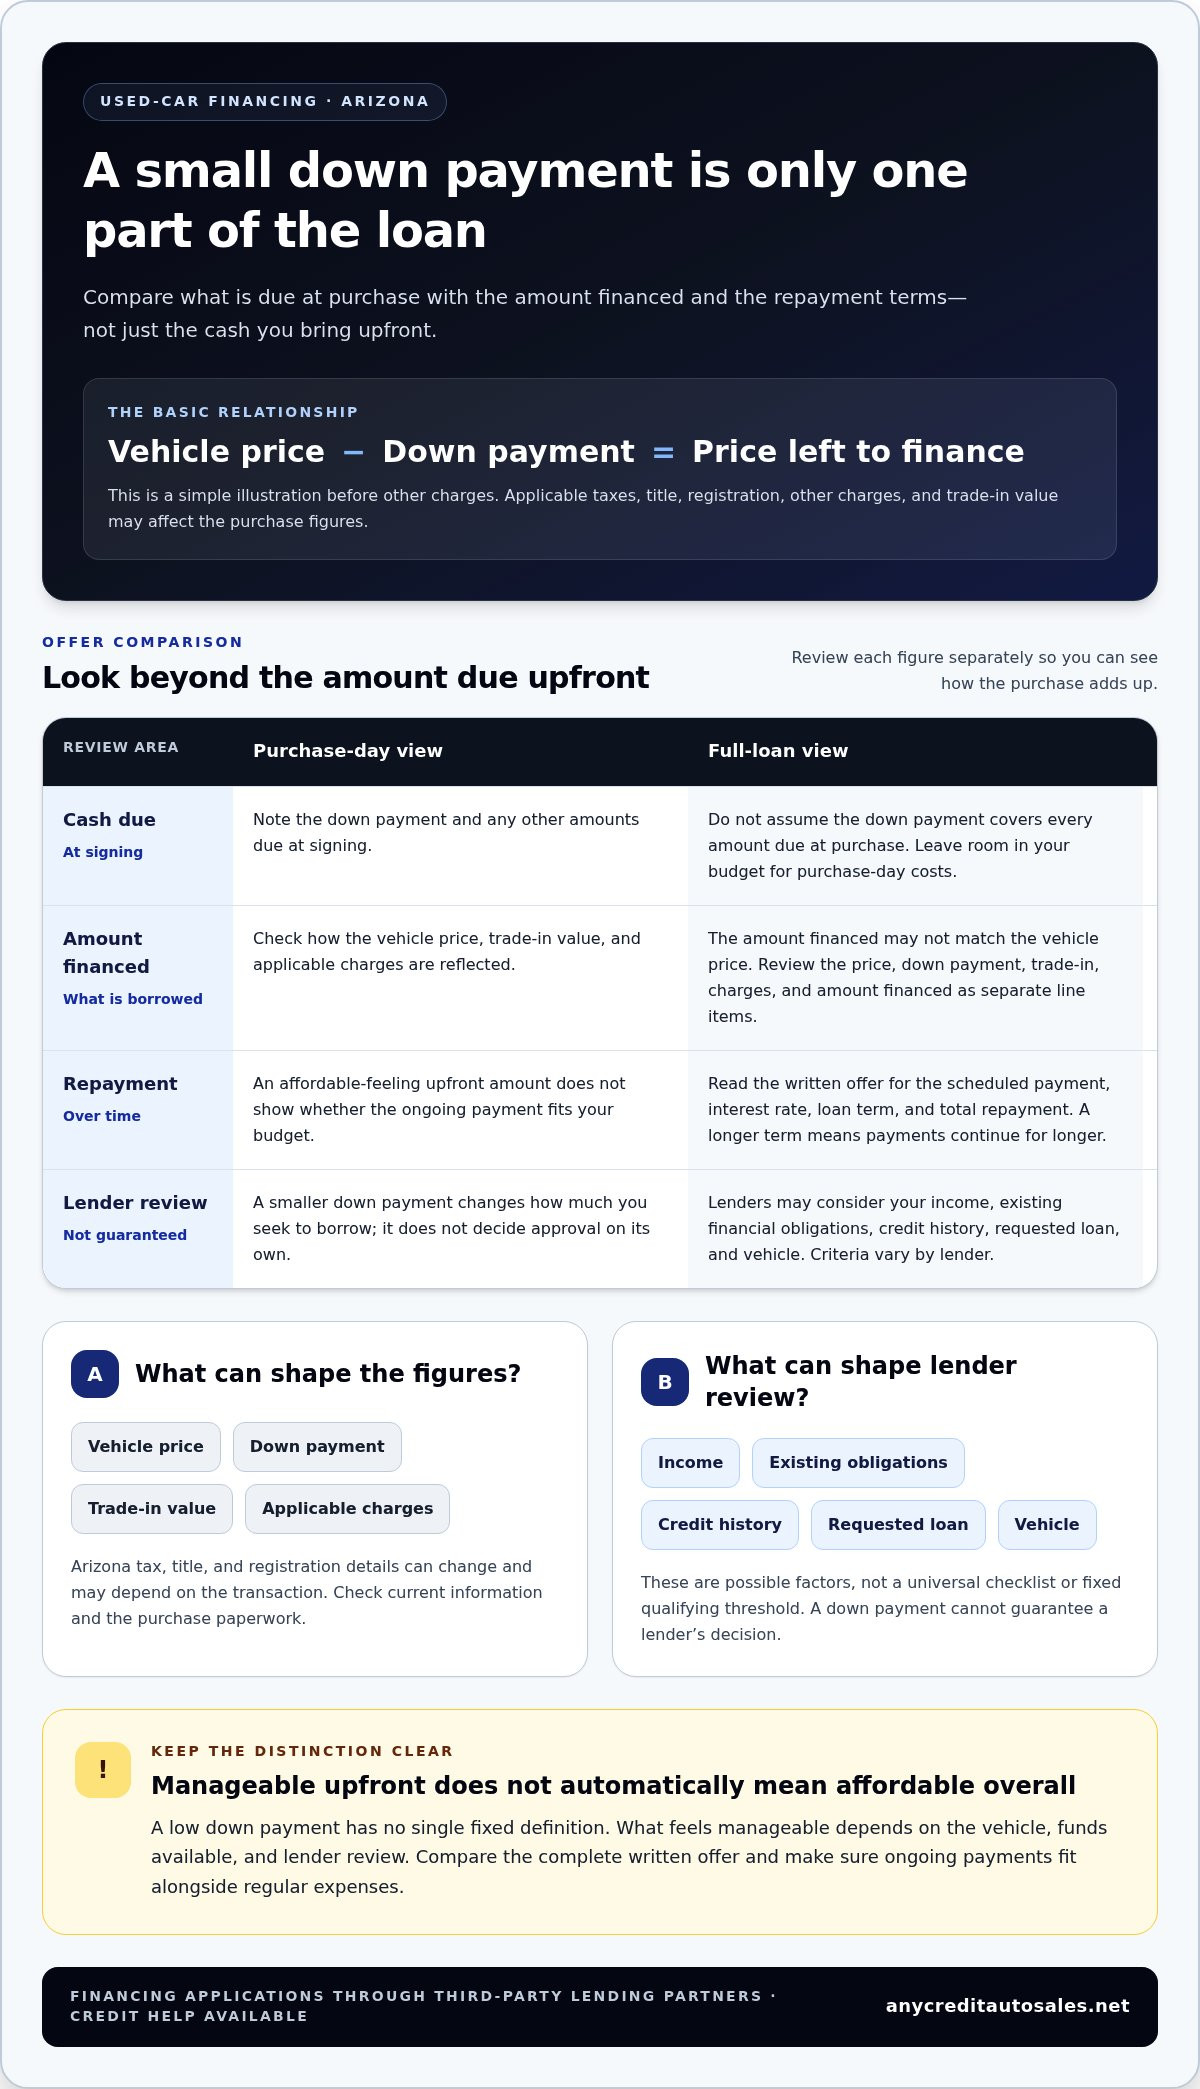
In general, paying more upfront leaves less of the vehicle price to finance. For a simple example, if the vehicle price is represented by P and your down payment by D, the portion of the price left before other charges is P − D. This is a basic illustration, not a loan quote. Understanding the wider picture of car finance can help you distinguish money paid upfront from the loan itself.
The amount financed may not match the vehicle price. Applicable taxes, title, registration, or other charges can affect the total funds needed or the amount included in a loan. A trade-in may also change the figures. Review the vehicle price, down payment, trade-in value, charges, and amount financed as separate line items to see how the purchase adds up.
Arizona tax, title, and registration details can change and may depend on the transaction. Review current information and the purchase paperwork when setting your budget. Do not assume the down payment covers every amount due at purchase.
Why a Small Upfront Amount Does Not Guarantee Approval
A lender reviews the application and relevant financial information to decide whether to offer financing and what terms may apply. The vehicle you select and the overall loan request also matter. A down payment can affect how much you seek to borrow, but it cannot determine the lender’s decision on its own.
A down payment is one factor in a financing decision, not a promise of approval. That is true whether you apply with a smaller amount or bring more money upfront. At Any Credit Auto Sales LLC, shoppers can apply through third-party lending partners, and credit help is available to guide them through financing choices. No particular approval or loan terms are promised.
Before you shop, choose an upfront amount that leaves room for purchase-day costs and regular expenses. Then compare the full loan picture, not just the amount due upfront. A clear breakdown helps you judge whether the vehicle and financing terms fit your budget.
How a Down Payment Can Affect a Used-Car Loan
Your down payment is only one part of the loan picture. The vehicle price, any trade-in value, and applicable charges can all affect how much you need to finance. A smaller amount paid upfront may leave a larger balance to borrow. A trade-in may reduce the amount you need to cover, depending on how it is applied. Review each figure separately so you can understand how the purchase adds up.
The loan’s interest rate and term shape repayment over time. The rate affects the cost of borrowing, while the term determines how long scheduled payments continue. A longer term may spread repayment out, but it also means payments continue for longer. Compare the written offer, not only an estimated payment or the cash due at signing.
What Else Can Shape a Lender’s Decision?
A lender may consider your income, existing financial obligations, credit history, requested loan, and the vehicle. These are possible factors, not a universal checklist or a fixed qualifying threshold. Each lender sets its own criteria and reviews the details of an individual application. A down payment can change the amount requested, but it cannot replace that review or guarantee a decision.
How to Compare Upfront Cash With the Full Loan
Review the money due at signing alongside the amount financed and scheduled payments. Then read the written terms for the interest rate, loan term, and total repayment. If a figure is unclear, get an explanation before deciding. This lets you compare the full commitment instead of choosing based only on what feels manageable on purchase day.
Use this quick comparison when reviewing an offer:
- Due upfront: Note the down payment and any other amounts due at signing.
- Amount financed: Review how the price, charges, and trade-in are reflected.
- Repayment: Check the scheduled payment, interest rate, term, and total repayment shown in writing.
A comfortable upfront amount is not the same as an affordable loan overall. Make sure the ongoing payment fits your budget alongside regular expenses, and consider how long you’ll be making payments. If you’re exploring a low down payment used car Arizona option, compare the complete written offer before settling on a vehicle or loan.
Any Credit Auto Sales LLC accepts financing applications through third-party lending partners and provides credit help as you consider financing choices. You can browse available used vehicles and submit an application as part of your shopping process.
Low Down Payment Financing Options: What Arizona Shoppers Should Compare
Financing terms can differ between lenders and offers, so compare the details rather than assuming a small down payment means the same thing in every situation. One useful distinction is who provides the loan. A dealership may help submit an application to outside lenders, while a buy-here-pay-here arrangement generally means the dealership itself provides financing. These are different structures, and the terms are not automatically alike.
Third-Party Financing Versus Buy-Here-Pay-Here
With third-party financing, an outside financial institution reviews the application and may provide the loan. Financing arranged through a dealership can use an outside lender, so “arranged through a dealership” does not necessarily mean the dealership is the lender. Any Credit Auto Sales works with third-party lending partners and does not offer in-house or buy-here-pay-here financing.
For a useful comparison, identify the lender named in each written offer and review the specific terms. A financing structure alone does not tell you whether an offer fits your budget. The lender’s review and the application and vehicle details can affect what is offered. Approval, down payment, rate, and term are not guaranteed.
Compare the Whole Offer, Not Just the Down Payment
Set the offers side by side and record the same details for each one. Note any information that is missing from the written offer. This makes it easier to see whether a lower upfront amount comes with a larger balance or a different repayment schedule.
Comparison item | Offer A | Offer B
Lender | Name of the lender | Name of the lender
Amount due upfront | Down payment and other amounts due at signing | Down payment and other amounts due at signing
Amount financed | Amount shown in the offer | Amount shown in the offer
Term | Length of repayment | Length of repayment
Rate | Interest rate shown in writing | Interest rate shown in writing
Total repayment | Total shown in the offer | Total shown in the offer
Compare the figures as a set. A lower amount due upfront may leave more to finance, while the rate and term affect repayment. Do not assume two offers are equal just because the monthly payments look close. Review the full written terms, including the repayment schedule, before deciding. For more background, Your Complete Guide to Auto Financing in Chandler can help you build your understanding of loan choices.
If you’re considering a low down payment used car Arizona purchase, Any Credit Auto Sales offers an auto financing application through third-party lending partners, along with credit help for shoppers with varied credit histories. You can browse available used vehicles as you compare your options.
How to Prepare for a Used-Car Purchase With a Smaller Down Payment
Preparation can make shopping more manageable. Set your budget before choosing a vehicle, keep useful application details close, and compare written terms before deciding. This helps you look beyond the amount due upfront and avoid rushing into a loan that does not suit your finances.
Set a Realistic Budget Before Choosing a Vehicle
Start with an upfront amount you can afford without using money needed for other priorities. Then account for regular ownership costs, such as insurance, fuel or charging, and maintenance. There is no single down-payment amount or monthly-payment target that works for everyone. Base your budget on your income, expenses, and comfort level.
Use this order to get ready:
- Set your budget. Decide what you can put down and which ongoing expenses you need to leave room for.
- Review available vehicles. Browse cars, trucks, and SUVs, then focus on options that suit your needs and budget.
- Gather your information. Have identification, income details, and residence information ready as examples of details that may be useful for an application.
- Apply for financing. Provide accurate information. Lender requirements vary, and an application may call for additional details.
- Compare written terms. Review the amount due upfront, amount financed, rate, term, scheduled payments, and total repayment before choosing.
Gather Information and Compare Your Financing Choices
Being organized can help you complete an application carefully. Identification, income details, and residence information are common examples to prepare, not a guaranteed list of lender requirements. If you’re buying your first vehicle, the First-Time Car Buyer Checklist: Documents You Need can help you think through what to gather. Keep your answers accurate, and review each written offer instead of relying on an informal estimate.
As you compare, look at the full repayment picture, not just whether the upfront amount feels manageable. Lenders may review applications differently, and the terms offered can vary. A smaller down payment does not promise approval or a particular rate or term. If you want to learn more about credit before applying, focus on understanding your own credit information and how it may be considered. Do not assume one score guarantees a particular result.
For a low down payment used car Arizona purchase, Any Credit Auto Sales offers an auto financing application through third-party lending partners, along with credit help for shoppers with varied credit histories. Browse used vehicles and apply for financing as you prepare for your purchase.
Explore Used Cars and Financing Help at Any Credit Auto Sales
Buying a vehicle is a significant decision, and you can work through it step by step. Any Credit Auto Sales is a used-car dealership in Chandler. Shoppers in Chandler, Mesa, Tempe, Phoenix, Queen Creek, and San Tan can start by reviewing the online inventory and considering which vehicles suit their daily needs and budget. If you’re weighing a low down payment used car Arizona purchase, keep both the vehicle and the complete financing picture in view.
Browse Pre-Owned Cars, Trucks, and SUVs
Explore available cars, trucks, and SUVs online. Think about how you’ll use the vehicle day to day. Your usual trips, passenger needs, and cargo requirements can help narrow your choices. Keep your budget in mind as you browse, including the cash you can comfortably put down and the ongoing costs of ownership. Use the current listings to guide your search.
A practical way to compare vehicles is to write down what matters most to you, such as body style, passenger space, or suitability for your regular drive. Then review the available options against those priorities. A vehicle that fits your routine and budget is a stronger starting point than one chosen only because the upfront amount seems manageable.
Start a Financing Conversation Without Pressure
When you’re ready, submit an auto financing application. Any Credit Auto Sales works with third-party lending partners, not in-house or buy-here-pay-here financing. The application connects you with outside financial institutions for review. Each lender decides whether to offer financing and what terms may apply. Approval, down payment, rate, and loan terms are not guaranteed.
Credit help is also available for shoppers with varied credit histories. It can guide you as you consider financing choices, but it is not a promise of a particular loan or approval. Read any written offer carefully and make sure you understand the amount due upfront, amount financed, repayment schedule, and other terms before deciding. Take the time you need to compare the full commitment with your budget.
Start with the part that feels easiest. Browse the current inventory, identify vehicles that suit your needs, and submit an application when you’re ready to explore financing through third-party lenders. Browse vehicles and take the next step with Any Credit Auto Sales.
Take Your Next Step With a Clear Plan
Your next move does not need to be a commitment. Start by browsing vehicles that suit your daily needs, then decide whether you’re ready to submit an application. Taking a thoughtful approach gives you room to review your choices and consider how a purchase fits your budget.
If you’re still exploring a low down payment used car Arizona purchase, Any Credit Auto Sales in Chandler offers used vehicles, financing applications through third-party lending partners, and credit help for shoppers with varied credit histories. Focus on understanding your options and the full loan terms before making a decision.
Choose a vehicle that feels practical for your life, and take the financing step when you’re ready. Browse used vehicles and start your financing application with Any Credit Auto Sales.
Move forward one step at a time, with a clear picture of what works for you.
Frequently Asked Questions
Can I buy a used car in Arizona with a low down payment?
It may be possible, but a low upfront amount does not guarantee that a lender will approve a loan. If you’re looking for a low down payment used car Arizona option, start by choosing a vehicle that fits your budget and submitting an application for lender review. Consider whether you can manage both the amount due at purchase and the ongoing costs of owning the vehicle. Approval and terms depend on the lender’s decision.
How much should I put down on a used car?
Choose an amount you can pay without leaving yourself short for essential expenses. There is no down-payment amount that suits every buyer or vehicle. Before settling on a figure, consider your available savings, possible purchase-day charges, and the payment obligations you can manage afterward. Avoid borrowing money for a down payment without considering how that added obligation would affect your budget.
Does a bigger down payment improve my chance of getting approved?
A larger down payment may reduce the amount you’re asking to finance, but it cannot guarantee approval. Lenders make their own decisions after reviewing the application and the vehicle being financed. If you have savings available, consider how much you can put down while keeping a cushion for everyday needs. Review the complete written offer so you understand the lender’s decision and terms rather than assuming the down payment decides everything.
Can I get a used-car loan in Arizona with challenged credit and little money down?
It may be possible, but approval cannot be assumed based only on credit history or down payment. Any Credit Auto Sales provides credit help and accepts financing applications for review by third-party lenders. Shoppers in Chandler, Mesa, Tempe, Phoenix, Queen Creek, and San Tan can explore vehicles and apply. Provide accurate information and review any offer carefully before deciding whether it works for you.
Is third-party financing the same as buy-here-pay-here financing?
No. With third-party financing, an outside financial institution reviews the application and may provide the loan. Buy-here-pay-here generally refers to financing provided by the dealership itself. Any Credit Auto Sales works with third-party lending partners and does not offer in-house or buy-here-pay-here financing. The lender named in the paperwork shows who provides the loan and sets its terms.
What should I compare besides the down payment?
Compare the amount due at signing, amount financed, interest rate, loan term, scheduled payment, and total repayment shown in each written offer. Check that you’re comparing offers for the same vehicle and purchase details. A payment that looks manageable by itself may not show how long repayment lasts or the total paid over time. Review each figure before agreeing to financing.
What information should I prepare before applying for used-car financing?
Have identification, income details, and residence information available as examples of details that may help you complete an application. These are not guaranteed lender requirements, and a lender may request other information. Check that names, addresses, and income details are accurate before submitting. If a question is unclear, read it carefully rather than guessing. Keeping your information consistent can make it easier to review your application and respond to follow-up requests.


