
A low credit score doesn’t tell the whole story of your car financing options. If you’re searching for a low credit score car dealership Arizona shoppers can approach with confidence, know that one number doesn’t automatically rule out a loan. It can affect the options available, so it’s reasonable to want clear answers before you apply.
Financing decisions depend on your full application, and a dealership can’t promise approval or a particular rate. At Any Credit Auto Sales LLC in Chandler, applicants can connect with outside lenders and get credit guidance to help them understand the process. Take time to review your options and decide what fits your needs.
This article explains how dealership-assisted financing works, what to compare in a lender’s offer, and how to keep a vehicle and loan within a practical budget. You’ll also find a next step for exploring used vehicles and financing in Chandler, Mesa, Tempe, Phoenix, Queen Creek, and San Tan Valley.
Key Takeaways
- A low credit score car dealership Arizona shoppers visit can help explore financing paths, but a lender considers your full application, not just one number.
- Dealership staff can guide you through an application reviewed by outside lenders, from discussing your needs to reviewing available terms.
- Third-party financing, direct loans, and buy-here-pay-here financing differ in who reviews your application and provides the funds.
- Set a comfortable vehicle budget, then compare written loan terms beyond the monthly payment before making a decision.
- Browse pre-owned vehicles and start an application with Any Credit Auto Sales in Chandler to take a practical next step.
Low credit score car dealerships in Arizona: what help can they provide?
A low credit score can make car shopping feel uncertain. You may wonder whether applying is worthwhile or worry that your score will define the conversation. A dealership that helps shoppers with credit challenges can make the process easier to understand while they shop for a vehicle. That help does not mean approval is automatic or that every applicant receives the same options.
For shoppers in Chandler, Mesa, Tempe, Phoenix, Queen Creek, and San Tan Valley, dealership-assisted financing can connect the vehicle search with the application process. Staff can discuss what you need, help you explore used vehicles, and explain how to begin an application. Any Credit Auto Sales works with third-party lenders. Those outside financial institutions review applications and make lending decisions.
What does a low-credit car dealership actually do?
A dealership can guide you through choosing a vehicle and submitting a financing application. That may include explaining what information the application requests and how it is sent to outside lending partners. The dealership supports the process, but it doesn’t provide the loan or decide whether a lender approves it.
That distinction matters. A lender reviews the application and sets any offer it is willing to make, including the terms. Dealership staff can help you understand the process, but they can’t promise a particular decision, rate, or loan structure. For a broader overview of how loans fit into car finance, you can review different ways vehicle purchases may be funded.
Think of the dealership as a guide between your vehicle search and the application, not as the lender. This can make the process easier to follow, especially if you haven’t applied for a vehicle loan before. Ask for unfamiliar terms to be explained in plain language, and take the time you need to understand the information before deciding.
Does a low credit score automatically end your options?
No single score tells you exactly what a lender will decide. A credit score is one part of an application review, and lenders may assess applications differently. Your score can affect the options available, but it doesn’t provide a guaranteed answer before a lender reviews your application.
A credit score alone cannot promise or rule out approval. The lender makes that decision after reviewing the application. A dealership can help you take the next step, but it shouldn’t present a possible outcome as certain. Be cautious of promises about guaranteed approval or specific terms before a lender has reviewed your information.
If you’re considering a low credit score car dealership Arizona shoppers can visit, focus on understanding who reviews your application and what happens next. Use the conversation to learn how the process works, then review any lender offer carefully to decide whether it fits your needs.
How Arizona dealership-assisted financing works with third-party lenders
Dealership-assisted financing gives you support with the application process while an outside lender reviews your request. At Any Credit Auto Sales in Chandler, applicants can connect with third-party lending partners. The dealership doesn’t lend the money. The lender decides whether to approve an application and sets any available terms after reviewing it.
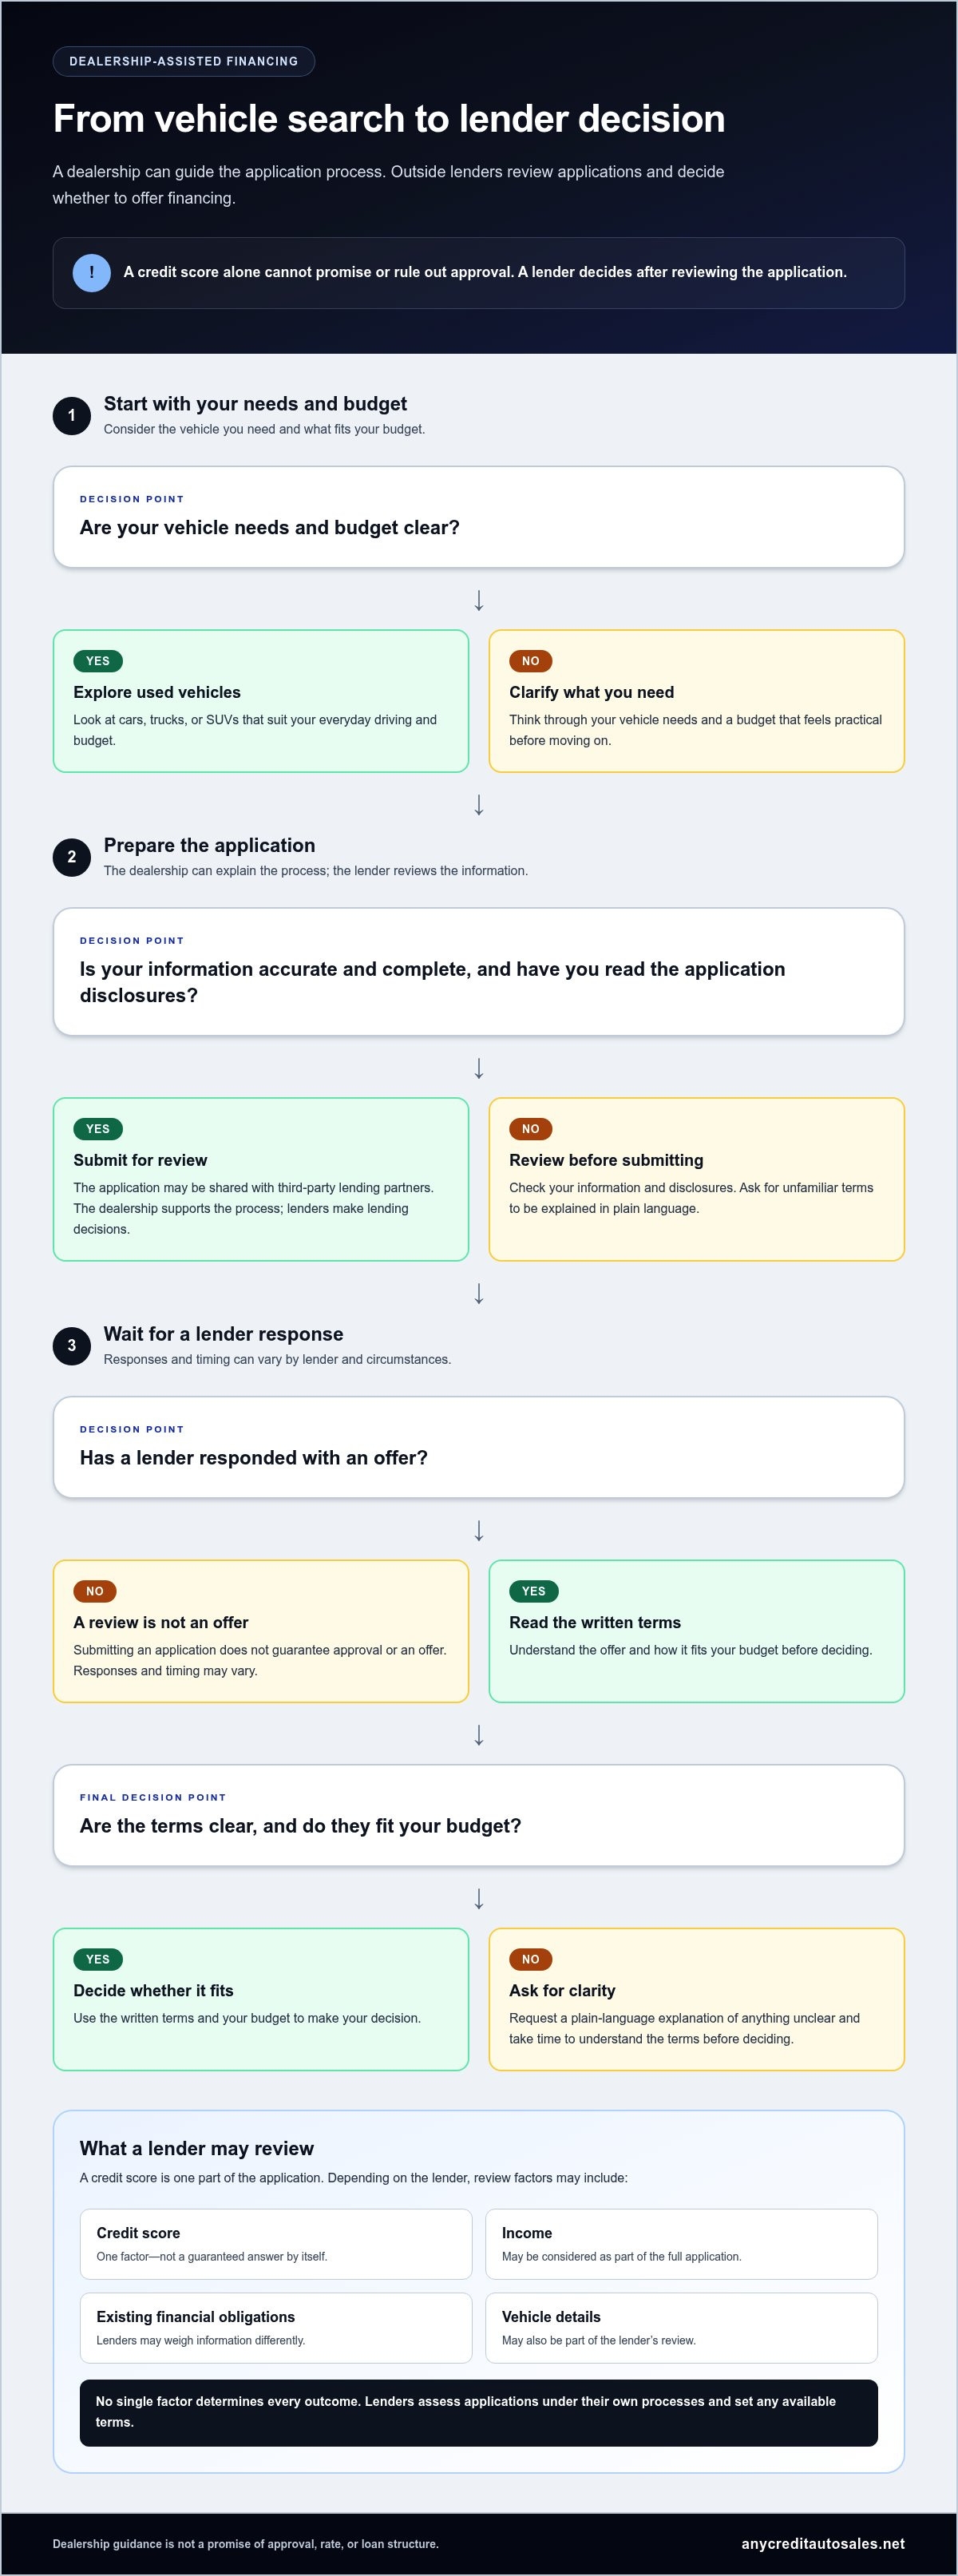
The process is easier to follow when you take it one step at a time:
- Discuss your needs. Consider what kind of vehicle you need and what fits your budget.
- Explore vehicles. Look at used cars, trucks, or SUVs that suit your everyday driving and budget.
- Submit an application. Provide the requested information so lending partners can review it.
- Review available terms. If a lender responds with an offer, understand the terms before deciding.
This sequence connects the vehicle search with the financing conversation while clarifying who handles each decision. A low credit score car dealership Arizona shoppers visit can guide the application, but it can’t promise lender approval or specific terms. The dealership supports your application; the lender makes the lending decision.
What happens after you submit an auto loan application?
After you submit an application, the information may be shared with lending partners for review. Each lender considers it under its own process. Responses and terms depend on the lender and your circumstances, so the number of responses and timing can vary. An application requests a review; it isn’t a guarantee of approval or an offer.
If a lender responds, read the details carefully. Make sure you understand the terms and how they fit your budget before moving forward. If a phrase or figure is unclear, ask for a plain-language explanation.
What information helps lenders review an application?
A lender may consider the full application, not just your credit score. Depending on the lender, review factors may include income, existing financial obligations, and details about the vehicle. Lenders can weigh information differently, so don’t assume one factor determines the outcome.
Before submitting, check that your information is accurate and complete. Read the application disclosures to understand what you’re agreeing to and how your details may be used in the review. Clear, accurate answers present your circumstances honestly, but they can’t guarantee a particular decision.
To take a practical next step, you can start an auto financing application while exploring used vehicles with Any Credit Auto Sales.
Third-party financing, direct loans, and buy-here-pay-here compared
These financing paths differ mainly in who reviews your application and who provides the loan funds. Understanding that distinction helps you compare offers without assuming one approach is right for every shopper. Any Credit Auto Sales uses dealership-assisted third-party financing: staff support the vehicle-shopping and application process, while outside lenders review applications. The dealership does not offer in-house or buy-here-pay-here financing.
| Financing path | Who reviews the application? | Who provides the funds? | What to compare |
|---|---|---|---|
| Dealership-assisted third-party financing | An outside lender | The lender, if it approves the application | Written loan terms, required payments, and total repayment amount |
| Direct loan | A bank, credit union, or other lender you apply to directly | The lender, if it approves the application | The same written terms, and how the offer fits your vehicle budget |
| Buy-here-pay-here financing | The dealership that offers the financing | The dealership | Written terms, payment schedule, and total repayment amount |
How dealership-assisted third-party financing differs
With dealership-assisted financing, staff can help you shop for a vehicle and submit an application to outside lending partners. The lender reviews it and decides whether to offer financing. Available terms can vary based on the lender, your application, and the vehicle. Applying through a dealership that connects shoppers with lenders doesn’t guarantee approval or multiple offers.
This is the financing model at Any Credit Auto Sales in Chandler. It differs from buy-here-pay-here financing, where a dealership provides its own financing. Knowing the difference before you apply helps you understand who reviews your information and who would provide the funds if a loan is offered.
How to compare financing paths fairly
Look beyond the monthly payment. A lower payment may come with a longer repayment period, which means paying for more time. Compare the complete written terms for each offer, including the payment amount and schedule, repayment period, and total amount due over the life of the loan. Check that the vehicle price and financing details are clear.
Read the paperwork and ask for plain-language explanations of terms you don’t understand. Where possible, compare offers using the same vehicle and purchase details so the comparison is useful. The right fit depends on your circumstances and comfort with the full obligation, not just the smallest-looking payment. This general guidance can help you review options, but it isn’t individualized financial or legal advice.
How to prepare and compare an Arizona low-credit auto loan offer
Preparation can help keep your vehicle search grounded in what works for your budget. Before discussing financing, decide what you can comfortably spend and organize the information you may need for an application. That gives you a clear starting point, whether you’re shopping in Chandler or exploring used vehicles in Mesa, Tempe, Phoenix, Queen Creek, or San Tan Valley.
Set your budget before choosing a vehicle. Consider your regular expenses and leave room for the costs of owning a car, not only the loan payment. A payment that looks manageable by itself may feel different when you consider the rest of your monthly budget.
What should you prepare before starting the conversation?
Gather accurate details about your identity, residence, income, and the vehicle you’re considering. Organizing this information can make it easier to complete an application carefully. Requirements can vary, so use this as a preparation list, not a promise that any one document or down payment will lead to approval.
- Set a vehicle spending limit that feels realistic for your current budget.
- Consider ownership costs beyond the loan payment.
- Organize accurate personal, residence, and income information.
- Write down questions about the application or any offer.
Keep your limit in mind while you shop. If a vehicle or offer pushes your budget too far, pause and consider whether another option would fit better. Take time to understand your choices before moving ahead.
What should you compare when reviewing an offer?
Read the written terms as a whole. Look for the annual percentage rate (APR), payment amount and schedule, loan length, and total repayment amount. Confirm that the vehicle details and the terms match the purchase you’re considering. If a figure or phrase is unclear, ask for a plain-language explanation before making a decision.
Compare the complete written loan terms, not just the monthly payment. A lower payment may come with a longer repayment period, so consider how long you’ll pay and the full amount due. Then decide whether both the vehicle and the overall repayment fit your current budget. An offer is useful only if its terms feel manageable for your circumstances.
If you searched for “low credit score car dealership Arizona,” use that search as a starting point, not a reason to rush. Any Credit Auto Sales in Chandler works with outside lending partners and offers credit guidance as you explore used vehicles. You can browse pre-owned vehicles and explore financing as a practical next step.
Explore used-car financing with Any Credit Auto Sales in Chandler
Shopping for a vehicle with credit concerns can bring up questions. Any Credit Auto Sales is a used-car dealership in Chandler that offers credit guidance and support with financing applications. Staff can help you understand the steps and explore a vehicle that fits your needs, without treating your credit history as a judgment.
Financing applications connect with outside lenders. Those lenders review each application and decide whether to offer financing, along with any available terms. The dealership can explain the process and the choices presented, but it can’t promise approval, a particular rate, or specific loan terms. Review any offer in writing before deciding.
What support can shoppers expect from the dealership?
Your credit history is personal, and it’s reasonable to have questions about how it may affect a vehicle search. Dealership staff provide practical credit guidance and explain how the application process works. They can also help connect your vehicle search with an application reviewed by outside lenders.
This support can make the steps easier to follow, but the lender makes the financing decision. Any available options depend on the lender’s review and your circumstances. Ask for unfamiliar terms to be explained clearly, then consider whether the vehicle and written offer fit your budget.
How can Arizona shoppers take the next step?
Start by browsing pre-owned cars, trucks, and SUVs. Shoppers in Chandler, Mesa, Tempe, Phoenix, Queen Creek, San Tan Valley, and nearby communities can explore options and note which vehicles suit their everyday needs. Keep your budget in mind as you browse so you can focus your financing conversation on realistic choices.
When you’re ready, begin an application and provide accurate information. If an outside lender offers terms, read the full written details carefully, including the payment, loan length, and total repayment amount. An application is a step toward understanding possible options, not a guarantee of a particular outcome.
If you’re looking for a low credit score car dealership Arizona shoppers can visit for used vehicles and application support, Any Credit Auto Sales offers a place to begin. Browse inventory and start a financing application when you’re ready, then take time to make a considered choice. Browse inventory and start your financing application.
Take your next step at a pace that feels right
You don’t have to decide everything at once. Start with the kind of vehicle that would make daily life easier, then review any financing details before choosing how to move forward. A useful first step may simply be browsing the inventory and identifying vehicles that fit your needs and budget.
If you’re looking for a low credit score car dealership Arizona shoppers can turn to while exploring used vehicles, begin with an option that feels manageable. Browse first, start an application when you’re ready, and leave yourself time to make a considered choice.
Browse pre-owned vehicles and start your financing application. Any Credit Auto Sales serves shoppers in Chandler, Mesa, Tempe, Phoenix, Queen Creek, and San Tan Valley. Take the process one step at a time and move forward when the choice feels right.
Frequently Asked Questions
Can I get a car loan in Arizona with a low credit score?
Possibly. A low score doesn’t automatically rule out a loan, but only a lender can decide after reviewing an application. If you’re searching for a “low credit score car dealership Arizona” shoppers can visit, Any Credit Auto Sales in Chandler connects applicants with outside lending partners. Shoppers in Chandler, Mesa, Tempe, Phoenix, Queen Creek, and San Tan Valley can explore vehicles and financing support, then consider any offer against their budget.
Does a low credit score automatically prevent auto loan approval?
No. A credit score alone doesn’t determine the outcome, and no score guarantees approval or denial across all lenders. A lender reviews the application and makes its own decision. If you’re unsure what a response means, focus on the lender’s stated reasons and conditions. Don’t treat a preliminary conversation as a final decision, and review any offer carefully before accepting it.
Does Any Credit Auto Sales offer buy-here-pay-here financing?
No. Any Credit Auto Sales doesn’t offer buy-here-pay-here or in-house financing. The dealership helps applicants connect with third-party lenders, which review applications and make lending decisions. The dealership isn’t the source of the loan funds. Knowing the difference helps clarify who makes the decision and whose written terms you’ll review if financing is offered.
What is the difference between dealership-assisted financing and a direct auto loan?
With a direct auto loan, you apply to a lender yourself. With dealership-assisted financing, dealership staff support the vehicle-shopping and application process, and outside lending partners review the application. Either way, the lender makes the decision and provides funds if it approves the loan. Consider which process feels clearer to you, and make sure you understand who will review your application.
What should I compare before accepting an auto loan offer?
Review the offer’s APR, amount financed, payment schedule, loan length, and total repayment amount. Check that the vehicle and any listed charges match what you expect to purchase. Consider whether the payment due dates work with your household budget. If a term or line item is unclear, get an explanation before agreeing. The full written offer gives you a better basis for deciding than one number alone.
Will applying for auto financing affect my credit score?
It may. A formal loan application can lead to a hard credit inquiry, which may affect your score. A preliminary inquiry may be treated differently, so don’t assume every application has the same effect. Before submitting, read the application disclosures and ask whether the lender will make a hard inquiry. That way, you know what to expect before sharing your information for a financing review.
Can I browse used cars before submitting a financing application?
Yes. You can look through used cars, trucks, and SUVs before starting an application. Browsing first can help you identify the type of vehicle that suits your needs and create a shortlist within your budget. Then you can decide whether you’re ready to apply. Vehicle availability can change, so use the current inventory as a guide while considering your options.


