
Could a car loan help rebuild your credit, or add pressure to an already tight budget? If you’re searching “rebuild credit with car loan Arizona,” focus on two questions: whether the lender reports your payments and whether the loan fits your finances.
An auto loan isn’t a shortcut to a higher credit score. If a lender reports your account and you make payments on time, that history may support your credit profile over time. But a payment you can’t comfortably manage may create more stress, so understand the terms before you apply.
This guide explains what to look for in credit reporting, how to assess whether a monthly payment is manageable, and what to consider when comparing loan terms. You’ll also learn how a financing application can connect you with third-party lenders and how dealership guidance can help you understand your options. Whether you’re shopping in Chandler, Mesa, Tempe, Phoenix, Queen Creek, or San Tan, take a steady, informed approach. Approval and credit improvement aren’t guaranteed.
Key Takeaways
- A car loan may support credit rebuilding when payments are reported and made on time, but borrowing alone won’t rebuild your credit.
- Before you rebuild credit with car loan Arizona financing, make sure the payment fits your budget alongside your other expenses.
- Compare written loan terms carefully, including the payment schedule, and understand the agreement before signing.
- Plan for payments and review your credit records so you can spot issues and stay on track.
- Any Credit Auto Sales LLC in Chandler offers credit guidance and financing applications that connect shoppers with third-party lenders. Approval and score increases aren’t guaranteed.
Can an Auto Loan Help Rebuild Credit in Arizona?
A car loan may help you build a stronger credit record, but borrowing by itself doesn’t rebuild credit. The potential benefit depends on what happens after the loan begins: whether the account is reported, whether you make payments as agreed, and whether the loan is manageable. Approval and a higher credit score aren’t guaranteed.
Credit rebuilding means developing a stronger record of responsible credit use over time. If you’re exploring how to rebuild credit with car loan Arizona financing, focus on the conditions that could make the loan useful, not just on getting approved.
What does rebuilding credit with a car loan mean?
An auto loan is an installment account. You borrow an amount to buy a vehicle and repay it through scheduled payments. If the lender reports the account to credit bureaus, payment activity may appear in your credit files. If it isn’t reported, your payments may not appear there, even when you pay on time.
Put simply: Reported, on-time car payments can add a record of responsible repayment to your credit history, but they don’t guarantee a score increase. Credit scores reflect multiple details in your credit history, and scoring approaches may weigh those details differently. For a general overview, see Understanding Credit Scores.
Separate the possible benefit from the result you hope for. A reported loan can contribute payment information to your file, but it doesn’t erase past late payments, ensure a particular score change, or guarantee future loan approval. Think of it as one possible part of a longer credit-building effort.
Who in Arizona may be considering this option?
You may be looking at an auto loan after missed payments, a limited credit history, or another financial setback. Those experiences can make financing feel uncertain, but they don’t mean the same choice is right for everyone. Your income, regular expenses, savings, and other debts all matter when deciding whether a new payment is realistic.
For residents of Chandler and the East Valley, dependable transportation may be a day-to-day need for commuting, family responsibilities, or getting to work. But needing a car doesn’t automatically make a loan affordable. Consider the full commitment, including the regular payment and other ownership expenses, before applying. If the payment would leave too little for essentials or unexpected costs, waiting or revisiting your vehicle budget may better protect your goals.
Start with two questions: Will the lender report the account, and can I make every payment on time without putting other needs at risk? The next sections explain how reporting works and how to weigh the potential credit-history benefit against the ongoing obligation.
How On-Time Car Payments May Affect Your Credit History
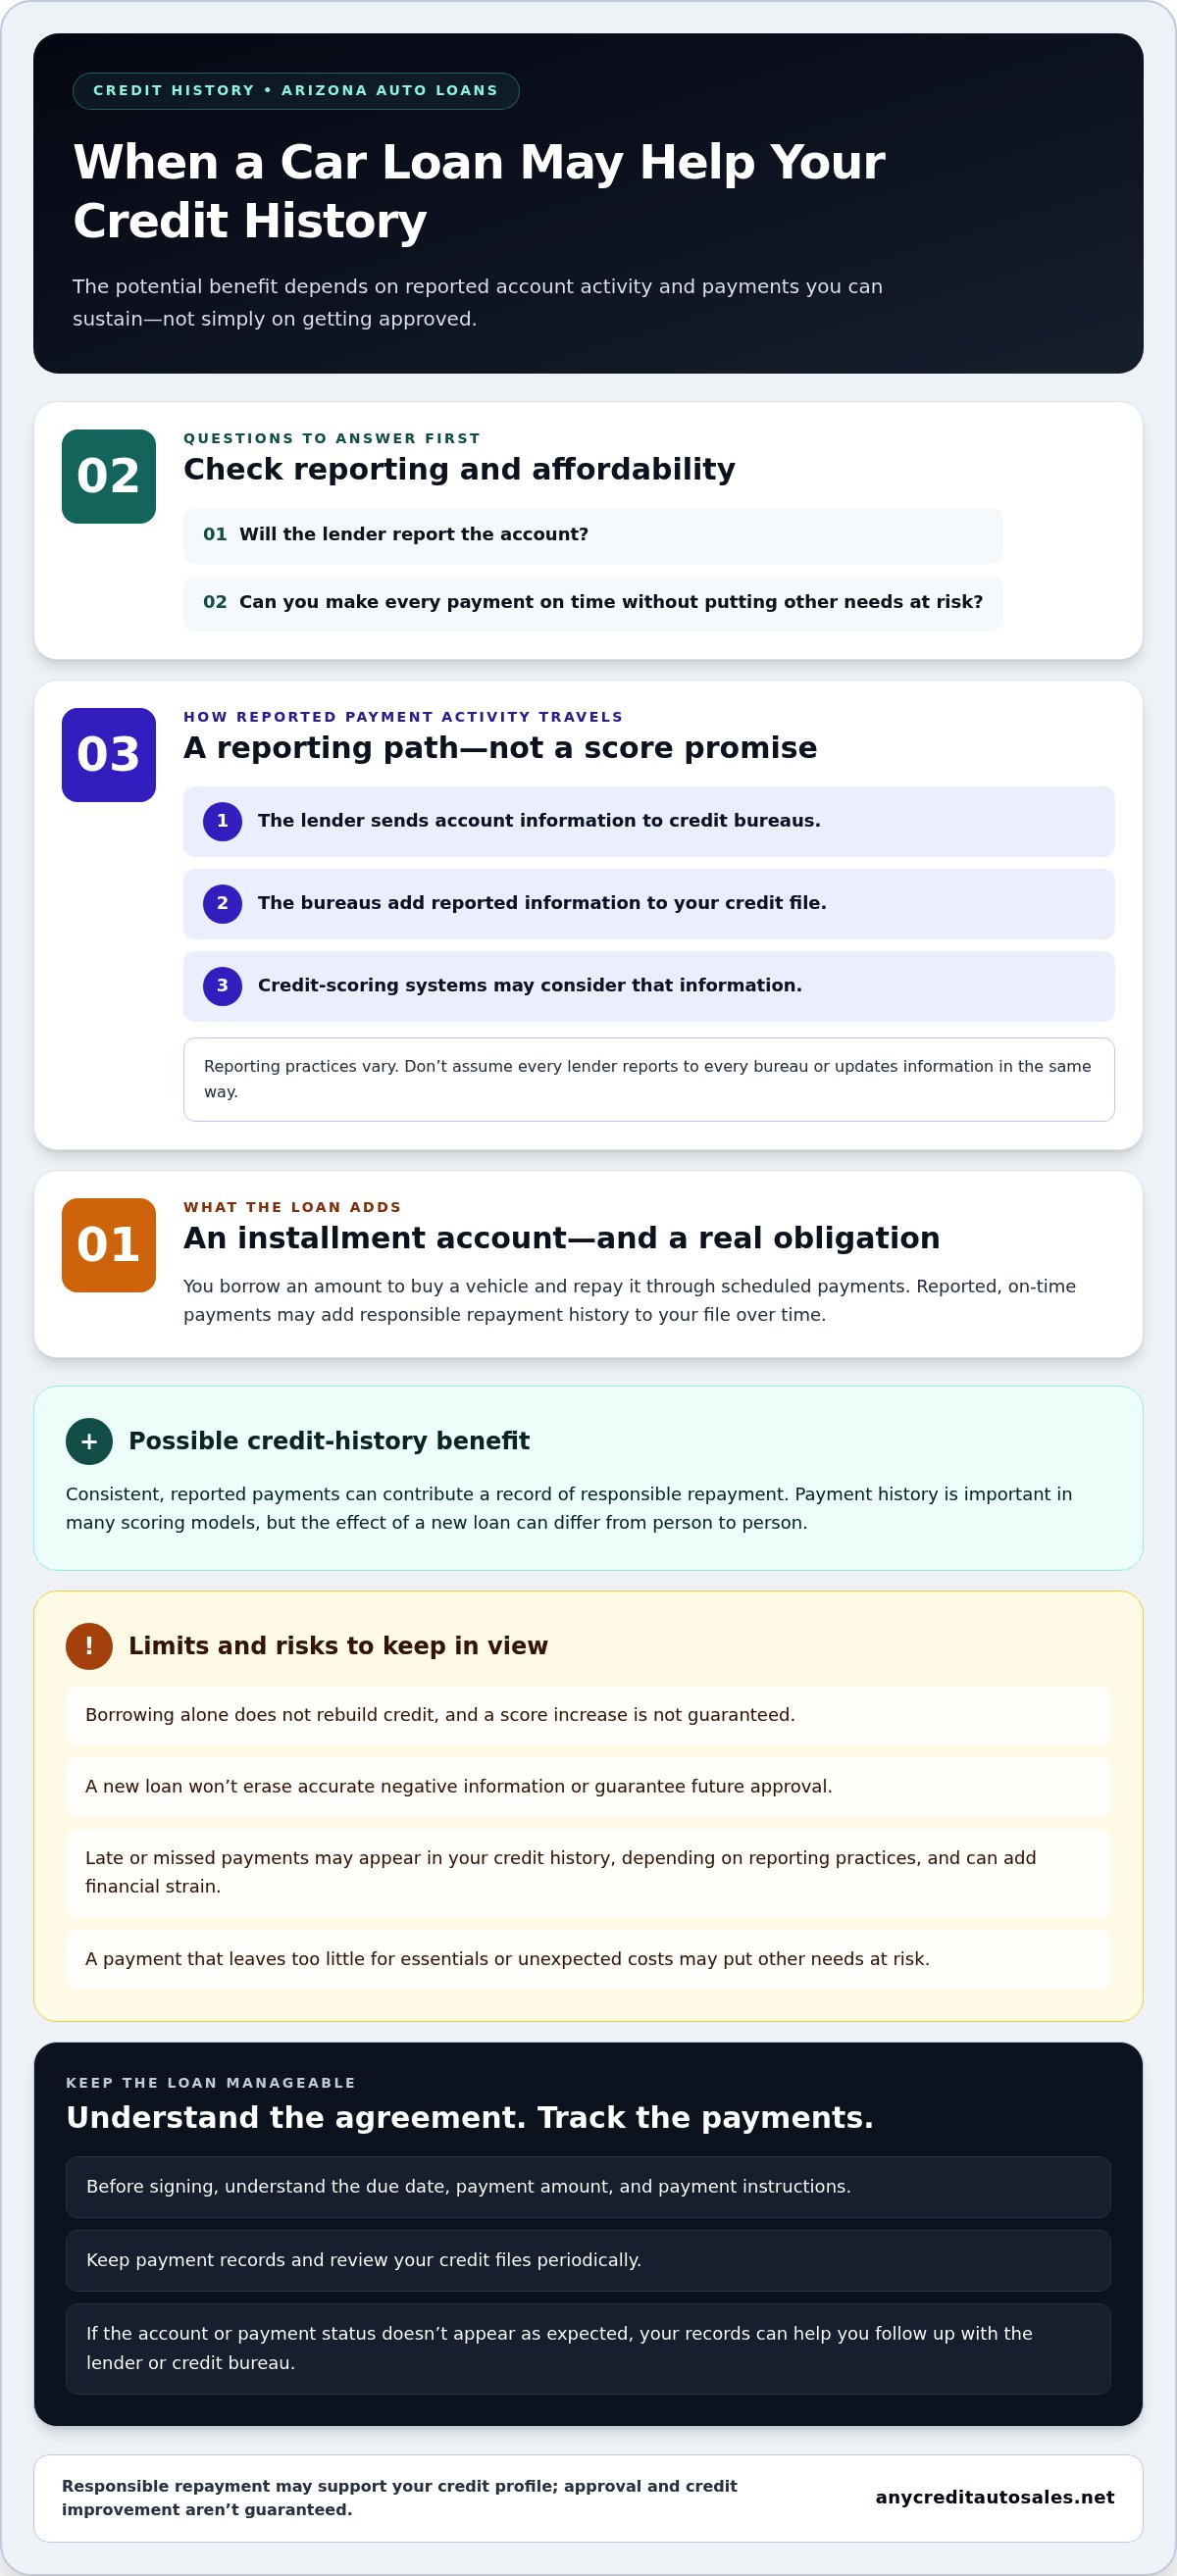
A car payment can contribute to your credit history only if the account and payment activity are reported. The lender sends account information to credit bureaus, the bureaus add that information to your credit file, and credit-scoring systems may consider it when calculating a score. Reporting practices vary, so don’t assume every lender reports to every bureau or updates information in the same way.
Reported, on-time payments can add positive repayment history to your credit file, but they can’t guarantee a particular credit-score change. That distinction matters if you’re researching “rebuild credit with car loan Arizona.” The goal is a steady record of responsible payments, not a promised score result.
Why payment history matters
Payment history is an important part of many credit-scoring models. Paying an installment loan as agreed may show how you’ve handled that obligation. Still, a scoring model considers your broader credit file, including other accounts and past payment activity. The effect of a new loan can differ from one person to another.
Consistent payments are more useful than borrowing solely to pursue a score. A loan creates a real obligation. If you don’t need a vehicle or the payment doesn’t fit your budget, taking on debt just to add an account may create avoidable pressure. If you do need a car, focus on terms you can manage and making every scheduled payment on time.
Before signing, read the agreement and understand the due date, payment amount, and payment instructions. Once the account is open, keep payment records and review your credit files periodically. If the account or payment status doesn’t appear as expected, your records can help you follow up with the lender or credit bureau.
What a car loan cannot do on its own
A new auto loan won’t erase accurate negative information already in your credit report. It can’t guarantee approval on a future application, a specific score increase, or a set timeline for rebuilding. Credit progress depends on your overall file and continued credit habits, not simply on having an open loan.
Missed payments can create another challenge. Depending on the lender’s reporting practices, late or missed payments may appear in your credit history. They can also make the loan harder to manage and add financial strain. If a payment problem arises, review your agreement and contact the lender promptly to understand your options. A new loan won’t fix earlier setbacks on its own.
For Chandler and East Valley shoppers weighing a vehicle purchase, Any Credit Auto Sales LLC offers credit guidance and financing applications that connect buyers with third-party lenders. Explore vehicle financing options while keeping your focus on manageable terms and a payment plan you can sustain.
Car Loan for Credit Rebuilding: Weigh the Benefits Against the Risks
A car loan has two sides: it may add reported payment history to your credit file, and it creates a commitment you need to manage month after month. Before you decide to rebuild credit with car loan Arizona financing, weigh both sides. The aim isn’t simply to add an account. It’s to choose transportation and a payment plan that can work for you.
| What to weigh | Possible upside | Responsibility or uncertainty |
|---|---|---|
| Credit history | If the lender reports the account and you pay as agreed, payment activity may contribute to your credit history. | Reporting practices vary, and an account can’t guarantee a score increase or future approval. |
| Monthly payment | A predictable payment schedule may help you plan repayment. | The payment remains due even when other expenses rise or income changes. |
| Vehicle choice | Financing may help you get transportation you need. | The loan’s full terms and ownership expenses can add pressure beyond the monthly payment alone. |
When financing may fit your situation
Financing may be worth considering if you need a vehicle, have a dependable payment plan, and can fit the commitment alongside your existing bills. Look at income stability, current debt payments, and regular household expenses. Leave room for ordinary surprises, too. Credit rebuilding can be a secondary benefit of financing a vehicle you genuinely need, not the only reason to borrow.
Separate the transportation decision from the credit goal. First, consider what kind of vehicle meets your daily needs. Then review the written loan terms and decide whether the payment works in your budget. Look beyond the monthly amount: the loan length and total amount you’ll repay show more of the full commitment.
When a car loan may add too much pressure
Pause if the payment would compete with housing, utilities, insurance, groceries, or other essentials. A payment that looks manageable on paper can feel different once regular ownership expenses and changing household needs are included. If you’d have to stretch your budget every month, the loan may work against your broader financial goals.
Don’t choose a more expensive vehicle just to add a credit account or pursue a possible score benefit. A larger obligation doesn’t guarantee a better credit outcome. Consider a less costly vehicle, delaying the purchase, or revisiting your budget if the terms leave too little breathing room. Protecting your ability to meet essential expenses is a practical part of rebuilding financial stability.
A useful test is whether you’d still choose the vehicle and payment if the loan had no effect on your credit score. If not, reconsider why you’re borrowing. If you need the vehicle and the terms fit your budget, any potential credit-history benefit can be one factor in your decision, not a promise or a substitute for affordability.
A Practical Arizona Plan for Managing an Auto Loan Responsibly
A steady plan starts before you apply and continues after your first payment. Take these steps to keep the decision grounded in your budget and make it easier to track your loan.
- Review your finances. Write down reliable income, housing costs, utilities, existing debt payments, and other essentials. Decide what vehicle payment could fit without leaving too little for everyday needs or unexpected expenses.
- Compare written terms. Look beyond the monthly payment. Read the full loan agreement, understand the amount financed and repayment terms, and make sure you know the due date and payment instructions. Don’t sign until the terms are clear to you.
- Plan your payments. Set reminders based on the due date and payment schedule in your agreement. Build the payment into your monthly budget so it doesn’t compete with essential bills at the last minute.
- Monitor your records. Keep copies of your agreement, payment confirmations, and lender communications. Review your credit reports periodically for accurate account details and payment status.
Prepare before submitting an auto-loan application
Use accurate income, housing, and debt information to shape your budget before choosing a vehicle. Set a manageable payment range first, then consider options that fit it. A dealership financing application may connect you with third-party lenders, but it doesn’t promise approval or specific terms. If you’re considering how to rebuild credit with car loan Arizona financing, a realistic budget is a useful starting point.
Any Credit Auto Sales LLC provides credit guidance and an application process that connects shoppers with third-party lenders. You can submit a vehicle financing application after reviewing your finances and deciding you’re ready to explore financing options.
Build payment habits that are easier to maintain
Choose a reminder that fits your routine, such as a calendar alert several days before the due date. If your budget allows, set aside the payment amount ahead of time. Follow the loan’s actual schedule rather than assuming the date matches other bills. Small habits can make a recurring obligation easier to manage.
If you think you may miss a payment, contact the lender promptly to discuss the situation and understand any available options. Keep notes about the conversation and save related messages. Don’t wait and assume the issue will resolve on its own.
Check your credit reports through official channels and compare the auto-loan details with your records. If you spot an error, follow the credit bureau’s official dispute process and provide supporting documents. You can also contact the lender that supplied the information. Keeping records makes it easier to explain what appears incorrect and track your follow-up.
Explore Credit Help and Vehicle Financing in Chandler, Arizona
If you’re considering an auto loan, keep the main takeaway in mind: reported, on-time payments may contribute to your credit history, but affordability and consistency come first. A loan won’t guarantee a score increase or approval later. It should make sense as transportation and as a commitment you can manage.
How dealership guidance can support your next step
Credit questions can feel personal, especially after missed payments or other financial setbacks. Any Credit Auto Sales LLC offers credit guidance to shoppers with varied credit histories. The guidance helps you understand financing choices and consider how they fit your needs, without promising a particular result.
The dealership’s financing application connects shoppers with third-party lenders. Those lenders review applications and determine whether to approve financing and what terms may apply. Consider the questions that matter to your decision: Does the vehicle meet your transportation needs? Do the written terms make sense? Can the payment fit alongside your regular expenses?
This practical review keeps the focus on a manageable decision rather than an assumed credit outcome. If your goal is to rebuild credit with car loan Arizona financing, remember that the loan is still a financial obligation. Any possible benefit to your credit history depends on lender reporting and your payment activity, and it isn’t guaranteed.
Start with a clear, manageable plan
Before applying, know the payment range that feels realistic for your household. Then consider which vehicle suits your daily use. Shoppers in Chandler, Mesa, Tempe, Phoenix, Queen Creek, and San Tan can explore Any Credit Auto Sales LLC’s pre-owned cars, trucks, and SUVs with their transportation needs and budget in mind. Comparing vehicles against those priorities can help you consider the full commitment, not just a loan offer.
The online financing application begins the process of connecting your application with third-party lending partners. It doesn’t guarantee approval or specific terms. Review any written offer carefully, including the payment schedule and full loan agreement, before deciding whether to proceed. Take the time you need to understand what you’d be agreeing to.
Credit rebuilding is gradual, and a car purchase doesn’t have to carry the weight of fixing everything at once. Make a thoughtful choice by starting with a clear transportation need, a payment that fits your budget, and an honest understanding of the loan terms. Whether you’re comparing options or ready to explore financing, take the next step at your own pace.
Chandler and East Valley shoppers can explore Any Credit Auto Sales LLC’s pre-owned inventory or begin a financing application when they’re ready.
Choose a Next Step That Feels Manageable
You don’t have to make the whole decision at once. Start by naming what you need from a vehicle and what you want your budget to protect. A clear limit gives you room to compare options without feeling rushed, and it’s okay to pause if the terms don’t feel right.
If you’re researching “rebuild credit with car loan Arizona,” focus on a choice that makes sense beyond the hope of a score change. Your financial history is personal, and a past setback doesn’t define your next decision. Take time to review the details, clarify any terms you don’t understand, and move ahead only when the commitment feels realistic.
When you’re ready to look at vehicles and financing, explore the available options at your own pace. View pre-owned vehicles and begin a financing application. Take it one step at a time, with your needs and peace of mind leading the way.
Frequently Asked Questions
How long does it take to rebuild credit with a car loan?
There’s no fixed timeline. A credit file changes as new information is reported, and scoring results depend on your overall credit history and the scoring model used. If you’re comparing ways to rebuild credit with car loan Arizona financing, focus on steady habits rather than a target date. Keep account statements and payment confirmations so you can check whether your records match the lender’s updates.
Can one late car payment hurt your credit?
Yes, a late payment may hurt your credit, though the effect depends on your full credit file and how the lender reports the account. If you realize a payment is overdue, check your loan agreement and contact the lender promptly. Save payment confirmations and communications. If your records show you paid on time but the account is marked late, use that documentation to follow up about the discrepancy.
Does paying off a car loan early help your credit score?
Not necessarily. Paying early may reduce the interest you pay, depending on your agreement, but a score change isn’t guaranteed. Once the loan is paid off, the account may close, changing the mix of open accounts in your credit file. Before making extra payments, review your contract for how early payoff is handled and consider whether keeping funds available for essential expenses is more useful.
Can I rebuild credit with a car loan if I have no credit history?
Possibly, if a lender approves your application and reports the account, but having no credit history doesn’t ensure approval or favorable terms. A lender may consider information such as income, existing obligations, and application details. Before applying, decide whether the payment fits your budget even if the loan doesn’t lead to the credit result you hope for. A first account is one part of building a broader credit record.
Should I take out a car loan just to build credit?
Usually, borrowing solely to add an account deserves careful thought because a car loan creates a long-term payment obligation. Consider financing if you also need a vehicle and the full commitment fits your budget. For shoppers in Chandler, Mesa, Tempe, Phoenix, Queen Creek, or San Tan, the same principle applies: choose transportation for practical needs, not just for a possible score effect.
Will applying for an auto loan affect my credit?
It may. A lender may check your credit as part of reviewing an application, and that check can be recorded as a hard inquiry. The effect varies by credit file and scoring model. Before submitting applications, understand whether a credit check is involved and avoid applying without a clear vehicle budget. Keep track of applications and review your credit file afterward for inquiries you don’t recognize.
Do auto lenders report payments to all three credit bureaus?
No, don’t assume every lender reports to all three nationwide credit bureaus. Reporting can differ by lender and bureau, so a loan may appear in one credit file but not another. Check your reports periodically and compare the account details with your statements. If information is missing or looks wrong, contact the lender and follow the bureau’s official process for asking about or disputing the record.


